Categories
Articles Articles Blogs Let Property Campaign

Self Assessment Tax Return Errors: How Long Do You Have to Make a Correction?

There isn’t just one deadline for correcting a Self Assessment error — there are several, and which one applies depends on how the correction affects your tax bill, how long ago the return was filed, and whether HMRC has already noticed the issue themselves. Understanding these different time limits helps you work out exactly where you stand, and how urgently you need to act.

Not sure which correction window applies to your situation? Book a free 15-minute consultation with Felix Accountants. Book your free call here.

The Standard Amendment Window: 12 Months

For most straightforward corrections, you have 12 months from the original filing deadline to amend your return, whether online or on paper. For example, a 2024/25 return with a filing deadline of 31 January 2026 can be amended up until 31 January 2027. Within this window, corrections are relatively simple — log in to your HMRC online account (after a required 72-hour wait following the original submission), update the figures, and resubmit.

After 12 Months, But Within Four Years: Over-payment Relief

If you’ve missed the standard 12-month amendment window and the correction would mean you’d overpaid tax, you can make a formal claim for “over-payment relief.” This must generally be submitted within four years from the end of the tax year the return relates to, and requires a written claim to HMRC rather than a simple online amendment — including the tax year involved, the reason for the correction, the amount overpaid, and a signed declaration.

Underpayments Outside the 12-Month Window

If the correction means you owe more tax, rather than less, there isn’t a similarly generous window — you should notify HMRC as soon as you become aware of the error, regardless of how long ago the original return was filed. Voluntarily correcting an underpayment, even years later, is still treated far more favourably than waiting for HMRC to discover it independently, since it keeps the disclosure classed as unprompted for penalty purposes.

How Long Does HMRC Have to Challenge Your Return?

It’s worth understanding the position from HMRC’s side too, since it affects how long a genuine error could remain “live.” HMRC’s general time limits for opening a “discovery assessment” — essentially, going back and adjusting a previous year’s tax — depend on the reason for the inaccuracy:

  • 4 years from the end of the relevant tax year, for genuine mistakes made despite taking reasonable care
  • 6 years from the end of the relevant tax year, where the taxpayer failed to take reasonable care (a careless error)
  • 20 years from the end of the relevant tax year, where the error was deliberate

Our guide on HMRC’s tax look-back periods covers this framework in more detail, and it’s the same underlying structure used to determine how many years landlords need to cover in a Let Property Campaign disclosure.

Why Acting Quickly Still Matters, Even Within a Longer Window

Even where you’re technically still within a four-year or longer window to correct something, waiting has real costs. Interest accrues on any underpaid tax from the original due date, regardless of when you get around to correcting it, so delaying simply increases the amount ultimately owed. There’s also a meaningful difference in how penalties are calculated between a genuinely prompt, voluntary correction and one that drags on for years before being addressed — our guide on prompted versus unprompted disclosures explains this distinction, and the same underlying principle applies to routine error correction, not just formal disclosure campaigns.

A Practical Summary of the Time Limits

SituationTime Limit
Standard online/paper amendment12 months from the original filing deadline
Claiming a refund after the 12-month window (over-payment relief)4 years from the end of the relevant tax year
Voluntarily correcting an underpaymentNo fixed deadline — correct as soon as discovered
HMRC discovery assessment: genuine mistake, reasonable care taken4 years from the end of the relevant tax year
HMRC discovery assessment: careless error6 years from the end of the relevant tax year
HMRC discovery assessment: deliberate inaccuracy20 years from the end of the relevant tax year

What Happens If You Miss the Self Assessment Filing Deadline Entirely?

It’s worth distinguishing between correcting an error on a filed return and simply filing late in the first place. Missing the original Self Assessment deadline triggers its own automatic penalties, starting immediately after the deadline and increasing the longer the return remains outstanding. Our guide on HMRC’s penalties for missing the tax deadline covers this separate scenario, and our wider guide to key UK tax year dates and deadlines maps out the full annual calendar.

Special Cases: Multiple Years and Ongoing Income Sources

Where an error relates to an income source that’s been consistently under-reported across several years — such as rental income — each year technically has its own time limits, but it’s usually more practical to address them together through a structured process, rather than a series of separate corrections. This is exactly the situation the Let Property Campaign is designed for when the underlying issue is rental income specifically.

How Felix Accountants Can Help

We help clients work out exactly which correction route and time limit applies to their specific situation, whether that’s a straightforward in-year amendment, a formal over-payment relief claim, or a multi-year rental income disclosure. Our guide on HMRC compliance covers the wider penalty and behaviour framework that underpins all of this.

Frequently Asked Questions

What’s the deadline to amend a Self Assessment return online?

12 months from the original filing deadline. For example, a return with a 31 January 2026 deadline can be amended online until 31 January 2027.

Can I still get a refund if I missed the 12-month amendment window?

Yes, generally through a formal over-payment relief claim, which must be submitted within four years from the end of the relevant tax year.

Is there a deadline for telling HMRC I underpaid tax?

Not a fixed one in the same way — you should notify HMRC as soon as you become aware of an underpayment, regardless of how long ago the original return was filed, to keep the correction classed as voluntary.

How far back can HMRC go if they discover an error themselves?

Generally 4 years for a genuine mistake, 6 years for a careless error, and up to 20 years where the inaccuracy was deliberate.

Does correcting an old error always trigger a penalty?

Not necessarily. Genuine, voluntary corrections made with reasonable care are often treated leniently, and penalties depend heavily on the underlying behaviour rather than simply how long ago the error occurred.

Let’s work out exactly where you stand. Book your free 15-minute consultation with Felix Accountants.
Categories
Articles Articles Blogs Let Property Campaign

Let Property Campaign and Property Renovation Costs: What Records Should You Keep?

Renovation work is where a lot of Let Property Campaign disclosures get genuinely complicated. Unlike straightforward running costs such as insurance or letting agent fees, renovation spending often sits in a grey area between “repair” (generally an allowable expense against rental income) and “capital improvement” (treated very differently for tax purposes). Getting this distinction right — and having the records to support it — makes a real difference to your disclosure.

Carried out renovation work and not sure what’s claimable? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Repairs vs Capital Improvements: The Core Distinction

This is the single most important distinction to understand before including renovation costs in a Let Property Campaign disclosure:

  • Repairs and maintenance restore the property to its previous condition, or replace something on a “like for like” basis. Examples include fixing a broken boiler, repairing a leaking roof, or replacing a worn carpet with a similar one. These are generally deductible against rental income in the year the cost is incurred.
  • Capital improvements go beyond restoring the property and instead enhance it, extend it, or add something that wasn’t there before — a loft conversion, an extension, or converting a single dwelling into two flats, for example. These aren’t deductible against rental income; instead, they’re generally added to the property’s cost base and only become relevant when calculating Capital Gains Tax on an eventual sale.

Why This Distinction Gets Genuinely Tricky

Many renovation projects mix both categories in a single job. Replacing a dated kitchen with a similar, modern equivalent is generally a repair; replacing that same kitchen while also knocking through a wall to create an open-plan layout introduces a capital element into the same project. Similarly, replacing single-glazed windows with double glazing has historically been accepted by HMRC as a repair, on the basis that double glazing is now the modern equivalent of a like-for-like replacement, even though it’s technically an improvement in performance.

This is exactly the kind of judgement call where professional advice earns its keep — getting the split wrong in either direction either understates a genuine deduction or overstates one, and both create problems in a disclosure.

What About a Property Bought in Poor Condition?

A particularly important rule to be aware of: if a property was purchased in a state of disrepair and renovation work was needed before it could be let at all, HMRC generally treats those costs as capital rather than revenue, even if the individual repairs would otherwise look like straightforward like-for-like work. This is because the cost of bringing a run-down property up to a let-table standard is seen as part of the acquisition cost, not an ongoing running expense of an already-established rental business. If your disclosure involves a property that needed significant work before its first tenancy began, this rule needs particular care.

Capital Allowances: A Separate Consideration

Certain capital expenditure — particularly on furniture, fixtures and equipment in furnished lettings, or on qualifying items in some commercial-adjacent scenarios — may separately qualify for capital allowances, which provide tax relief in a different way from either a straightforward repair deduction or Capital Gains Tax treatment. Our guide on maximising capital allowances for a property investor covers this in more detail, and it’s worth reviewing alongside any wider renovation spending.

What Records You’ll Need

Because the repair-versus-capital distinction depends heavily on the specific nature of the work, the quality of your records matters more here than almost anywhere else in a disclosure. Ideally, you’d retain:

  • Itemised invoices from contractors, breaking down the work done rather than a single lump-sum figure
  • Before-and-after photographs, which can help demonstrate whether work was genuinely like-for-like or represented a real change to the property
  • Planning permission or building control records, where relevant, which often clearly indicate whether work went beyond a simple repair
  • Dates of the work relative to the start of the letting, since per-letting renovation is treated differently from ongoing repairs during an established tenancy
  • Bank statements or payment records confirming amounts paid and to whom

Our broader record keeping guide sets out what to retain across all categories of landlord expenditure, and our allowable expenses guide covers how different cost types are treated.

What If the Original Invoices Are a Single Lump Sum?

It’s common, particularly for older renovation work, to have only a single invoice covering a whole project without a breakdown between repair and capital elements. Where this happens, a reasonable, well-documented apportionment can be made — for example, based on quotes for comparable individual elements of the work, or a contractor’s recollection of the scope, clearly labelled as an estimate. This isn’t ideal, but it’s a workable and accepted approach where the original itemisation genuinely doesn’t exist.

How Renovation Costs Fit Into the Wider Disclosure

Renovation costs need to be allocated to the correct tax year — generally the year the cost was incurred, or in some cases spread differently depending on the nature of the work — and correctly categorised as repair or capital before they can be included in your Let Property Campaign calculation. Our guide on how many years you need to declare is a useful companion resource for understanding the overall disclosure period this fits within.

How Felix Accountants Can Help

Renovation costs are one of the areas we most commonly see get miscategorised in self-prepared disclosures — sometimes understating a genuine repair deduction, sometimes incorrectly claiming capital works against rental income. We review renovation spending line by line, apply the correct treatment, and help you build the record trail to support it, as part of our wider LPC disclosure guidance.

Frequently Asked Questions

Can I claim the cost of a new kitchen against my rental income?

Generally yes, if it’s a like-for-like replacement of an existing kitchen. If the work also involves structural changes, such as an extension or knocking through walls, that capital element isn’t deductible against rental income.

Are double glazing replacement windows a repair or a capital improvement?

HMRC has generally accepted replacing single glazing with double glazing as a repair, treating double glazing as the modern equivalent of the original, even though it’s technically an improvement.

Can I claim renovation costs incurred before my property was first let?

Generally no, if the property needed significant work to bring it up to a let-table standard before the rental business began — this is usually treated as a capital cost of acquisition rather than a revenue expense.

What if I don’t have itemised invoices for old renovation work?

A reasonable, documented apportionment between repair and capital elements can be used where original itemisation genuinely isn’t available, based on the best evidence available.

Do capital improvements ever reduce my tax bill?

Yes, but differently — capital improvement costs are generally added to the property’s cost base and reduce any Capital Gains Tax due when the property is eventually sold, rather than reducing rental income tax in the year the work was done.

Let’s review your renovation costs before you disclose. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Articles Blogs Let Property Campaign

Let Property Campaign: How Should Landlords Calculate Income From Part-Year Rentals?

Very few rental properties are let smoothly from 6 April to 5 April every single year. Tenants move out and there’s a void period before the next one moves in; a property is bought or sold partway through the year; a landlord moves in for a few months between tenancies. When you’re putting together a Let Property Campaign disclosure covering several tax years, working out exactly how much income and which expenses relate to each part-year period is one of the more fiddly calculations — but getting it right matters, since it directly affects how much tax is due for each year.

Working through a disclosure with messy, part-year letting periods? Book a free 15-minute consultation with Felix Accountants. Book your free call here.

Why Part-Year Periods Come Up So Often in LPC Disclosures

Common reasons a property was only let for part of a tax year include:

  • The property was purchased or sold partway through the tax year
  • There was a void period between tenants, sometimes lasting several months
  • The landlord lived in the property for part of the year before letting it out, or moved back in for a period
  • The letting only began partway through the campaign’s relevant period, for example if the property was previously used differently

Each of these scenarios needs its own approach to correctly calculate the income and expenses that actually relate to the letting period, rather than the tax year as a whole.

Step 1: Establish the Exact Letting Dates

Before any calculation can begin, you need to pin down precisely when the letting period started and ended within each relevant tax year. This might come from tenancy agreements, a letting agent’s records, the completion date on a purchase or sale, or bank statements showing when rent first appeared. Where records are incomplete, a reasonable, clearly documented estimate is acceptable, provided the reasoning behind it is explained.

Step 2: Calculate Income for the Actual Letting Period Only

Only rent actually received (or due, if using the accruals basis) during the period the property was genuinely let should be included as rental income for that tax year. If a property was let from 1 October to 5 April in a particular tax year, only the rent relating to that six-month window counts as income for that year — not a full year’s worth of rent apportioned evenly, unless the actual rent received happens to align with that.

Step 3: Apportion Ongoing Costs Correctly

This is where part-year calculations get more technical. Some costs relate specifically to the letting activity and should only be claimed for the period the property was actually let or genuinely available to let; others are ongoing regardless of tenancy status and need a different treatment:

  • Costs directly tied to the letting period: letting agent management fees, for example, generally only apply while a tenancy is active or the property is being actively marketed
  • Costs that continue regardless of tenancy: mortgage interest, buildings insurance, and ground rent are often payable whether or not the property is currently tenanted, and can generally still be claimed for the full ownership period within the tax year, including reasonable void periods, as long as the property was genuinely held as part of a rental business rather than for personal use
  • Costs relating to personal use periods: if the property was genuinely used as a personal residence for part of the year, expenses relating to that period generally can’t be claimed against rental income at all

Our detailed guides on property expenses and allowable expenses for property investors cover which costs fall into each category in more depth.

Void Periods: What Counts as “Still Let”?

A genuine void period — where the property is empty between tenants but still being actively marketed and available to let — is generally still treated as part of the rental business, meaning ongoing costs during that gap remain claimable. This is different from a period where the property was deliberately taken off the market, used personally, or left vacant with no active intention to re-let, which would generally break the continuity of the letting business for that portion of the year.

Worked Example

PeriodStatusTreatment
6 April – 30 JuneTenanted (rent received)Rent counted as income; full costs claimable
1 July – 30 SeptemberVoid, actively marketedNo rental income; ongoing costs (mortgage interest, insurance) still claimable
1 October – 5 AprilTenanted (new tenant, rent received)Rent counted as income; full costs claimable

In this example, the full tax year’s ongoing costs would generally still be claimable, while rental income only reflects the two tenanted periods.

What If the Property Was Bought or Sold Partway Through the Year?

Where a property was purchased or sold during a tax year covered by the disclosure, only the period of actual ownership and letting is relevant — there’s no rental income or expense claim for the period before purchase or after sale. If the sale itself wasn’t reported separately, it’s also worth checking whether a Capital Gains Tax reporting obligation applies alongside the Let Property Campaign disclosure; our Capital Gains Tax guide covers this side of the picture.

Documenting Your Approach

Because part-year calculations involve a degree of judgement — particularly around whether a void period counts as ongoing letting activity — it’s important to document the reasoning behind each apportionment clearly. This protects the disclosure if HMRC has questions later, and shows a consistent, defensible methodology rather than figures that were simply estimated without explanation. Our record keeping guide sets out what’s worth retaining to support this.

How This Fits Into the Wider Look-Back Calculation

Part-year calculations need to be done separately for each tax year within your disclosure period, since the letting pattern often differs from year to year. Our guide on how many years you need to declare explains how the overall look-back period is determined, and each of those years will typically need its own careful income and expense calculation if the letting pattern wasn’t consistent throughout.

How Felix Accountants Can Help

Part-year and void-period calculations are one of the more common sources of error in self-prepared Let Property Campaign disclosures. We help landlords work through each relevant tax year methodically, correctly apportioning income and expenses, and documenting the approach so the disclosure holds up to scrutiny. See our guide to landlord accounting for the broader calculation framework this sits within.

Frequently Asked Questions

Do I need to claim expenses for the whole tax year if my property was empty for part of it?

Generally yes, for ongoing costs like mortgage interest and insurance, provided the property remained genuinely part of your rental business — for example, being actively marketed during a void period rather than taken off the market entirely.

How do I calculate rent for a property let for only part of a tax year?

Only the rent actually received or due during the genuine letting period counts as income for that tax year — it shouldn’t be averaged or apportioned evenly across the full year unless that happens to reflect the actual amounts received.

What if I can’t remember exactly when a tenancy started or ended?

A reasonable, documented estimate is acceptable where exact dates can’t be confirmed, based on the best available evidence such as bank statements or correspondence with a letting agent.

Does a void period break my entitlement to claim mortgage interest relief?

Not usually, as long as the property remained genuinely available and marketed for letting during that period, rather than being used personally or withdrawn from the rental market.

Do I need to do this calculation separately for every tax year in my disclosure?

Yes, since the letting pattern often varies year to year. Each tax year within your look-back period generally needs its own income and expense calculation reflecting what actually happened that year.

Let’s get your part-year figures calculated correctly. Book your free 15-minute consultation with Felix Accountants.


Categories
Articles Articles Blogs Let Property Campaign News

Let Property Campaign and Furnished Holiday Let Income: What Landlords Should Check

Owners of holiday cottages, coastal Airbnbs and other short-term let properties have historically benefited from more generous tax treatment than standard buy-to-let landlords. That changed significantly from April 2025, when the Furnished Holiday Lettings (FHL) tax regime was abolished. If you have undeclared income from a furnished holiday let, this shift makes it more important than ever to understand exactly which rules apply to which years — because the position before and after April 2025 is genuinely different, and a Let Property Campaign disclosure needs to reflect that.

Undeclared income from a holiday let or short-term rental? Book a free 15-minute consultation with Felix Accountants and we’ll help you work through the detail. Book your free call here.

What Was the Furnished Holiday Lettings Regime?

Until 5 April 2025, properties that qualified as Furnished Holiday Lets benefited from a range of tax advantages not available to standard residential lettings, including full relief for mortgage interest and other finance costs (rather than the restricted basic-rate credit that applies to standard buy-to-lets), the ability to claim capital allowances on furniture and equipment, treatment of profits as relevant earnings for pension contribution purposes, and access to certain Capital Gains Tax reliefs, including Business Asset Disposal Relief, on eventual sale.

What Changed From April 2025?

From 6 April 2025 for Income Tax and Capital Gains Tax (1 April 2025 for Corporation Tax), the FHL regime was abolished, and qualifying properties are now taxed in essentially the same way as any other residential letting. This means finance costs are now restricted to the basic-rate tax credit, new capital allowances claims have generally stopped (with “replacement of domestic items relief” available instead in many cases), and the favourable Capital Gains Tax treatment on disposal has been withdrawn other than in limited transitional circumstances.

Why This Matters for a Let Property Campaign Disclosure

If you’re disclosing undeclared income from a property that qualified as a furnished holiday let, the calculation needs to be split at the April 2025 boundary:

  • For years up to and including 2024/25: if the property genuinely met the FHL qualifying conditions, the more generous FHL rules (full finance cost relief, capital allowances, etc.) would have applied
  • For 2025/26 onwards: the property is taxed under the standard residential letting rules, meaning restricted mortgage interest relief and the other changes described above

Getting this split right matters because applying the wrong rules to the wrong years can significantly under- or over-state what’s owed. This is a more technical calculation than a standard buy-to-let disclosure, and it’s an area where professional advice is genuinely valuable.

Did Your Property Actually Qualify as an FHL?

Before assuming the FHL rules applied for earlier years, it’s worth checking whether the property genuinely met the qualifying conditions during those periods, which broadly required the property to be available for letting on a commercial basis for a set number of days per year, actually let for a minimum number of days, and not normally occupied by the same tenant for long continuous periods. A property let short-term through platforms like Airbnb doesn’t automatically qualify as an FHL simply because of how it was marketed — the specific letting pattern needs to be checked year by year.

Joint Ownership Changes Are Worth Checking Too

Another change worth being aware of: under the old FHL rules, jointly owned couples could flexibly allocate profits between themselves, reflecting who actually did the work, rather than following the strict ownership split. From April 2025, furnished holiday lets are subject to the same default rules as standard jointly owned property, generally a 50:50 split unless a valid election has been made. If your disclosure involves a jointly owned former FHL, this is worth reviewing carefully for the years either side of the change.

What About VAT for Short-Term Lets?

Separately from Income Tax, holiday accommodation is generally treated as a standard-rated supply for VAT purposes, unlike most long-term residential letting, which is typically exempt. If your short-term let income (combined with any other taxable turnover) exceeds the VAT registration threshold, VAT registration and reporting obligations may also need reviewing alongside the Income Tax disclosure. Our property tax guide covers how different letting types are treated for tax purposes more broadly.

Working Out How Many Years to Disclose

The look-back period for a Let Property Campaign disclosure is generally determined by the reason for non-disclosure rather than the type of letting involved, so the same principles apply to holiday lets as standard buy-to-lets. Our guide on how many years you need to declare sets out the general framework, though the added complexity of the FHL-to-standard-letting transition means the year-by-year calculation itself takes more care to get right.

What You’ll Need to Gather

  • Booking records or platform statements showing income received each year
  • Evidence of letting pattern (nights let, availability) to confirm FHL qualification for pre-2025/26 years
  • Mortgage interest statements and records of capital expenditure on furniture and equipment
  • Details of the ownership structure, particularly for jointly owned properties

How Felix Accountants Can Help

Disclosing undeclared income from a former furnished holiday let is genuinely more involved than a standard residential letting disclosure, given the rule change partway through the relevant period. We help holiday let owners establish which years qualified under the old FHL rules, apply the correct treatment either side of April 2025, and manage the disclosure process through our Let Property Campaign guide and wider disclosure services.

Frequently Asked Questions

Does the Furnished Holiday Lettings regime still exist?

No. It was abolished from 6 April 2025 for Income Tax and Capital Gains Tax purposes (1 April 2025 for Corporation Tax). Holiday let properties are now generally taxed in the same way as standard residential lettings.

Do I still get full mortgage interest relief on my holiday let?

Only for years up to and including 2024/25, if the property genuinely qualified as an FHL during those years. From 2025/26 onwards, mortgage interest relief is restricted to a basic-rate tax credit, the same as standard buy-to-let properties.

How do I know if my property actually qualified as an FHL in earlier years?

Qualification depended on meeting specific letting-pattern conditions each year, including availability and actual letting days. It’s worth reviewing this year by year rather than assuming qualification based on how the property was marketed.

Is holiday let income treated differently for VAT?

Yes. Holiday accommodation is generally standard-rated for VAT, unlike most long-term residential letting, which is usually exempt. This may create a separate VAT registration obligation if turnover exceeds the threshold.

Can I still use the Let Property Campaign for undeclared holiday let income?

Yes, the Let Property Campaign covers undeclared residential letting income generally, including furnished holiday lets, though the calculation needs to correctly reflect the rules that applied in each specific tax year.

Get your holiday let’s tax position properly reviewed. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Articles Blogs Let Property Campaign

Undeclared Rental Income From a Former Home: How Can Landlords Correct Their Tax Position?

It’s one of the most common ways people become landlords without ever really deciding to: you move in with a partner, relocate for work, or upsize to a bigger house, and rather than sell your old property, you rent it out. It feels like a sensible, low-key decision at the time — and often nobody mentions that the rent needs to be declared to HMRC. Years can pass before it becomes clear that this “temporary” arrangement has created a genuine, and growing, tax liability. The good news is that this is a well-recognised situation, and there’s a clear, structured way to correct it.

Rented out your old home without realising you needed to declare it? Book a free 15-minute consultation with Felix Accountants and we’ll help you get back on the right side of HMRC. Find a time here.

Why This Situation Is So Common

Most people who fall into this position never set out to become a landlord. Common scenarios we see regularly include:

  • Moving in with a partner and letting out a previous flat or house rather than selling it
  • Relocating for work and renting the family home while abroad or in another part of the UK
  • Inheriting a property, moving in briefly, and then letting it out once circumstances changed
  • Buying a new main residence and keeping the old one as a rental “for now”

In every one of these cases, the person’s mental model is often “this is still basically my house,” which makes it easy to overlook that HMRC treats rental income exactly the same way regardless of how the letting arrangement came about. Our guide on being an accidental landlord covers this pattern in more depth, including the specific triggers that most often catch people out.

Why the Rent-Only-Covers-the-Mortgage Myth Is So Costly

A particularly common misconception is believing that if the rent received roughly matches the mortgage payment, there’s no taxable profit and therefore nothing to declare. This isn’t correct, for two reasons. First, only the interest element of a mortgage payment is an allowable expense — the capital repayment portion isn’t deductible at all. Second, since 2020, tax relief for mortgage interest on residential lettings held personally has been restricted to a basic-rate tax credit rather than a full deduction against income. This means many landlords who genuinely believed they were breaking even are, in fact, sitting on a taxable rental profit they’ve never reported.

Correcting the Position Through the Let Property Campaign

The Let Property Campaign is HMRC’s dedicated voluntary disclosure route for exactly this situation. It allows individual landlords to come forward, calculate what’s owed across the relevant tax years, and pay it — typically with significantly lower penalties than if HMRC discovers the income independently and opens an enquiry. The process generally involves three stages: notifying HMRC of your intention to disclose, calculating the tax owed for each relevant year (including interest), and submitting a formal disclosure, usually within 90 days of notifying.

Working Out How Many Years to Go Back

The number of years you need to include depends on why the income wasn’t declared, not simply how long you’ve been letting the property. For most people in this situation — where the omission genuinely stemmed from not realising the obligation existed, rather than any attempt to conceal income — the look-back period is typically four to six years. Our detailed guide on how many years you need to declare explains how this is determined and why getting it right matters, since under-disclosing can itself create problems later.

What About the Original Main Residence Relief?

Because the property was once your main home, it’s worth understanding how that history interacts with your tax position going forward, particularly around Capital Gains Tax if you eventually sell. Private Residence Relief can reduce or eliminate Capital Gains Tax for the period the property was genuinely your main residence, plus a final period of ownership, even though it’s since been let out. Our guide on maximising main residence relief explains how this relief interacts with a period of letting, which is a separate but closely related consideration alongside sorting out the undeclared rental income itself.

What If HMRC Has Already Written to You?

If you’ve received a nudge letter from HMRC about rental income, the position changes slightly. A disclosure made after HMRC has already contacted you is classed as “prompted” rather than “unprompted,” which generally attracts a higher penalty percentage than coming forward first. Our comparison of prompted versus unprompted disclosures sets out exactly how the two are treated differently, and it’s still almost always better to respond promptly and constructively than to ignore the letter or delay further.

What You’ll Need to Pull Together

  • The date you moved out and started letting the property
  • Rent received each year, from bank statements or a letting agent’s annual statement
  • Mortgage interest statements for the letting period
  • Records of repairs, insurance, letting agent fees, and any other allowable running costs
  • Details of any period the property was genuinely your main residence, for the Capital Gains Tax position if it’s later sold

If some of this is missing, that’s a common and manageable problem — a reasonable, well-documented estimate is generally acceptable where original records genuinely can’t be recovered.

Why Acting Now Is Better Than Waiting

HMRC’s ability to identify undeclared rental income has grown substantially through data from letting agents, deposit protection schemes, the Land Registry, and information-sharing arrangements with online letting platforms. The longer an undeclared rental arrangement continues, the larger the eventual liability becomes, and the greater the risk that HMRC identifies it independently before you’ve had the chance to disclose voluntarily and secure the lower penalty treatment available for unprompted disclosures.

How Felix Accountants Can Help

We regularly help people in exactly this position — landlords who never intended to be landlords, and who simply want to get their tax affairs straight without unnecessary stress. We’ll help you work out the correct number of years to disclose, calculate what’s owed, and manage the process with HMRC on your behalf through our undisclosed rental income reporting service.

Frequently Asked Questions

Do I need to declare rental income if it just covers my mortgage payment?

Yes. Only the interest portion of a mortgage payment is an allowable cost, and mortgage interest relief for individual landlords is now given as a basic-rate tax credit rather than a full deduction, so many landlords in this position do have a taxable profit even if it doesn’t feel that way.

How many years of rental income will I need to declare for my old home?

This depends on the reason for non-disclosure. Where the omission stemmed from a genuine misunderstanding rather than deliberate concealment, the look-back period is typically four to six years.

Will I lose the tax relief for the years the property was my main home?

No. Private Residence Relief still applies to the period the property was genuinely your main residence, plus a final period of ownership, and this is separate from correcting the undeclared rental income for the letting period.

What if I’ve already had a letter from HMRC about this property?

You can still disclose, but it will generally be treated as a prompted disclosure, which typically carries a higher penalty than an unprompted one. It’s still better to respond and disclose than to ignore the letter.

Is it worth using an accountant for this, or can I do it myself?

You can make a disclosure yourself, but the calculations involving mortgage interest restrictions, allowable expenses and the correct look-back period are easy to get wrong. An accountant experienced with the Let Property Campaign can help ensure the disclosure is accurate and complete the first time.

Ready to put your old home’s rental income right? Book your free 15-minute consultation with Felix Accountants today.


Categories
Articles Articles Blogs Let Property Campaign

VAT Flat Rate vs Standard VAT Scheme: Which Could Suit a Small Business?

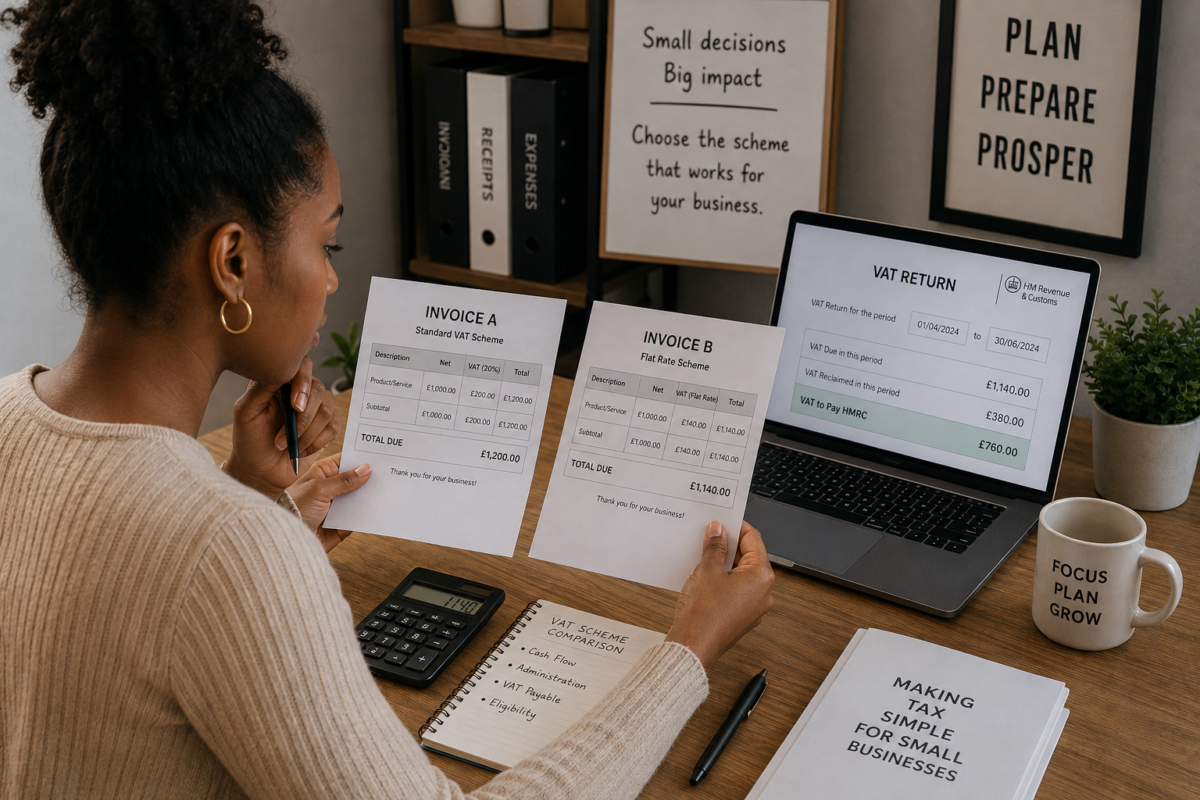
Once your business is VAT-registered, one of the first practical decisions you’ll face is which VAT scheme to use. The two most common options for small businesses are the standard VAT scheme and the VAT Flat Rate Scheme, and the right choice can genuinely affect both your admin burden and your bottom line. This guide compares how each works, who tends to benefit, and the one rule that catches out a lot of service-based businesses on the Flat Rate Scheme.

Not sure which VAT scheme actually saves you money? Book a free 15-minute consultation with Felix Accountants and we’ll run the numbers for your business. Book your free call here.

How Standard VAT Accounting Works

Under standard VAT accounting, you charge VAT on your sales (output VAT) and reclaim VAT on your business purchases (input VAT). Each quarter, you pay HMRC the difference between the two — output VAT minus input VAT. This means every invoice and receipt genuinely matters, since your VAT bill depends directly on tracking both sides accurately. For businesses with significant purchase costs, such as those buying stock, equipment or materials, this is usually the more financially favourable option, because you’re able to reclaim the VAT you’ve paid out.

How the VAT Flat Rate Scheme Works

The VAT Flat Rate Scheme (FRS) simplifies the calculation considerably. You still charge customers VAT at the standard rate — usually 20% — but instead of separately tracking input VAT on purchases, you pay HMRC a single fixed percentage of your VAT-inclusive turnover. The percentage is set by HMRC according to your business sector and is always below 20%, so the gap between what you charge and what you hand over effectively stays in the business.

For example, if your sector’s flat rate is 12% and you invoice a client £10,000 plus £2,000 VAT (a total of £12,000), you’d pay HMRC 12% of £12,000, which is £1,440, keeping the remaining £560 rather than reclaiming input VAT separately.

To join the scheme, your VAT-taxable turnover generally needs to be £150,000 or less (excluding VAT) in the next 12 months, and you must leave once your total VAT-inclusive turnover exceeds £230,000 on the anniversary of joining, or if you expect it to exceed that figure within the next 12 months.

The First-Year Discount

If you’re in your first year of VAT registration, HMRC applies a 1% discount to your flat rate percentage. So a business with a standard sector rate of 12% would pay just 11% during that first year, from the date of VAT registration until the first anniversary of joining the scheme.

The Limited Cost Trader Rule: Why the Flat Rate Scheme Can Backfire

This is the single most important rule to understand before choosing the Flat Rate Scheme. If your business spends very little on goods — broadly, less than 2% of your VAT-inclusive turnover, or under £250 per quarter — you’re classed as a “limited cost trader” and must apply a flat rate of 16.5%, regardless of your actual sector. Because 16.5% of VAT-inclusive turnover is very close to the full 20% VAT you’re charging, the scheme can end up leaving you with barely any benefit, or in some cases costing more than standard VAT accounting would have.

This catches out a lot of consultants, contractors, agencies and other service businesses with genuinely low goods spend — think office supplies and a laptop, rather than stock or materials. If that describes your business, it’s worth running the comparison carefully before committing to the Flat Rate Scheme.

What You Can Still Reclaim Under the Flat Rate Scheme

There’s one notable exception to the “no input VAT reclaim” rule on the Flat Rate Scheme: capital assets costing £2,000 or more (including VAT) can still have their input VAT reclaimed separately, even while you’re on the scheme. This matters if you’re planning a larger one-off purchase, such as equipment or machinery, as it can meaningfully change the maths.

Comparing the Two: A Practical Framework

FactorStandard VAT SchemeVAT Flat Rate Scheme
Admin burdenHigher — every purchase and sale trackedLower — one percentage applied to turnover
Reclaiming VAT on purchasesYes, in full (subject to normal rules)No, except capital assets over £2,000
Best suited toBusinesses with significant purchase/stock costsLow-cost service businesses not caught by the 16.5% rule
Risk factorMore record-keeping errors possibleLimited cost trader rule can erode the benefit

Which Businesses Tend to Benefit From the Flat Rate Scheme?

  • Service businesses with a sector flat rate meaningfully below 20% that aren’t caught by the limited cost trader rule
  • Businesses that want simpler quarterly VAT returns and are willing to accept a slightly less precise calculation in exchange for reduced admin
  • New businesses in their first year of VAT registration benefiting from the 1% discount

Which Businesses Tend to Benefit From Standard VAT Accounting?

  • Businesses with regular, significant purchases where reclaiming input VAT makes a real financial difference
  • Businesses whose main activity would place them in, or close to, the 16.5% limited cost trader category under the Flat Rate Scheme
  • Businesses that want the VAT return to reflect the actual, precise VAT position rather than a fixed-percentage approximation

Don’t Forget Making Tax Digital

Regardless of which VAT scheme you choose, VAT-registered businesses are required to keep digital records and file VAT returns through Making Tax Digital-compatible software. This has applied to all VAT-registered businesses for some time now, so the choice between schemes doesn’t affect whether MTD applies — only how the underlying VAT calculation is worked out.

How This Applies to Property and Landlord Businesses

Most residential letting income is exempt from VAT, so many individual landlords never need to register at all. However, property developers, those providing furnished holiday lettings on a commercial scale, or businesses with a mix of taxable and exempt property income can face more complex VAT decisions. Our guide on VAT and property in the UK and our article on VAT implications for property developers and investors cover this in more detail if your situation involves property alongside a wider small business.

How Felix Accountants Can Help

Choosing between the Flat Rate Scheme and standard VAT accounting isn’t a one-size-fits-all decision — it depends on your actual sector rate, your typical spending on goods, and your growth plans. We run the comparison for clients using real business figures rather than rules of thumb, and handle the registration, scheme selection and ongoing VAT return filing. See our wider taxation services for how we support small businesses beyond VAT.

Frequently Asked Questions

Can I switch between the Flat Rate Scheme and standard VAT accounting?

Yes, you can leave the Flat Rate Scheme at any time, though once you leave you generally can’t rejoin for at least 12 months. Moving to the Flat Rate Scheme from standard VAT is also possible if you meet the eligibility criteria.

What is a limited cost trader?

A limited cost trader is a business that spends less than 2% of its VAT-inclusive turnover on goods (not services) in a VAT period, or less than £250 per quarter. Limited cost traders must apply a 16.5% flat rate, regardless of their actual business sector.

Do I still charge customers 20% VAT on the Flat Rate Scheme?

Yes. The flat rate percentage only affects how much VAT you hand over to HMRC, not the rate you charge customers, which remains the normal rate applicable to your goods or services.

Is the Flat Rate Scheme always simpler, even if it isn’t cheaper?

Generally yes, since you don’t need to analyse every purchase invoice for VAT. However, “simpler” doesn’t always mean “cheaper,” so it’s worth weighing the admin saving against the potential extra VAT cost, particularly under the 16.5% limited cost trader rate.

Does my VAT scheme choice affect Making Tax Digital requirements?

No. Making Tax Digital applies to all VAT-registered businesses regardless of which VAT scheme they use — it governs how records are kept and returns are filed, not which scheme calculates the VAT owed.

Let’s work out which VAT scheme actually suits your business. Book your free 15-minute consultation with Felix Accountants today.


Categories
Articles Blogs Let Property Campaign

Corporation Tax Accounting Periods Explained for UK Companies

Every UK limited company has a Corporation Tax accounting period, and understanding exactly what it is — and how it differs from your company’s financial year — is essential to avoiding late filing penalties and interest charges. It’s a surprisingly common source of confusion, particularly for new directors, because the accounting period isn’t always the same length as the company’s financial year shown at Companies House. This guide sets out clearly what a Corporation Tax accounting period is, how it’s set, and what deadlines follow from it.

Not sure when your Corporation Tax is actually due? Book a free 15-minute consultation with Felix Accountants and we’ll confirm your exact deadlines. Book your free call here.

What Is a Corporation Tax Accounting Period?

A Corporation Tax accounting period is the period HMRC uses to calculate how much Corporation Tax your company owes. It’s usually 12 months long and generally matches your company’s financial year, which runs to your accounting reference date set at Companies House. However, the two aren’t automatically identical — HMRC’s rules cap a single Corporation Tax accounting period at 12 months, so if your company’s financial year is longer than 12 months (which can happen in a company’s first year of trading), HMRC splits it into two separate accounting periods for tax purposes.

Financial Year vs Accounting Period: What’s the Difference?

These two terms are often used interchangeably, but they serve different purposes:

  • Financial year (accounting reference period): the period covered by your statutory accounts, filed at Companies House. This can be up to 18 months for a company’s first set of accounts.
  • Corporation Tax accounting period: the period HMRC uses to assess Corporation Tax. This is capped at 12 months, so a longer financial year is split accordingly.

For example, a company incorporated on 1 July 2025 with an accounting reference date of 31 March 2026 would have a first financial year of nine months (1 July 2025 to 31 March 2026), which in this case fits within the 12-month cap, so financial year and accounting period would match. But a company with a longer first period — say, 15 months from incorporation to its first accounting reference date — would need to split that into a 12-month Corporation Tax accounting period followed by a shorter second period covering the remaining months, each requiring its own calculation and, where applicable, its own CT600 return.

How Your First Accounting Period Is Set

Your first Corporation Tax accounting period begins on the date your company starts trading, not necessarily the date it was incorporated. Many companies are incorporated some time before they actually begin trading — for example, a property investment company might be set up months before it acquires its first property. Corporation Tax obligations, including the requirement to register with HMRC, generally begin once trading activity actually starts, so it’s important to notify HMRC within three months of trading commencing.

If you’re setting up a company to hold or invest in property, our guide on property investment through a limited company covers some of the wider considerations around structuring, alongside the accounting period rules covered here.

The Three Key Deadlines That Follow From Your Accounting Period

Once your accounting period is established, three separate deadlines follow from its end date:

  • Corporation Tax payment: due 9 months and 1 day after the end of the accounting period
  • Company Tax Return (CT600): due 12 months after the end of the accounting period
  • Companies House annual accounts: due 9 months after the end of the financial year for most private companies (21 months from incorporation for a first set of accounts)

Note that the tax payment deadline actually falls before the CT600 filing deadline — a common point of confusion. For example, for an accounting period ending 31 March 2026, Corporation Tax would be due by 1 January 2027, while the CT600 return wouldn’t be due until 31 March 2027. Directors sometimes assume that because the return isn’t due yet, the payment isn’t either, which can lead to interest charges on genuinely late tax.

Why Splitting an Accounting Period Matters in Practice

When a financial year longer than 12 months is split into two Corporation Tax accounting periods, each period requires its own profit calculation, its own set of allowances and reliefs applied proportionately, and potentially its own CT600 submission. This most commonly affects newly incorporated companies with an unusually long first trading period, and it’s an area where getting the split wrong can lead to an incorrect tax calculation or a missed filing obligation for the second, shorter period. This is particularly relevant for companies formed to hold buy-to-let or investment property, where the gap between incorporation and the first accounting reference date can sometimes exceed 12 months.

Can You Change Your Accounting Period?

Yes, a company can shorten or extend its accounting reference date at Companies House, which in turn affects the Corporation Tax accounting periods that follow. This might be done to align the company’s year-end with a parent company, a calendar year, or simply for administrative convenience. Any change should be considered carefully, since it can affect both the Companies House filing deadline and how HMRC treats the corresponding tax periods, and once shortened, some restrictions apply to changing it again too frequently.

What Happens if You Miss an Accounting Period Deadline?

Missing the Companies House accounts deadline triggers an automatic penalty, starting from £150 for filings up to one month late and rising with the length of the delay, doubling if you were also late the previous year. Separately, missing the CT600 filing deadline triggers its own fixed penalties from HMRC, and missing the tax payment deadline results in daily interest accruing on the outstanding amount. Because these are three distinct obligations with three distinct deadlines, it’s entirely possible to file your accounts on time but still incur penalties for a late Corporation Tax payment, or vice versa.

Dormant Companies Aren’t Exempt

Even if your company hasn’t started trading, it still has an accounting reference period for Companies House purposes and must file dormant accounts on the same schedule as a trading company. Once trading does begin, the Corporation Tax accounting period clock starts, and HMRC registration becomes necessary within three months.

How Felix Accountants Can Help

We help directors of trading companies and property investment companies alike get their accounting periods, deadlines and filings right from day one, whether that’s registering a newly trading company with HMRC, managing a split accounting period in year one, or simply confirming when your next Corporation Tax payment is actually due. See our wider business tax services for how we support companies through the full filing cycle.

Frequently Asked Questions

Is my Corporation Tax accounting period the same as my financial year?

Usually, yes, but not always. A Corporation Tax accounting period can never exceed 12 months, so if your company’s financial year is longer than 12 months, it will be split into two separate accounting periods for Corporation Tax purposes.

When does my first accounting period start?

Your first Corporation Tax accounting period begins when your company starts trading, which is not necessarily the same as its incorporation date.

What’s the deadline to pay Corporation Tax?

Corporation Tax is generally due 9 months and 1 day after the end of your accounting period, which is earlier than the deadline to file your CT600 return.

Do I need to file a CT600 if my company hasn’t traded yet?

If your company is genuinely dormant, you’ll still need to file dormant accounts at Companies House, but a CT600 is only required once the company has started trading and been registered with HMRC for Corporation Tax.

Can I change my company’s accounting reference date?

Yes, you can shorten or extend your accounting reference date via Companies House, though this affects your future Corporation Tax accounting periods and filing deadlines, so it’s worth getting advice before making the change.

Get clarity on your company’s exact filing deadlines. Book your free 15-minute consultation with Felix Accountants.


Categories
Articles Blogs Let Property Campaign News

Let Property Campaign Disclosure: How Should Landlords Deal With Missing Rental Records?

One of the most common reasons landlords put off making a Let Property Campaign disclosure isn’t reluctance — it’s fear that they simply don’t have the paperwork to back it up. Old tenancy agreements have been lost, bank accounts have been closed, and receipts for repairs from six years ago were never kept. The reassuring truth is that missing records don’t stop you from making a valid disclosure; HMRC expects landlords in this position and accepts carefully reasoned estimates, provided they’re built on a sensible method rather than guesswork.

Missing paperwork doesn’t have to hold up your disclosure. Book a free 15-minute consultation with Felix Accountants and we’ll help you map out exactly what you can reconstruct. Grab a free slot here.

Why Missing Records Are So Common Among Landlords Disclosing Under the LPC

Most landlords who end up using the Let Property Campaign weren’t running a professional letting business from day one. Many became landlords by accident — inheriting a property, relocating for work, or renting out a former family home — and never set up formal bookkeeping. Years later, when it’s time to disclose, bank statements have often been archived beyond easy online access, letting agents have changed hands, and receipts were simply thrown away. This is normal, and it’s exactly the scenario HMRC’s disclosure process is built to accommodate.

Start With What You Can Actually Access

Before assuming records are gone for good, it’s worth checking a few sources that are often more complete than landlords expect:

  • Online banking archives: most UK banks retain digital statements for 6–7 years and can often provide older statements on request, sometimes for a small fee
  • Letting agent portals or year-end statements: agents typically issue annual income summaries, which are far easier to request than reconstructing every transaction
  • Mortgage statements: useful for establishing the interest paid, which is a major allowable cost
  • Insurance renewal documents: confirm landlord insurance costs and the dates the property was actually let
  • Land Registry and conveyancing paperwork: confirms purchase date, sale date (if applicable), and ownership history

Our guide to record keeping sets out the categories of documents HMRC typically expects landlords to retain, and is a useful checklist even when working backwards from an incomplete starting point.

When Records Genuinely Don’t Exist: Building a Reasonable Estimate

Where source documents can’t be recovered, HMRC allows landlords to use reasonable estimates, as long as the method is transparent and defensible. A sound approach usually involves:

  • Establishing the letting period from tenancy start/end dates, Land Registry records, or correspondence with a former letting agent
  • Using average local market rents for a comparable property over the relevant years as a cross-check against any partial records you do have
  • Applying a consistent, conservative approach to expenses — only claiming costs you can reasonably evidence or that are typical and proportionate for the property type
  • Documenting the assumptions behind every estimate in writing, so the methodology can be explained if HMRC asks questions later

This is where working with an accountant experienced in Let Property Campaign disclosures makes a real difference. We’ve supported landlords who arrived with almost nothing beyond a mortgage statement and a rough idea of when tenants moved in, and helped them build a disclosure that HMRC accepted without further challenge.

Missing Records Don’t Change Your Look-Back Period

It’s worth being clear that having incomplete records doesn’t reduce how many years you need to disclose. The look-back period is determined by the reason the income wasn’t declared — careless error, failure to take reasonable care, or deliberate non-disclosure — not by how much paperwork survives. Our article on how many years you need to declare explains this in more detail, and it’s a good starting point before you begin reconstructing figures, so you know exactly which tax years to focus on.

The 90-Day Window and Why Preparation Matters

Once you notify HMRC of your intention to disclose under the Let Property Campaign, you generally have 90 days to submit the full disclosure and calculate what’s owed. Trying to reconstruct several years of missing records within that window, under time pressure, is far harder than starting the reconstruction work before you notify HMRC. Our 90-day deadline prep guide walks through how to use that period efficiently if you’ve already notified, but the ideal approach is to begin gathering what you can before you formally start the clock.

What Counts as a Reasonable Excuse — and What Doesn’t

Missing records themselves aren’t usually accepted as a reason not to disclose at all, but the circumstances behind why records went missing can matter for how HMRC views your overall behaviour. Genuinely losing paperwork in a house move, a bereavement, or simply never having set up formal bookkeeping as an accidental landlord is treated very differently from deliberately destroying evidence. Being upfront about why records are incomplete, rather than presenting rough figures as if they were exact, tends to support a smoother disclosure.

Common Mistakes to Avoid When Records Are Incomplete

  • Rounding figures without any supporting logic, rather than using a documented estimation method
  • Ignoring years where you’re unsure of the exact rent, hoping HMRC won’t notice — this significantly increases risk if discovered later
  • Claiming expenses you can’t reasonably evidence or that seem disproportionate to the size of the letting
  • Waiting indefinitely to “find better records” instead of starting the disclosure with a reasonable, well-documented estimate

See our broader guide on the top bookkeeping mistakes landlords make for related pitfalls worth avoiding going forward.

How Felix Accountants Helps When Your Records Are Incomplete

We regularly work with landlords who come to us with partial, patchy, or almost non-existent records for the years in question. Our process involves piecing together what’s available, applying recognised estimation techniques where genuine gaps exist, and preparing a disclosure that stands up to scrutiny. You can read more in our LPC disclosure guide or get in touch directly to talk through your specific situation.

Frequently Asked Questions

Can I make a Let Property Campaign disclosure without any bank statements?

Yes, in principle. If bank statements aren’t available, other evidence such as letting agent statements, tenancy agreements, or a reasonable, documented estimate based on comparable market rents can be used instead.

Will HMRC reject my disclosure if some figures are estimates?

Not usually, provided the estimates are reasonable, consistently applied, and clearly explained as estimates rather than presented as exact figures without qualification.

Should I wait until I’ve found all my missing records before notifying HMRC?

Generally no. It’s better to begin the record-reconstruction process first, then notify HMRC once you have a workable picture, since the 90-day disclosure window starts as soon as you notify.

Does having incomplete records mean I’ll face higher penalties?

Not on its own. Penalties are primarily driven by whether the disclosure is prompted or unprompted and the underlying behaviour (careless versus deliberate), not simply by the state of your paperwork.

Can an accountant help reconstruct years of missing rental records?

Yes, this is one of the most valuable parts of working with an experienced property accountant during a Let Property Campaign disclosure, as we can apply consistent, defensible methods across multiple tax years.

Don’t let missing paperwork stop you from disclosing. Book your free 15-minute consultation with Felix Accountants and we’ll help you build a disclosure that works with what you actually have.


Categories
Articles Articles Corporation Tax

Accounting Profit vs Taxable Profit: Corporation Tax Explained

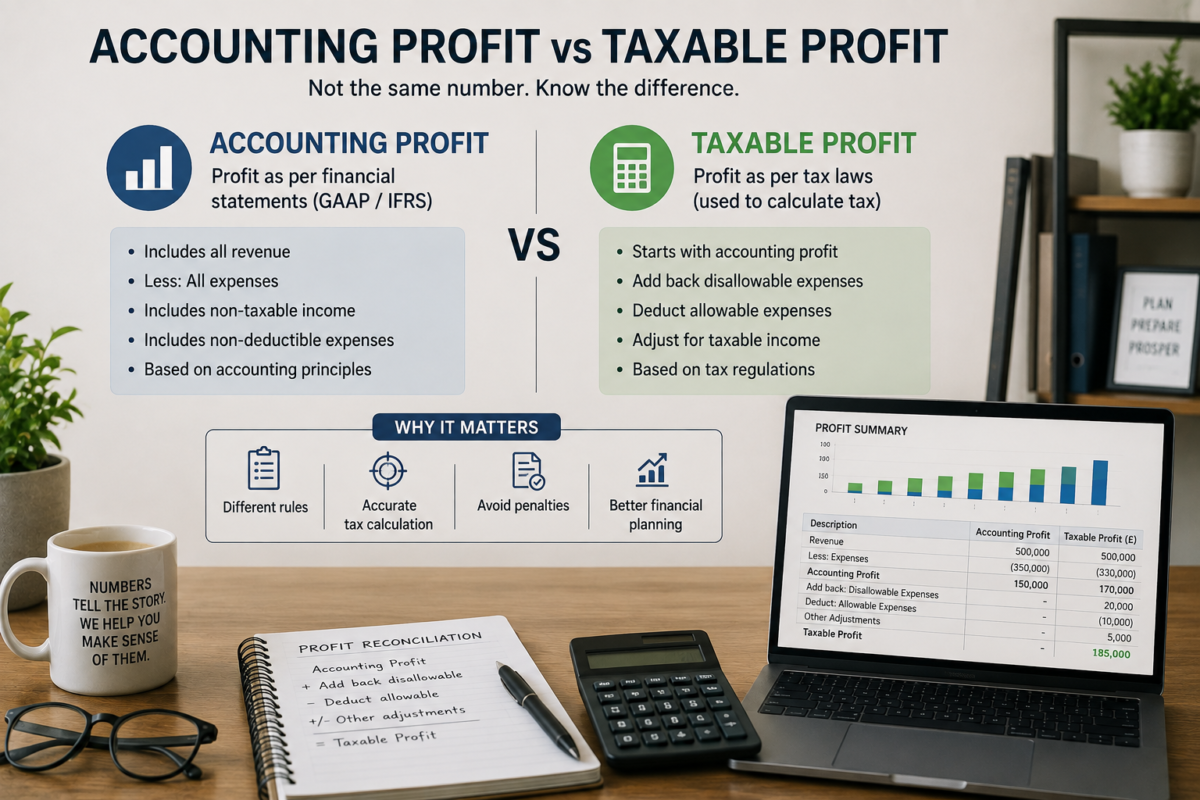
If you’ve ever looked at your company’s profit and loss account and then been surprised by the Corporation Tax bill that follows, you’re not alone. The profit in your accounts and the profit HMRC actually taxes are rarely the same figure, and understanding why is one of the most useful things a director can learn about how Corporation Tax actually works.

Want a second opinion on your Corporation Tax computation before you file? Book a free 15-minute consultation with Felix Accountants and we’ll take a look.

What Is Accounting Profit?

Accounting profit is the figure shown in your statutory accounts, prepared under standard accounting frameworks such as FRS 102 or FRS 105. It reflects your income less all costs recognised during the accounting period, including things like depreciation, which spreads the cost of an asset over its useful life for accounting purposes.

What Is Taxable Profit?

Taxable profit — more precisely, “taxable total profits” for Corporation Tax purposes — starts with your accounting profit and adjusts it according to tax law. Some costs that are perfectly valid in your accounts simply aren’t deductible for tax, and some tax reliefs don’t appear in your accounts at all. The result, after these adjustments, is the figure your Corporation Tax is actually calculated on.

Why Depreciation Gets Added Back

Depreciation is an accounting estimate of how an asset loses value over time, and estimates aren’t something tax law is willing to rely on directly. Instead, depreciation is added back in full in the tax computation, and capital allowances — a set of HMRC-defined rates and allowances — are used instead to give tax relief on qualifying capital expenditure. The Annual Investment Allowance, for example, currently allows many businesses to deduct the full cost of qualifying plant and machinery in the year of purchase, up to a set limit, with writing down allowances covering amounts above that.

Common Disallowable Expenses

Beyond depreciation, several other costs that appear in your accounts must be added back because they aren’t allowable for Corporation Tax:

  • Client entertainment costs
  • Fines and penalties, including parking tickets and HMRC penalties
  • Costs that don’t meet the “wholly and exclusively” test for business purposes
  • Certain provisions that haven’t yet crystallised into an actual liability

For a fuller list of what is and isn’t deductible for a limited company, see our guide to allowable limited company expenses.

A Worked Example

ItemAmount
Profit per accounts£60,000
Add back: depreciation+£8,000
Add back: client entertaining+£1,200
Less: capital allowances-£6,500
Taxable total profits£62,700

Notice that the taxable figure here is higher than the accounting profit, even though the company hasn’t earned any additional cash — it’s purely the effect of the add-backs and reliefs working differently in the two calculations. In other cases, generous capital allowances can push taxable profit below accounting profit instead.

Why This Distinction Matters for Directors

Understanding the gap between accounting and taxable profit matters for more than just curiosity. It affects how much cash you should be setting aside for your Corporation Tax bill, and it’s also a completely separate question from how much profit is legally available to pay out as dividends, which is governed by company law and your accounting profit and reserves, not your tax computation. Paying dividends from profits that don’t actually exist can result in an illegal dividend — our guide on illegal dividends explains this risk in more detail.

Common Misunderstandings

  • Assuming your Corporation Tax bill should match a simple percentage of your accounting profit
  • Forgetting that capital expenditure isn’t deducted as it’s spent, but relieved through capital allowances instead
  • Treating distributable reserves and taxable profit as the same thing when deciding on dividends
  • Missing available reliefs, such as R&D relief, because they don’t automatically appear in the accounting figures

How Felix Accountants Can Help

We prepare Corporation Tax computations that correctly reconcile your accounting profit to your taxable profit, make sure you’re claiming every allowance and relief you’re entitled to, and help you plan cash flow around your actual tax liability rather than guesswork.

Frequently Asked Questions

Why is my Corporation Tax bill higher than expected based on my accounts?

This usually happens because disallowable expenses, like depreciation or client entertaining, have been added back in the tax computation, increasing your taxable profit above your accounting profit.

Do capital allowances always reduce my tax bill more than depreciation would?

Not necessarily in every year, but capital allowances are the only mechanism HMRC recognises for tax relief on capital expenditure, so understanding and claiming them correctly is essential regardless of how they compare to your accounting depreciation charge in any given year.

Can I pay dividends based on my accounting profit even if my taxable profit is lower?

Dividends must be paid from distributable reserves under company law, which relate to your accounting position, not your taxable profit figure. The two calculations serve different purposes and shouldn’t be confused when deciding what can legally be paid out.

Does every company need a formal tax computation separate from its accounts?

Yes. Even small companies need to prepare a Corporation Tax computation that adjusts accounting profit for tax purposes as part of the CT600 filing process, regardless of how straightforward the underlying accounts are.

Categories
Articles Articles Blogs Self Assessment Taxation Services

What Happens If You Discover an Error in a Previous UK Tax Return?

Spotting a mistake on a tax return you’ve already submitted is more common than you might think — a missed expense, an omitted source of income, or a figure that simply doesn’t add up. The important thing is what you do next, because HMRC treats a self-corrected error very differently from one it uncovers itself.

Not sure whether you’re still within the amendment window, or how to approach HMRC about an older error? Book a free 15-minute consultation with Felix Accountants and we’ll help you work out the best next step.

Step One: Work Out Which Deadline Applies

How you correct the error depends on how long ago you filed the return in question.

Within 12 Months of the Filing Deadline

If you’re within 12 months of the normal Self Assessment filing deadline for that return, you can simply amend it yourself. For an online return, log back into your HMRC account, update the relevant figures, and resubmit — the system recalculates your bill automatically, showing whether you owe more or are due a refund. For example, a 2024/25 return filed by the 31 January 2026 deadline can generally be amended up to 31 January 2027.

More Than 12 Months After the Deadline

Once the 12-month window has closed, you can no longer amend the return online. Instead, you’ll need to write to HMRC explaining the correction, or make a formal overpayment relief claim if the error means you paid too much tax. Overpayment relief claims can generally be made up to four years after the end of the tax year the return relates to.

What to Include in a Written Correction or Overpayment Relief Claim

  • The tax year the correction relates to
  • A clear explanation of what was wrong and why
  • The amount you believe was overpaid or underpaid
  • Supporting evidence (invoices, statements, calculations)
  • A signed declaration confirming the details are correct and complete to the best of your knowledge

If the Error Means You Owe More Tax

If correcting the mistake increases your tax bill, it’s best to notify HMRC and pay the difference as soon as you’re aware of it. Interest accrues from the original due date, and coming forward yourself, before HMRC identifies the discrepancy independently, generally puts you in a much stronger position on penalties than waiting to be caught out. This is the same underlying principle behind voluntary disclosure routes like the Let Property Campaign for landlords with undeclared rental income specifically.

If the Error Means You Overpaid

If you’re due a refund, amending within the 12-month window is the most straightforward route — HMRC recalculates your position and processes the repayment. Outside that window, an overpayment relief claim achieves the same result but requires a more formal written submission with supporting evidence.

Genuine Mistakes vs Careless or Deliberate Errors

HMRC distinguishes between an honest, reasonable mistake and one caused by carelessness or deliberate action, and this distinction affects whether a penalty applies at all. If you took reasonable care and made a genuine error in good faith, you’re unlikely to face a penalty for correcting it — HMRC generally responds far more favourably to taxpayers who put things right themselves. If the error was significant, spanned several years, or involved undeclared income you knew about, professional advice is worth getting before you approach HMRC, since the correct classification affects both the penalty and how many years need correcting.

What If HMRC Corrects the Error First?

HMRC can amend a return itself within nine months of the date you filed it, typically to correct obvious errors, and will notify you of any change. If HMRC identifies a more significant discrepancy through a compliance check, the process moves from a simple correction into a formal enquiry, and the potential penalties for the same underlying mistake are usually higher than if you’d corrected it proactively.

A Practical Example

Suppose you filed your 2023/24 return in January 2025 and later realise, in mid-2026, that you forgot to include some rental income. Since more than 12 months have passed since the 31 January 2025 deadline, you can’t amend the return online — you’d need to write to HMRC, or, if the omission relates to rental income specifically, consider whether the Let Property Campaign disclosure process is the more appropriate route, since it’s specifically designed for this kind of correction.

How Felix Accountants Can Help

Whether you’re inside the 12-month amendment window or need to make a formal overpayment relief claim or voluntary disclosure, we’ll help you work out the right process, prepare accurate figures, and manage the correspondence with HMRC on your behalf.

Frequently Asked Questions

How long do I have to amend a Self Assessment tax return?

You generally have 12 months from the normal filing deadline for that tax year. For example, a return with a 31 January 2027 deadline can usually be amended up to 31 January 2028.

What is overpayment relief?

Overpayment relief is a formal claim you can make to recover tax you’ve overpaid, once the standard 12-month amendment window has passed. It must generally be made within four years of the end of the relevant tax year and requires a written submission with supporting evidence.

Will I be penalised for correcting my own mistake?

If the error was a genuine mistake made despite taking reasonable care, a penalty is unlikely. Penalties are more commonly applied where HMRC considers the error careless or deliberate, and coming forward yourself before HMRC identifies the issue generally results in a lower penalty than waiting.

Can HMRC change my tax return without telling me?

HMRC can make certain corrections within nine months of your filing date, but it will notify you of any change made. Anything beyond a simple correction, such as a discrepancy found through a compliance check, involves a more formal process where you’re kept informed and can respond.