Categories
Articles Articles Blogs Let Property Campaign News

What Happens When Rental Income Was Shared With a Spouse or Partner?

When a rental property is jointly owned by a married couple, civil partners, or unmarried co-owners, disclosing undeclared income through the Let Property Campaign raises a question that doesn’t come up for a sole landlord: how should the income actually be split between the owners for tax purposes? The answer depends heavily on your relationship status and how the property is legally owned, and getting it wrong can mean disclosing — and paying tax on — the wrong amounts for each person.

Jointly own a property with undeclared rental income? Book a free 15-minute consultation with Felix Accountants and we’ll help you both get this sorted. Book your free call here.

The Default Rule for Married Couples and Civil Partners

For married couples and civil partners who jointly own a property, HMRC’s default assumption is that rental income is split 50:50 between them for tax purposes, regardless of the actual ownership proportions or who does more of the practical management. This applies automatically unless the couple has taken specific steps to declare a different split.

Declaring an Unequal Split: Form 17

If a couple genuinely owns the property in unequal shares — for example, 70:30 — and wants their tax treatment to reflect that actual ownership split rather than the automatic 50:50 default, they need to make a formal declaration to HMRC using Form 17, along with evidence of the underlying unequal beneficial ownership, such as a declaration of trust. This election isn’t automatic or retrospective in the way some people assume — it only takes effect from the date HMRC receives a valid declaration, and can’t be backdated to earlier tax years where no such election was made.

This matters directly for a Let Property Campaign disclosure: if no Form 17 election was in place during the years being disclosed, HMRC will generally expect the 50:50 split to apply for those years, even if the couple’s actual ownership shares were different and even if they later put a valid election in place going forward.

Unmarried Couples and Other Joint Owners

The 50:50 default is specifically a rule for married couples and civil partners. For unmarried couples, siblings, friends, or other joint owners, rental income is generally taxed according to each person’s actual beneficial ownership share, which may or may not be an equal split, depending on how the property is legally and beneficially owned. This makes it particularly important for unmarried co-owners to establish the correct ownership percentages, ideally supported by a declaration of trust or similar documentation, before calculating each person’s disclosure.

What If Ownership Shares Have Changed Over Time?

It’s not unusual for ownership shares to change during the period covered by a disclosure — perhaps one partner bought out a larger share, or a property was transferred between spouses at some point. Where this has happened, the income split for each tax year needs to reflect the ownership position that actually applied during that specific year, rather than applying today’s ownership split retrospectively across the whole disclosure period.

Does Each Owner Need Their Own Disclosure?

Generally, yes. Each individual is separately responsible for reporting their own share of rental income to HMRC, which means each joint owner typically needs to make their own Let Property Campaign notification and disclosure, reflecting their own share of the income and their own personal tax position (including their own personal allowance, tax band, and other income). Our guide on joint tax disclosures covers the practical process of coordinating disclosures between joint owners.

Why the Split Matters for the Overall Tax Bill

Because Income Tax is charged on each individual separately, the way income is split between joint owners can genuinely affect the total tax bill for the household — particularly where one owner pays tax at a higher rate than the other, or where one owner has unused personal allowance. This is a legitimate area for forward-looking tax planning (via a genuine change in beneficial ownership and a Form 17 election), but for a historic disclosure, the split needs to reflect what actually applied during each year in question, not what would have been most tax-efficient with hindsight.

Married Couples Considering Tax-Efficient Ownership Going Forward

Once the historic disclosure is dealt with, some couples find it worth reviewing their ownership structure for future years, particularly where one spouse’s income sits in a lower tax band. Our guide on tax planning strategies for married couples and civil partners covers this in more detail, including how a Form 17 election and a change in beneficial ownership can work together going forward.

What Records You’ll Need

  • Evidence of the legal and beneficial ownership structure — the title deeds, and any declaration of trust
  • Any Form 17 elections made, and the effective date each one took effect
  • Records of any change in ownership shares during the disclosure period
  • Rental income and expense records, which can generally be shared between joint owners rather than duplicated

Our guide on property ownership structures in the UK is a useful companion resource for understanding how different ownership arrangements affect the tax position more broadly.

How Many Years Does Each Owner Need to Cover?

The look-back period is generally assessed per individual, based on their own circumstances and behaviour, rather than automatically applying the same number of years to both joint owners. In practice, since both owners are usually disclosing the same underlying property and income history, the years covered often end up aligned, but it’s worth confirming this rather than assuming. Our guide on how many years you need to declare sets out the general framework.

How Felix Accountants Can Help

We regularly help couples and joint owners work through exactly this kind of disclosure, correctly establishing the ownership split for each relevant year, preparing separate but coordinated disclosures for each individual, and making sure the numbers add up consistently across both. Get in touch to talk through your specific ownership situation.

Frequently Asked Questions

Is jointly owned rental income automatically split 50:50 between married couples?

Yes, by default, for married couples and civil partners, unless a valid Form 17 election has been made declaring a different split based on actual unequal ownership shares.

Can we backdate a Form 17 election to cover the years we’re disclosing?

No. A Form 17 election only takes effect from the date HMRC receives a valid declaration — it can’t be applied retrospectively to earlier tax years where no election was in place.

Does the 50:50 rule apply to unmarried couples too?

No. The 50:50 default is specific to married couples and civil partners. Unmarried co-owners are generally taxed according to their actual beneficial ownership shares.

Do both joint owners need to make separate Let Property Campaign disclosures?

Generally yes, since each individual is separately responsible for their own share of rental income and their own tax position, though the disclosures are usually coordinated to reflect the same underlying facts.

What if our ownership share changed partway through the years we’re disclosing?

The income split for each tax year should reflect the ownership arrangement that actually applied during that specific year, rather than applying the current ownership split retrospectively.

Let’s sort out your joint property disclosure together. Book your free 15-minute consultation with Felix Accountants.
Categories
Articles Articles Blogs Let Property Campaign News

Bookkeeping for Limited Companies: What Records Should Directors Maintain?

Running a limited company comes with a specific set of legal record-keeping obligations that go beyond what’s expected of a sole trader — partly because a company is a separate legal entity from its directors and shareholders, and partly because Companies House and HMRC each have their own requirements. Getting organised early makes year-end accounts, Corporation Tax returns, and any future due diligence considerably smoother.

Want help setting up proper bookkeeping for your limited company? Book a free 15-minute consultation with Felix Accountants. Book your free call here.

Two Categories of Records: Statutory and Accounting

Limited company record-keeping falls into two related but distinct categories:

  • Statutory records: company-level records required by Companies House, covering the company’s legal structure and governance
  • Accounting records: financial records required by both Companies House (to prepare accurate statutory accounts) and HMRC (to support the Company Tax Return)

Directors are legally responsible for maintaining both, even where day-to-day bookkeeping is outsourced to an accountant or bookkeeper.

Statutory Records Every Company Must Maintain

  • Register of members (shareholders)
  • Register of directors and their service addresses
  • Register of people with significant control (PSC register)
  • Records of resolutions and minutes of general meetings and board decisions
  • Register of charges, where the company has secured debt against its assets

Many of these are also filed at Companies House and kept up to date through the annual confirmation statement, but the company itself is still required to maintain its own internal registers, whether physically or digitally. Our company secretarial services cover the ongoing maintenance of these records if you’d rather not manage them in-house.

Accounting Records Every Company Must Maintain

Separately from the statutory registers, companies must keep sufficient accounting records to show and explain the company’s transactions, and to allow accurate financial statements to be prepared. In practice, this generally includes:

  • Records of all money received and spent by the company, including the reason for each transaction
  • A record of the company’s assets and liabilities, including what the company owns and owes
  • Records of goods bought and sold, including invoices issued and received, for companies dealing in goods
  • Stock records at the end of each financial year, where the company holds stock
  • Details of stocktaking used to arrive at stock figures, where applicable
  • Records supporting all business expenses claimed, including receipts and invoices, particularly for allowable limited company expenses

Bank Records

Every limited company should operate through its own dedicated business bank account, entirely separate from any director’s personal finances — this isn’t just good practice, it’s essentially required by the legal separation between a company and its owners. Bank statements form a core part of the accounting record trail, and regular bank reconciliation against your bookkeeping software helps catch errors early rather than at year end.

Director’s Loan Account Records

Where money moves between a director personally and the company outside of salary or dividends — for example, a director lending money to the company, or drawing money that isn’t yet formally declared as salary or dividend — this needs to be tracked carefully through a director’s loan account. Poor record-keeping here is a common source of problems, since an unclear or overdrawn director’s loan account can create unexpected tax charges, both for the company and the director personally.

Payroll Records

If the company has any employees, including directors paid a salary, payroll records need to be maintained separately, covering pay, tax and National Insurance deductions, and the underlying Real Time Information submissions made to HMRC. See our guide on small business payroll explained for what’s involved in running this correctly.

VAT Records, If Registered

VAT-registered companies have an additional layer of record-keeping requirements, including VAT invoices issued and received, and — under Making Tax Digital — digital records maintained through compatible software rather than manual spreadsheets alone. Our Making Tax Digital guide covers what this means in practice.

How Long Do Records Need to Be Kept?

For most companies, accounting records generally need to be retained for at least six years from the end of the relevant accounting period, though this can be longer in specific circumstances — for example, where the company buys something that it expects to last more than six years, such as equipment or property, or if the company is subject to an ongoing HMRC enquiry. It’s a sensible default to retain everything for at least six years even where a shorter minimum might technically apply, given how straightforward digital storage has become.

Choosing a Bookkeeping System

Beyond the legal minimum, most directors find that cloud accounting software, linked directly to the company bank account, makes ongoing compliance considerably easier than manual spreadsheets — particularly for VAT-registered companies needing Making Tax Digital compatibility, and for directors who want an accurate, real-time view of the company’s financial position rather than reconstructing it at year end.

What Happens If Records Aren’t Properly Maintained?

Failing to keep adequate accounting records is a company law offence, and directors can be personally liable for penalties or, in more serious cases, disqualification. Beyond the legal risk, poor records also make it far harder to prepare accurate statutory accounts and tax returns, increase accountancy costs (since more time is spent reconstructing information), and create real problems if the company is ever sold, audited, or subject to an HMRC enquiry.

How Felix Accountants Can Help

We help directors set up bookkeeping systems and statutory record-keeping processes that meet both Companies House and HMRC requirements from day one, whether that’s a fully managed bookkeeping service or guidance to help you manage it confidently yourself. See our wider business tax services for how well-organised records feed into accurate, efficient annual compliance.

Frequently Asked Questions

What’s the difference between statutory records and accounting records?

Statutory records relate to the company’s legal structure — shareholders, directors, and governance decisions. Accounting records relate to the company’s financial transactions, assets and liabilities, used to prepare accounts and tax returns.

How long must a limited company keep its accounting records?

Generally at least six years from the end of the relevant accounting period, though this can be longer in specific circumstances, such as an ongoing HMRC enquiry.

Do I need a separate bank account for my limited company?

Yes, effectively. A company is a separate legal entity from its directors, and its finances should be kept entirely separate from any director’s personal banking.

What is a director’s loan account and why does it need careful records?

It tracks money moving between a director personally and the company outside of formal salary or dividends. Poor record-keeping here can lead to unexpected tax charges if the account becomes unclear or overdrawn.

What happens if a company doesn’t keep proper accounting records?

It’s a company law offence, and directors can be held personally liable. It also makes accurate accounts and tax returns far harder to prepare, and creates problems for any future sale, audit or HMRC enquiry.

Let’s get your company’s records properly organised. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Articles Blogs Let Property Campaign News

Let Property Campaign and Furnished Holiday Let Income: What Landlords Should Check

Owners of holiday cottages, coastal Airbnbs and other short-term let properties have historically benefited from more generous tax treatment than standard buy-to-let landlords. That changed significantly from April 2025, when the Furnished Holiday Lettings (FHL) tax regime was abolished. If you have undeclared income from a furnished holiday let, this shift makes it more important than ever to understand exactly which rules apply to which years — because the position before and after April 2025 is genuinely different, and a Let Property Campaign disclosure needs to reflect that.

Undeclared income from a holiday let or short-term rental? Book a free 15-minute consultation with Felix Accountants and we’ll help you work through the detail. Book your free call here.

What Was the Furnished Holiday Lettings Regime?

Until 5 April 2025, properties that qualified as Furnished Holiday Lets benefited from a range of tax advantages not available to standard residential lettings, including full relief for mortgage interest and other finance costs (rather than the restricted basic-rate credit that applies to standard buy-to-lets), the ability to claim capital allowances on furniture and equipment, treatment of profits as relevant earnings for pension contribution purposes, and access to certain Capital Gains Tax reliefs, including Business Asset Disposal Relief, on eventual sale.

What Changed From April 2025?

From 6 April 2025 for Income Tax and Capital Gains Tax (1 April 2025 for Corporation Tax), the FHL regime was abolished, and qualifying properties are now taxed in essentially the same way as any other residential letting. This means finance costs are now restricted to the basic-rate tax credit, new capital allowances claims have generally stopped (with “replacement of domestic items relief” available instead in many cases), and the favourable Capital Gains Tax treatment on disposal has been withdrawn other than in limited transitional circumstances.

Why This Matters for a Let Property Campaign Disclosure

If you’re disclosing undeclared income from a property that qualified as a furnished holiday let, the calculation needs to be split at the April 2025 boundary:

  • For years up to and including 2024/25: if the property genuinely met the FHL qualifying conditions, the more generous FHL rules (full finance cost relief, capital allowances, etc.) would have applied
  • For 2025/26 onwards: the property is taxed under the standard residential letting rules, meaning restricted mortgage interest relief and the other changes described above

Getting this split right matters because applying the wrong rules to the wrong years can significantly under- or over-state what’s owed. This is a more technical calculation than a standard buy-to-let disclosure, and it’s an area where professional advice is genuinely valuable.

Did Your Property Actually Qualify as an FHL?

Before assuming the FHL rules applied for earlier years, it’s worth checking whether the property genuinely met the qualifying conditions during those periods, which broadly required the property to be available for letting on a commercial basis for a set number of days per year, actually let for a minimum number of days, and not normally occupied by the same tenant for long continuous periods. A property let short-term through platforms like Airbnb doesn’t automatically qualify as an FHL simply because of how it was marketed — the specific letting pattern needs to be checked year by year.

Joint Ownership Changes Are Worth Checking Too

Another change worth being aware of: under the old FHL rules, jointly owned couples could flexibly allocate profits between themselves, reflecting who actually did the work, rather than following the strict ownership split. From April 2025, furnished holiday lets are subject to the same default rules as standard jointly owned property, generally a 50:50 split unless a valid election has been made. If your disclosure involves a jointly owned former FHL, this is worth reviewing carefully for the years either side of the change.

What About VAT for Short-Term Lets?

Separately from Income Tax, holiday accommodation is generally treated as a standard-rated supply for VAT purposes, unlike most long-term residential letting, which is typically exempt. If your short-term let income (combined with any other taxable turnover) exceeds the VAT registration threshold, VAT registration and reporting obligations may also need reviewing alongside the Income Tax disclosure. Our property tax guide covers how different letting types are treated for tax purposes more broadly.

Working Out How Many Years to Disclose

The look-back period for a Let Property Campaign disclosure is generally determined by the reason for non-disclosure rather than the type of letting involved, so the same principles apply to holiday lets as standard buy-to-lets. Our guide on how many years you need to declare sets out the general framework, though the added complexity of the FHL-to-standard-letting transition means the year-by-year calculation itself takes more care to get right.

What You’ll Need to Gather

  • Booking records or platform statements showing income received each year
  • Evidence of letting pattern (nights let, availability) to confirm FHL qualification for pre-2025/26 years
  • Mortgage interest statements and records of capital expenditure on furniture and equipment
  • Details of the ownership structure, particularly for jointly owned properties

How Felix Accountants Can Help

Disclosing undeclared income from a former furnished holiday let is genuinely more involved than a standard residential letting disclosure, given the rule change partway through the relevant period. We help holiday let owners establish which years qualified under the old FHL rules, apply the correct treatment either side of April 2025, and manage the disclosure process through our Let Property Campaign guide and wider disclosure services.

Frequently Asked Questions

Does the Furnished Holiday Lettings regime still exist?

No. It was abolished from 6 April 2025 for Income Tax and Capital Gains Tax purposes (1 April 2025 for Corporation Tax). Holiday let properties are now generally taxed in the same way as standard residential lettings.

Do I still get full mortgage interest relief on my holiday let?

Only for years up to and including 2024/25, if the property genuinely qualified as an FHL during those years. From 2025/26 onwards, mortgage interest relief is restricted to a basic-rate tax credit, the same as standard buy-to-let properties.

How do I know if my property actually qualified as an FHL in earlier years?

Qualification depended on meeting specific letting-pattern conditions each year, including availability and actual letting days. It’s worth reviewing this year by year rather than assuming qualification based on how the property was marketed.

Is holiday let income treated differently for VAT?

Yes. Holiday accommodation is generally standard-rated for VAT, unlike most long-term residential letting, which is usually exempt. This may create a separate VAT registration obligation if turnover exceeds the threshold.

Can I still use the Let Property Campaign for undeclared holiday let income?

Yes, the Let Property Campaign covers undeclared residential letting income generally, including furnished holiday lets, though the calculation needs to correctly reflect the rules that applied in each specific tax year.

Get your holiday let’s tax position properly reviewed. Book your free 15-minute consultation with Felix Accountants.


Categories
Articles Blogs Let Property Campaign News

Let Property Campaign Disclosure: How Should Landlords Deal With Missing Rental Records?

One of the most common reasons landlords put off making a Let Property Campaign disclosure isn’t reluctance — it’s fear that they simply don’t have the paperwork to back it up. Old tenancy agreements have been lost, bank accounts have been closed, and receipts for repairs from six years ago were never kept. The reassuring truth is that missing records don’t stop you from making a valid disclosure; HMRC expects landlords in this position and accepts carefully reasoned estimates, provided they’re built on a sensible method rather than guesswork.

Missing paperwork doesn’t have to hold up your disclosure. Book a free 15-minute consultation with Felix Accountants and we’ll help you map out exactly what you can reconstruct. Grab a free slot here.

Why Missing Records Are So Common Among Landlords Disclosing Under the LPC

Most landlords who end up using the Let Property Campaign weren’t running a professional letting business from day one. Many became landlords by accident — inheriting a property, relocating for work, or renting out a former family home — and never set up formal bookkeeping. Years later, when it’s time to disclose, bank statements have often been archived beyond easy online access, letting agents have changed hands, and receipts were simply thrown away. This is normal, and it’s exactly the scenario HMRC’s disclosure process is built to accommodate.

Start With What You Can Actually Access

Before assuming records are gone for good, it’s worth checking a few sources that are often more complete than landlords expect:

  • Online banking archives: most UK banks retain digital statements for 6–7 years and can often provide older statements on request, sometimes for a small fee
  • Letting agent portals or year-end statements: agents typically issue annual income summaries, which are far easier to request than reconstructing every transaction
  • Mortgage statements: useful for establishing the interest paid, which is a major allowable cost
  • Insurance renewal documents: confirm landlord insurance costs and the dates the property was actually let
  • Land Registry and conveyancing paperwork: confirms purchase date, sale date (if applicable), and ownership history

Our guide to record keeping sets out the categories of documents HMRC typically expects landlords to retain, and is a useful checklist even when working backwards from an incomplete starting point.

When Records Genuinely Don’t Exist: Building a Reasonable Estimate

Where source documents can’t be recovered, HMRC allows landlords to use reasonable estimates, as long as the method is transparent and defensible. A sound approach usually involves:

  • Establishing the letting period from tenancy start/end dates, Land Registry records, or correspondence with a former letting agent
  • Using average local market rents for a comparable property over the relevant years as a cross-check against any partial records you do have
  • Applying a consistent, conservative approach to expenses — only claiming costs you can reasonably evidence or that are typical and proportionate for the property type
  • Documenting the assumptions behind every estimate in writing, so the methodology can be explained if HMRC asks questions later

This is where working with an accountant experienced in Let Property Campaign disclosures makes a real difference. We’ve supported landlords who arrived with almost nothing beyond a mortgage statement and a rough idea of when tenants moved in, and helped them build a disclosure that HMRC accepted without further challenge.

Missing Records Don’t Change Your Look-Back Period

It’s worth being clear that having incomplete records doesn’t reduce how many years you need to disclose. The look-back period is determined by the reason the income wasn’t declared — careless error, failure to take reasonable care, or deliberate non-disclosure — not by how much paperwork survives. Our article on how many years you need to declare explains this in more detail, and it’s a good starting point before you begin reconstructing figures, so you know exactly which tax years to focus on.

The 90-Day Window and Why Preparation Matters

Once you notify HMRC of your intention to disclose under the Let Property Campaign, you generally have 90 days to submit the full disclosure and calculate what’s owed. Trying to reconstruct several years of missing records within that window, under time pressure, is far harder than starting the reconstruction work before you notify HMRC. Our 90-day deadline prep guide walks through how to use that period efficiently if you’ve already notified, but the ideal approach is to begin gathering what you can before you formally start the clock.

What Counts as a Reasonable Excuse — and What Doesn’t

Missing records themselves aren’t usually accepted as a reason not to disclose at all, but the circumstances behind why records went missing can matter for how HMRC views your overall behaviour. Genuinely losing paperwork in a house move, a bereavement, or simply never having set up formal bookkeeping as an accidental landlord is treated very differently from deliberately destroying evidence. Being upfront about why records are incomplete, rather than presenting rough figures as if they were exact, tends to support a smoother disclosure.

Common Mistakes to Avoid When Records Are Incomplete

  • Rounding figures without any supporting logic, rather than using a documented estimation method
  • Ignoring years where you’re unsure of the exact rent, hoping HMRC won’t notice — this significantly increases risk if discovered later
  • Claiming expenses you can’t reasonably evidence or that seem disproportionate to the size of the letting
  • Waiting indefinitely to “find better records” instead of starting the disclosure with a reasonable, well-documented estimate

See our broader guide on the top bookkeeping mistakes landlords make for related pitfalls worth avoiding going forward.

How Felix Accountants Helps When Your Records Are Incomplete

We regularly work with landlords who come to us with partial, patchy, or almost non-existent records for the years in question. Our process involves piecing together what’s available, applying recognised estimation techniques where genuine gaps exist, and preparing a disclosure that stands up to scrutiny. You can read more in our LPC disclosure guide or get in touch directly to talk through your specific situation.

Frequently Asked Questions

Can I make a Let Property Campaign disclosure without any bank statements?

Yes, in principle. If bank statements aren’t available, other evidence such as letting agent statements, tenancy agreements, or a reasonable, documented estimate based on comparable market rents can be used instead.

Will HMRC reject my disclosure if some figures are estimates?

Not usually, provided the estimates are reasonable, consistently applied, and clearly explained as estimates rather than presented as exact figures without qualification.

Should I wait until I’ve found all my missing records before notifying HMRC?

Generally no. It’s better to begin the record-reconstruction process first, then notify HMRC once you have a workable picture, since the 90-day disclosure window starts as soon as you notify.

Does having incomplete records mean I’ll face higher penalties?

Not on its own. Penalties are primarily driven by whether the disclosure is prompted or unprompted and the underlying behaviour (careless versus deliberate), not simply by the state of your paperwork.

Can an accountant help reconstruct years of missing rental records?

Yes, this is one of the most valuable parts of working with an experienced property accountant during a Let Property Campaign disclosure, as we can apply consistent, defensible methods across multiple tax years.

Don’t let missing paperwork stop you from disclosing. Book your free 15-minute consultation with Felix Accountants and we’ll help you build a disclosure that works with what you actually have.


Categories
Articles Articles Blogs Let Property Campaign News

Let Property Campaign: Can You Disclose Rental Income From a Property You No Longer Own?

If you used to let out a property but have since sold it, gifted it, or moved back in yourself, you might assume that any undeclared rental income from those years is now somehow out of reach of HMRC. It isn’t. The good news is that selling the property doesn’t close the door on putting things right — you can still use the HMRC Let Property Campaign to disclose rental income from a property you no longer own, and doing so voluntarily is almost always better than waiting to be found.

Not sure where you stand with a property you’ve already sold? Book a free 15-minute consultation with Felix Accountants and we’ll talk through your situation in plain English, with no obligation. Reserve your free call here.

Does Selling a Rental Property Remove Your Obligation to Declare Past Rent?

No. Your obligation to report rental income relates to the tax years in which you actually received that income, regardless of whether you still own the property today. If you let out a property between, say, 2019 and 2023 and then sold it, you were still legally required to report the rent you received during those years on a Self Assessment tax return. Selling the property doesn’t erase that history — it simply means the disclosure now covers a property that no longer appears on your current asset list.

This is one of the most common misunderstandings we see at Felix Accountants. Landlords often believe that once a property is sold, any loose ends relating to it are automatically tidied up. In reality, HMRC’s Let Property Campaign was specifically designed to capture exactly this kind of situation — current landlords, former landlords, and anyone in between with unreported letting income.

Who Can Use the Let Property Campaign for a Former Rental Property?

The Let Property Campaign is open to individual landlords who have received undeclared rental income from residential property in the UK or abroad. This includes people who:

  • Sold the rental property some years ago but never declared the rent received while they owned it
  • Inherited a property, let it out for a period, and later sold it
  • Moved back into a property that was previously let to tenants
  • Gifted or transferred a rental property to a family member and stopped receiving rent from it
  • Were an accidental landlord for a short period before selling

In every one of these cases, the fact that the property has moved on doesn’t change the underlying tax history. What matters to HMRC is the income you received while you owned and let the property, not whether you still hold the title today.

How Far Back Do You Need to Declare?

The look-back period depends on why the income wasn’t declared in the first place, not on when you sold the property. As a general guide:

  • Genuine, careless error: typically up to 4–6 years
  • Failure to take reasonable care: up to 6 years
  • Deliberate non-disclosure: HMRC can go back as far as 20 years

We’ve written a more detailed breakdown of this in our guide on how many years you need to declare and our companion article on how many years of rental income landlords must disclose. If the property has since been sold, you’ll still need to work out the correct number of years based on when you first started letting it and when the undeclared income actually stopped, which for a sold property is usually the completion date.

What About Capital Gains Tax on the Sale Itself?

A disclosure through the Let Property Campaign covers rental income and any related expenses, not the sale of the property. However, if you sold the property at a profit, you may separately owe Capital Gains Tax on that sale, and UK residential property sales generally need to be reported to HMRC within 60 days of completion. If both the rental income and the sale itself were never reported, it’s sensible to deal with both matters together rather than treating them as separate problems, since HMRC will often be looking at your full history once a disclosure is opened.

Why Voluntary Disclosure Still Matters After the Sale

Coming forward voluntarily, before HMRC contacts you, generally results in significantly lower penalties than a prompted disclosure that follows an HMRC letter or enquiry. Our article on prompted versus unprompted disclosures sets out the practical difference in more detail, but the short version is this: HMRC has extensive data-matching capability drawn from Land Registry records, Stamp Duty Land Tax returns, letting agent reporting and platforms such as Airbnb, so a sold property is not invisible simply because you no longer own it. Making the first move, through our voluntary disclosure guidance, gives you more control over the outcome, the tone of the process and the penalty percentage applied.

What You’ll Need to Gather

Because you no longer own the property, you may not have easy access to the same records a current landlord would. It’s still worth trying to pull together:

  • Bank statements showing rent received during the letting period
  • Tenancy agreements or letting agent statements, if available
  • Records of allowable expenses such as mortgage interest, insurance, repairs and letting agent fees
  • The completion date of the sale, and the purchase and sale prices, in case a Capital Gains Tax position also needs reviewing

If some records are missing entirely, that’s a common and manageable problem — HMRC accepts reasonable estimates provided they’re clearly labelled and based on a sensible methodology, rather than guesswork presented as fact.

How Felix Accountants Can Help

We regularly help former landlords work through reporting undisclosed rental income to HMRC, including cases where the property has already been sold, gifted, or repossessed. We’ll help you reconstruct a reasonable income and expense history, calculate what’s owed, and manage the notification and disclosure process on your behalf so you’re not dealing with HMRC directly and unrepresented.

Frequently Asked Questions

Can I still be investigated if I sold the rental property years ago?

Yes. HMRC’s ability to open an enquiry into undeclared rental income isn’t affected by a subsequent sale. The tax liability relates to the years you received the income, and HMRC can pursue this regardless of your current ownership status.

Do I need to disclose if the rental profit was very small?

Generally yes. There’s no minimum threshold that exempts small amounts of rental profit from disclosure, although your allowable expenses and personal allowance may mean little or no tax is ultimately due once everything is calculated correctly.

What if I can’t find all my old records for a property I no longer own?

This is common, particularly for properties sold some years ago. HMRC accepts reasonable, clearly explained estimates where original records aren’t available. An accountant experienced with the Let Property Campaign can help you build a defensible estimate.

Will disclosing affect the sale I’ve already completed?

No. The sale itself is a separate, completed transaction. A Let Property Campaign disclosure deals with the historic rental income tax position and won’t unwind or affect the property sale.

Is it too late to make a voluntary disclosure?

It’s rarely too late to disclose voluntarily unless HMRC has already contacted you about the specific property. Acting before any HMRC letter arrives keeps your disclosure classed as unprompted, which generally attracts lower penalties.

Ready to sort out a property you’ve already sold? Felix Accountants specialises in Let Property Campaign disclosures for current and former landlords. Book your free 15-minute consultation and let’s work out exactly where you stand.


Categories
News

Let Property Campaign Voluntary Disclosure: Why Coming Forward Now Costs You Less

HMRC is not standing still on undeclared rental income. The Spring Budget committed an extra £100 million to fund 500 new compliance officers, alongside £79 million earmarked for third-party debt collection over the next five years — on top of the 1,800 debt management roles already announced in the previous Autumn Budget. In plain terms: HMRC’s ability to find undeclared rental income is growing fast, and landlords who wait are taking on more risk with every month that passes.

The good news is that landlords who come forward under the Let Property Campaign before HMRC contacts them can pay meaningfully lower penalties and sidestep a full-blown investigation. This article breaks down exactly how much that difference is worth in practice, using real calculation examples, and what to do if you can’t pay everything you owe at once.


Not sure what your voluntary disclosure would actually cost? Book a free discovery call and we’ll walk through your numbers with you.

👉 Book your free discovery call


Why Timing Changes the Penalty You Pay

The single biggest lever landlords have over their own penalty bill is when they come forward. Disclose voluntarily, ahead of any HMRC enquiry, and the penalty bands sit meaningfully lower than if HMRC opens a compliance check first. Once HMRC initiates that enquiry, the more favourable rates disappear.

This applies whether your rental income was never reported to HMRC at all, or whether you filed a return but left the property income off it — HMRC treats these as two separate situations, each with its own behaviour categories.

How HMRC Classifies Your Behaviour

Where a landlord never registered for tax and never filed a return covering the rental income, HMRC groups the reason into one of three bands:

  • Non-deliberate — the omission stemmed from a genuine misunderstanding or circumstance, not an intent to avoid tax.
  • Deliberate (not concealed) — the landlord knew the income should have been reported and chose not to, but took no further steps to hide it.
  • Deliberate and concealed — the landlord not only withheld the income but actively worked to disguise it.

Where a return was filed but the rental income was left out or understated, a slightly different set of categories applies:

  • Reasonable care — HMRC doesn’t set a fixed test here; it’s judged case by case, but landlords are generally expected to seek advice when they’re unsure of the rules and to file accurate figures.
  • Careless — the return was wrong because reasonable steps weren’t taken to get it right, such as poor recordkeeping or overlooking a known obligation.
  • Deliberate — the landlord knew the figures were wrong and submitted the return anyway, for example by understating rental income or overstating costs.
  • Deliberate and concealed — the landlord not only filed an inaccurate return but took active steps to cover it up, such as producing a fabricated invoice for repair work that never happened.

What Actually Reduces Your Penalty

Beyond the behaviour category, HMRC also looks at the quality of the disclosure itself when setting the final penalty. A strong disclosure is scored across three elements:

  • Telling HMRC about the problem — worth up to 30% of the reduction
  • Helping HMRC understand what happened — worth up to 40%
  • Giving HMRC access to the records behind it — worth up to 30%

The more complete and cooperative the disclosure, the more the penalty can be reduced from the maximum. For landlords weighing up their overall position, our tax-saving strategies guide covers the legitimate ways to manage the ongoing liability once everything is up to date.

Case Study: Failure to Notify (Ben’s Eight Properties)

Ben has owned eight rental properties generating income since the 2016/17 tax year, and never filed a tax return covering any of it. His annual rental income sat around £45,000, with net profits — after deductions and mortgage interest — starting near £33,000 and rising year on year. His PAYE employment income began at £80,000 and grew by roughly 3% annually.

Once the calculation runs through to 2022/23, Ben’s total unpaid tax comes to £113,969. Assuming his behaviour is classed as non-deliberate and he cooperates fully, working through the applicable penalty rates:

  • Voluntary disclosure (before HMRC contacts him): total cost of £155,710
  • Prompted disclosure (after HMRC contacts him): total cost of £167,107

That’s a difference of £11,397 — purely down to coming forward first.

There’s a further wrinkle: HMRC generally won’t accept the most recent tax year as part of a Let Property Campaign disclosure. So a landlord disclosing for 2023/24, for example, would typically be asked to file that year’s return separately, which then carries its own late filing and late payment penalties.

If that 2023/24 return were filed six months late, the numbers would look like this:

Late filing penalties:

  • Initial penalty: £100
  • Daily penalties (up to 90 days): £900
  • Six-month penalty (the greater of £300 or 5% of unpaid tax): £999.30

Total late filing penalties: £1,990.30

Late payment:

  • 5% surcharge on unpaid tax: £999.30
  • Interest on the late payment: £771

Total estimated penalties for 2023/24 alone: £4,759.90

Landlords in Ben’s position want to know their exact exposure before they disclose, not after — this is exactly the kind of number our specialists work through on a discovery call.

Case Study: Inaccurate Returns (Ms Kim’s Rental Income)

Ms Kim runs a consultancy business that returned trading profits of £130,000 in 2018/19, growing at around 5% a year since. Alongside that, she owns two rental properties, cash-purchased with no mortgage, which brought in £28,000 gross in 2018/19 — £21,000 after £7,000 of allowable expenses. That rental income was never included on her Self Assessment return, and stayed missing from every year since, with income and costs both rising roughly 7% annually.

By 2022/23, her total unpaid tax comes to £59,409.

Her 2023/24 position is different, because a return for that year has already been filed. Since it’s within the amendment window (open until 31 January 2026), she can correct it directly without incurring additional late-filing penalties — though because the original payment deadline was 31 January 2025, late payment penalties and interest still apply.

Working through the penalty rates for the earlier years:

  • Voluntary disclosure: total cost of £85,443
  • Prompted disclosure: total cost of £94,354

A difference of £8,911 simply for disclosing before HMRC gets there first.

For 2023/24 specifically, if paid promptly:

  • Late payment penalty (5% of £12,614): £631
  • Interest on late payment: £355

Total tax, interest and penalty for 2023/24: £13,600

What If You Can’t Pay Everything Up Front?

HMRC expects payment in full at the point of disclosure — but that’s not always realistic, and it’s not a reason to delay. If you can’t cover the whole amount, the correct move is to contact HMRC’s Let Property Campaign helpline before you submit your disclosure or make any payment.

HMRC will want to understand your financial position to agree a realistic payment plan. Be ready to provide:

  • Your disclosure reference number
  • How and when you plan to pay what’s owed
  • Your current income and outgoings, weekly or monthly
  • What you own — property, vehicles, savings, investments
  • What you owe — mortgages, loans, credit cards

Submitting a disclosure (or payment) before this conversation has happened, when you genuinely can’t pay in full, can create more problems than it solves.

The Bottom Line

HMRC’s enforcement capacity is only growing, and every month of delay adds interest, risk, and — if HMRC gets there first — significantly higher penalties. Whether the gap in your case was an honest oversight or something more deliberate, the Let Property Campaign rewards landlords who come forward on their own terms rather than waiting to be found.

Ready to find out what your voluntary disclosure would actually cost?

👉 Book a free discovery call

Categories
Articles Blogs News

Reporting Undisclosed Rental Income to HMRC: What Landlords Need to Know

If HMRC has never heard about some or all of your rental income, the Let Property Campaign is the mechanism built specifically to fix that. It gives residential landlords a formal way to bring past tax years up to date — and, more often than not, it’s simply a question of when you report it rather than whether HMRC eventually finds out on its own.

This guide covers how HMRC actually identifies undisclosed rental income, who the campaign is open to, the exact steps involved in making a disclosure, and what happens if HMRC pushes back on your figures.


Received a letter from HMRC, or just want to check your position before they get in touch? Book a free discovery call and we’ll talk it through.

👉 Book your free discovery call


How HMRC Actually Finds Undisclosed Rental Income

It’s tempting to assume small or informal lettings fly under the radar. In practice, HMRC pulls from a wide net of sources: letting agent records, land registry filings, council tax data, mortgage applications, and even reports from members of the public. Where the data points to rental income that hasn’t been matched against a tax return, HMRC will often reach out directly, inviting the landlord to use the Let Property Campaign to put things right.

The key detail here is timing. You don’t have to wait for that letter. Landlords who register for the campaign proactively — before any contact from HMRC — are treated more favourably, with faster resolution and materially lower penalties than those who only respond once HMRC has already made contact.

Who the Campaign Is Open To

The Let Property Campaign covers a broad range of residential landlords, including:

  • Landlords with one or more residential properties, whether in the UK or overseas
  • Individuals renting out a room in their own home under the Rent a Room Scheme
  • Landlords letting to students, workforce tenants, or similar groups
  • Holiday let landlords

Who Can’t Use It

A few situations fall outside the scope of the campaign:

  • Commercial property — shops, garages, and lock-ups aren’t covered on their own, though a mixed portfolio with a residential component can still use the campaign for that portion
  • Companies and trusts — these need to use a different disclosure route entirely; the campaign is for individuals
  • Directors and commercial landlords — separate disclosure methods apply here too

Joint ownership is treated individually, not jointly. Where a property is owned by more than one person, each owner needs to make their own separate disclosure covering their share of the profit — a single combined submission isn’t accepted.

The Disclosure Process

1. Notify HMRC of your intent If HMRC hasn’t already been in touch, you register your intention to disclose and receive a reference number in return.

2. Quantify the undisclosed income Within 90 days of getting that reference number, work out all previously undisclosed income and gains across every year HMRC can still assess — and this isn’t limited to rental income alone; any other undisclosed business or investment income within scope should be included too.

3. Calculate what’s owed Work through the additional tax, interest, and penalties due for each affected tax year.

4. Make a formal offer Submit a formal offer to HMRC to settle everything in full and final settlement of your historical position.

5. Pay using your reference number Once the offer is submitted, use your Payment Reference Number to settle the agreed amount.

6. Submit full supporting detail Alongside your calculations and offer, provide a comprehensive account of the facts and assumptions behind your figures.

What happens after submission: HMRC typically sends an acknowledgement within around two weeks, followed by internal checks. If they’re satisfied, you’ll receive a formal acceptance letter closing the matter. If not, expect follow-up questions aimed at verifying your figures.

Going forward, staying compliant means registering for Self Assessment if you haven’t already, and reporting all income and gains through your annual return from that point on.

There’s real value in professional input at this stage — not just to get the numbers right, but because there are legitimate technical arguments that can reduce both the number of years included and the resulting penalty. For a closer look at how everyday situations turn into undisclosed income in the first place, our article on common landlord tax errors is worth reading alongside this one.

How Many Years Get Included

The number of assessable years isn’t fixed — it depends on the nature of the underlying issue, and our guide on which years you need to declare covers this in full detail.

One point worth flagging clearly: if income or gains were deliberately left off a return, there’s a genuine risk of prosecution, and professional advice on your options is strongly recommended before proceeding. In cases involving deliberate conduct, the Contractual Disclosure Facility is a separate route that can offer immunity from prosecution — a very different mechanism from the Let Property Campaign, and one worth discussing with an advisor if it’s relevant to your circumstances.

What If Your Records Are Incomplete?

Missing historical records don’t remove the obligation to disclose. The expectation is a genuine effort to obtain what documentation still exists, and where gaps remain, reasonable, well-explained assumptions can be used to quantify the income and gains involved.

How the Tax Is Actually Calculated

Tax on previously undeclared profit is worked out using the rates and allowances that applied in each specific tax year in question — not current-year rates applied retrospectively. How much falls due depends on how far income sat above the tax-free personal allowance for that year, and it’s worth making sure every available relief is claimed rather than assumed away.

How the Penalty Is Set

Penalty rates vary by circumstance, but voluntary, high-quality disclosures consistently land at the lower end of the scale. The starting point also differs depending on whether returns were filed incorrectly versus never filed at all.

HMRC reduces penalties based on how the disclosure is handled — often summarised as telling, helping, and giving: coming forward with the issue, actively assisting HMRC in understanding it, and cooperating fully in establishing the correct figures. Landlords weighing up the practical cost difference between disclosing voluntarily and waiting to be contacted may find our voluntary disclosure guide useful, since it walks through real penalty comparisons with worked figures.

If HMRC Disagrees With Your Disclosure

HMRC retains the right to review any disclosure for accuracy and can challenge the assumptions behind it, including requesting the underlying records used to support the figures submitted.

Where a disagreement over the final amount can’t be resolved, HMRC may issue formal assessments for the tax and penalties it believes are due. From there, you retain the right to appeal. If an appeal doesn’t resolve things, further options remain available — including requesting an internal review or taking the matter to the Tax Tribunal for a final decision.

Getting It Right From the Start

A well-prepared disclosure, backed by accurate figures and a clear explanation of the facts, is far more likely to close quickly and without dispute. Given the technical judgement involved in scoping the right years and minimising penalties, most landlords benefit from working through this with an experienced advisor rather than navigating it alone. For the full picture on eligibility and process, our complete Let Property Campaign guide brings everything together in one place.

Ready to find out exactly where you stand?

👉 Book a free discovery call

Categories
Articles Blogs FAQs Guides News

Trying to do everything yourself

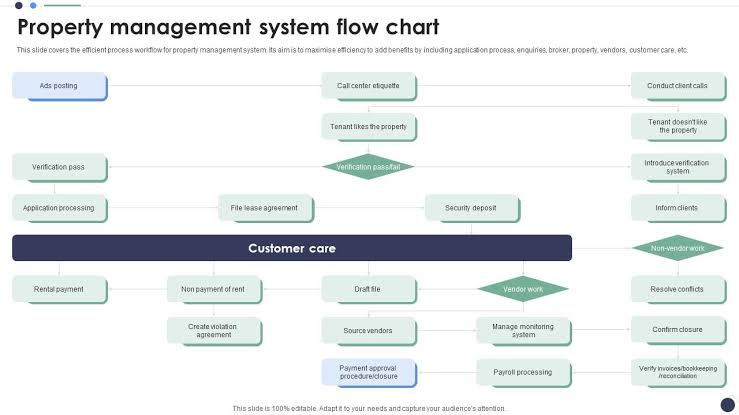
When you start a new property venture, it is tempting to handle every single task yourself. You might be bootstrapping, trying to minimize expenses while navigating initial growth. You handle company registration, website design, tenant screenings, and bookkeeping. However, as your portfolio expands, the operational demands on your time multiply rapidly. Moving from working in your business to working on your business requires a reliable property system to sustain expansion.

Successful property investors view their operations as an entity distinct from their individual identity. They design systematic frameworks that allow their businesses to run smoothly without requiring their constant, hands-on intervention.

Value-Based Time Allocation

Every daily task carries a different notional value. Some operational duties are worth ten pounds an hour, while high-level strategic acquisitions are worth one thousand pounds an hour.

To achieve sustainable scale, you must dedicate your focus to those high-value, thousand-pound activities. This shift means intentionally shifting lower-value administrative tasks to external specialists or trusted software tools.

Task LevelValue Per HourTypical ExamplesOperational Treatment
Low£10 – £20Initial lead entry, social media posting, filing receiptsAutomate or delegate to freelancers
Medium£50 – £100Documenting standard procedures, detailed deal analysisDelegate to specialized team members
High£1000+Strategic joint ventures, capital raising, final acquisition decisionsRetain for principal investor

Core Elements of a Scalable Property System

Delegating tasks before establishing clear processes often leads to costly organizational errors. Before hiring assistants on platforms like Fiverr, Upwork, or People Per Hour, you need to document exactly how you want each operation performed. Clear documentation ensures external support delivers work that matches your personal standards.

1. Documenting Lead Sourcing Procedures

Create an exact checklist detailing how your business sources potential real estate leads. Specify the target geographic areas, maximum purchase thresholds, and acceptable rental yield percentages. When a freelancer understands these parameters, they can filter out irrelevant opportunities, leaving you with highly qualified options.

2. Standardizing Bookkeeping and Compliance

Accurate financial record-keeping keeps your business compliant with regulatory changes. For example, HMRC requires landlords with gross property income exceeding fifty thousand pounds to register for Making Tax Digital (MTD) by April 2026. Having a standardized process for scanning receipts and recording rental income prevents severe penalties.

Important Operational Rule: Always separate your personal and business expenditures completely to avoid accounting complications and potential regulatory scrutiny.

1.Audit Current Time Use:

Week 1.

Track every task you perform for seven days to identify low-value administrative friction points.

2.Draft Standard Operating Procedures:

Week 2.

Write step-by-step instructions for tasks like tenant communications and basic expense tracking.

3.Select Your Outsourcing Platform:

Week 3.

Create accounts on Upwork or specialized virtual assistant platforms to find matching talent.

4.Implement Quality Control Metrics:

Ongoing.

Review the completed work against your documented standards weekly to refine the operational loop.Property System Guide scale Your Portfolio

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture files an inaccurate tax return, HMRC sends a formal notification outlining the financial discrepancy. You will face standard interest charges on the unpaid balance, along with potential penalties calculated based on whether the error was accidental or deliberate. Implementing a secure property system minimizes these financial risks.

How many years can HMRC investigate?

The look-back period depends directly on landlord behavior. If you took reasonable care, HMRC looks back four years. For careless bookkeeping, the window expands to six years. Deliberate tax evasion or failure to notify allows an investigation going back twenty years.

Can HMRC find me after 20 years?

Yes, modern digital tracking makes discovery highly likely. The HMRC Connect system automatically cross-references Land Registry records, bank accounts, and council tax databases to expose undeclared rental streams. Relying on professional property system accounting ensures you do not trigger automated audits.

What if my rental business made a loss 5 years ago?

Legitimate historical property losses fall within the standard investigation window but do not create immediate tax liabilities. You can actively carry forward these documented losses to offset your future rental profits. Keeping your documentation updated via an organized property system protects these valuable deductions.

My partner and I aren’t married. How does that affect the tax?

If the property title belongs strictly to one individual, that person is liable for one hundred percent of the rental income tax. Jointly owned properties typically split the incoming tax obligations fifty-fifty. A structured property system maps these ownership structures to maintain precise tax compliance.

Does HMRC really know if I’m renting out my old flat?

Yes, automated data matching leaves clear digital trails. HMRC regularly tracks changing voter registries, tenancy deposit protection data, and mortgage classifications. An unannounced change in your address often triggers an automated warning letter if no rental income appears on your self-assessment.

I only plan to rent it for a year. Do I still need to tell HMRC?

Yes, all short-term rental income above the one thousand pound annual property allowance must be formally declared. Failing to notify the tax authority because of a short rental timeline still results in automated penalties. Consistent execution through a solid property system avoids these simple compliance oversights.

Can I deduct mortgage interest from my rental income?

Individual residential landlords cannot deduct mortgage interest payments directly from their rental earnings. The old deduction system has been replaced with a fixed twenty percent tax credit. Integrating your portfolio with a professional property system helps track how this restriction impacts higher-rate taxpayers.

If you want to free up your schedule and reduce administrative friction, visit Felix Accountants to establish a compliant framework for your growing business.

Trying to do everything yourselfBook Your Comprehensive Property Tax Review
Categories
Articles Blogs FAQs Guides News

The Best Expert Guide to UK Landlord Tax Deductions in 2026

Understanding UK landlord tax deductions 2026

You must understand UK landlord tax deductions to make the most profit from your rental property. It also helps you avoid paying more tax than necessary in 2026. Therefore, knowing what costs you can legally claim keeps you compliant with HMRC while improving your property tax efficiency.

What are allowable UK landlord tax deductions?

UK property tax efficiency

A cost must be wholly and exclusively for your rental property business to qualify as an allowable expense. These deductions reduce your taxable rental profit and can help landlords manage their tax responsibilities more effectively.

Common UK landlord tax deductions include property safety checks such as gas certificates, EICRs, and fire alarm inspections. Landlords can also claim property management costs, including letting agent fees, tenant referencing, inventory checks, and advertising costs.

Additionally, professional costs such as accounting services and certain legal fees may be deductible. Insurance costs, including landlord insurance, buildings insurance, and liability cover, can also qualify. Travel expenses related to managing the rental property, repairs, or inspections may be allowed if they meet HMRC rules.

Repairs vs Improvements: UK landlord tax deductions

Understanding the difference between repairs and improvements is important because they receive different tax treatment.

Repairs restore a property to its original condition and are normally deductible. Examples include repairing a leaking roof, fixing broken windows, replacing damaged flooring, or repairing an existing boiler.

However, improvements add value or upgrade the property beyond its original state. Examples include building an extension, adding a loft conversion, or installing a luxury kitchen. These costs are usually not deducted from rental income, but keeping records is important because they may help reduce your Capital Gains Tax when selling the property.

How to document expenses for HMRC

HMRC compliance

Keeping accurate records is essential for every landlord. Digital record keeping makes it easier to track expenses and prepare your tax return.

Landlords should keep invoices, receipts, bank statements, and digital copies of expenses. Using accounting software or a receipt management app can prevent missing important deductions. Separating rental income and expenses through a dedicated bank account can also make tax reporting easier.

Good record keeping also helps landlords prepare for changes such as Making Tax Digital (MTD) requirements and ensures evidence is available if HMRC requests supporting documents.

Common grey area deductions

Some landlord expenses are not always straightforward. Many landlords ask whether they can claim administrative costs, home office expenses, or professional membership fees.

Some costs may qualify if they are directly connected to running the rental property business. For example, certain legal costs, property management expenses, and professional advice fees may be allowable. Always check that expenses meet HMRC requirements before claiming them.

Frequently Asked Questions About UK Landlord Tax Deductions 2026

1. What tax deductions can UK landlords claim in 2026?

UK landlords can claim allowable expenses that are directly related to renting out their property. These may include repairs, insurance, letting agent fees, property management costs, accountant fees, safety certificates, and other necessary rental business expenses.

2. Can landlords claim mortgage payments as a tax deduction?

No. Individual landlords cannot normally deduct the full mortgage payment from rental income. However, mortgage interest may qualify for tax relief through the finance cost restriction rules.

3. Are property repairs tax deductible for landlords?

Yes. Repairs that maintain the property and return it to its original condition are usually allowable deductions. Examples include fixing leaks, repairing damage, replacing broken parts, and maintaining existing facilities.

4. What is the difference between repairs and improvements?

Repairs maintain the existing property, while improvements add value or create something new. Repairs are usually deducted from rental income, but improvements are generally treated as capital expenses and may only provide relief when calculating Capital Gains Tax.

5. Can landlords claim letting agent fees?

Yes. Fees paid to letting agents for finding tenants, managing properties, collecting rent, or carrying out tenant checks are normally allowable UK landlord tax deductions.

6. Can landlords claim insurance costs?

Yes. Landlord insurance, buildings insurance, and certain liability insurance costs connected with renting out a property can usually be claimed as allowable expenses.

7. Do landlords need receipts for tax deductions?

Yes. Landlords should keep receipts, invoices, bank statements, and digital records for all claimed expenses. Proper documentation helps support your claims if HMRC requests evidence.

8. Can landlords claim expenses when a property is empty?

Some expenses during an empty period may still qualify if they are necessary for preparing or maintaining the property for rental. The expense must still meet HMRC’s rules for allowable deductions.

9. Can landlords claim accountant fees?

Yes. Professional fees for preparing tax returns, managing rental accounts, and receiving property tax advice can usually be claimed as allowable expenses.

10. How can landlords reduce tax legally in the UK?

Landlords can reduce tax legally by claiming all eligible expenses, keeping accurate records, understanding available tax reliefs, and getting professional advice to structure their property investments efficiently.

Need Help With Your UK Landlord Tax?

Managing rental property taxes can be complicated. Missing allowable deductions could mean paying more tax than necessary. Contact Felix & Co. Accountants for professional property tax advice and support with your 2026 tax return.

Understanding UK landlord tax deductions 2026 helps property owners maximise their rental profits while staying compliant with HMRC rules. From repairs and insurance to professional fees and property management costs, claiming the correct expenses can significantly reduce your taxable rental income.

Landlords should keep detailed records, understand the difference between repairs and improvements, and seek professional advice when unsure. With proper tax planning, landlords can make better financial decisions and manage their property investments more effectively.

Understanding UK landlord tax deductions 2026  Book Your Comprehensive Property Tax Review

Categories
News

How UK Property Accountants Reduced a £9,000+ HMRC Penalty to Nil

A landlord in Berkshire opened a letter from HMRC and saw a penalty demand for more than £9,000. Nine months later, that figure was zero. Nothing about the tax owed had changed. What changed was how the disclosure was handled, and that’s the part most people get wrong.

This is a walkthrough of that case, anonymised for client confidentiality, and what it shows about how HMRC actually calculates and reduces penalties for undeclared rental income.

How the Penalty Reached Over £9,000 in the First Place

The client owned two rental properties in Reading, bought them in 2019 and 2021, and had never registered for Self Assessment on the rental income. This wasn’t tax evasion in any deliberate sense. He’d moved from an employed role into buy-to-let almost by accident, inherited one property, remortgaged to buy the second, and assumed his letting agent or his old employer’s payroll department was somehow “sorting the tax.” Neither was.

HMRC caught up with him through its Connect system, which cross-references Land Registry data, mortgage records, and letting agent reports against Self Assessment filings. He received what’s commonly called a nudge letter, a prompt asking him to check his tax position and come forward voluntarily. Ignoring it, or responding badly, is what usually turns a manageable situation into an expensive one. We’ve written before about what to do when an HMRC nudge letter arrives, and the short version is: don’t wait.

By the time he came to us, roughly £30,000 of rental income across four tax years had gone undeclared. The tax owed on that was significant on its own. But it was the penalty, calculated as a percentage of what HMRC calls the “potential lost revenue,” that pushed the total demand past £9,000.

Why the Penalty Was Calculated the Way It Was

Failure to notify HMRC of taxable income falls into three categories: non-deliberate, deliberate, and deliberate with concealment. Almost every landlord case we see is non-deliberate; people genuinely didn’t realise letting income needed reporting, or believed a small profit margin meant nothing was owed.

For a non-deliberate failure to notify, disclosed more than 12 months after the tax was due, the penalty range runs from 20% to 30% of the potential lost revenue if HMRC prompts the disclosure. Get there first, unprompted, and the range drops to 10% to 20%, sometimes lower. That gap between prompted and unprompted is the single biggest lever available, and it’s one reason speed matters more than most people assume. We break the distinction down properly on our prompted vs unprompted disclosure page.

Why This Situation Is So Common Among Landlords

Most people picture tax evasion as something calculated. In practice, the overwhelming majority of landlord disclosures we handle look nothing like that. A few patterns come up again and again:

  • Someone inherits a property, keeps renting it out, and never thinks of themselves as running a rental “business.”
  • A homeowner relocates for work, lets their old house rather than sell it, and treats the rent as background income rather than something requiring a tax return.
  • An accidental landlord assumes that because the mortgage swallows most of the rent, there’s no profit and therefore nothing to declare, which isn’t how HMRC calculates taxable profit.
  • A property investor with several units loses track of which ones are actually registered for Self Assessment as their portfolio grows.

If any of that sounds familiar, it’s worth reading our guide on accidental landlord tax obligations before HMRC gets in touch first.

The Strategy That Brought the Penalty Down to Nil

Getting from a £9,000+ demand to a nil penalty involved three separate arguments, run in parallel rather than as a single request for leniency.

Registering Through the Let Property Campaign

The Let Property Campaign is HMRC’s disclosure route specifically for landlords with undeclared rental income. It’s not an amnesty and it doesn’t erase the tax owed, but it structures the process in a way that lets a taxpayer demonstrate cooperation from the outset, which matters enormously when penalties are calculated. Because the client had already received a nudge letter, his disclosure was classed as prompted rather than unprompted, which meant the starting penalty range was higher than it would otherwise have been. Our Let Property Campaign guide covers how registration works and what HMRC expects at each stage.

Building the Quality of Disclosure

Within the penalty calculation, HMRC allows a reduction based on three factors: telling, helping, and giving. Telling covers how much the taxpayer volunteers unprompted, before HMRC has to ask. Helping covers the level of cooperation during the process, answering questions promptly, providing records without repeated requests. Giving covers access to documents and figures, including bank statements, mortgage certificates, and letting agent statements.

Combined, these three factors can reduce a penalty by up to 70% even where the disclosure itself was prompted. We prepared a complete, well-organised disclosure package before HMRC asked for a single follow-up document, which is the part most self-filed disclosures miss. People often register for the Let Property Campaign and then respond to HMRC’s questions reactively, one letter at a time, which reads to HMRC as reluctant cooperation rather than genuine transparency.

Arguing Special Circumstances

HMRC has the power to reduce a penalty, or not charge it at all, where it considers this right because of special circumstances. This isn’t the same as a reasonable excuse defence, which applies to the underlying failure itself; special reduction applies to the penalty specifically, and HMRC has discretion over when to use it.

In this case, we presented evidence of the client’s genuine and reasonable belief that his letting agent was managing tax reporting, alongside a clean compliance history and full, proactive cooperation once the nudge letter arrived. None of that erased the tax liability. What it did was give HMRC grounds to apply special reduction on top of the quality-of-disclosure reduction already secured.

Penalty typeStandard rangeReduction applied in this case
Non-deliberate, prompted disclosure, over 12 months late20%–30% of tax owedQuality of disclosure reduction (telling, helping, giving)
Reduced rate after quality-of-disclosure reductionAs low as 10% of the reduced rangeSpecial reduction applied on top
Final penalty£9,000+ as originally issued£0

The tax due on the £30,000 of previously undeclared income was still paid in full, along with interest for late payment. That part doesn’t disappear, and no legitimate accountant will tell a client otherwise. What disappeared was the penalty sitting on top of it.

What This Case Actually Teaches Other Landlords

A few things stand out from working through cases like this one:

  • Speed changes the penalty band. A voluntary, unprompted disclosure starts from a lower base than one triggered by a nudge letter, and a nudge letter starts from a lower base than a formal HMRC enquiry.
  • The quality of the disclosure package matters as much as the disclosure itself. HMRC assesses cooperation, not just honesty.
  • Special reduction is discretionary, not automatic. HMRC won’t apply it unless the case for it is made clearly, with evidence.
  • None of this reduces the tax owed. It reduces the penalty sitting on top of the tax owed, which is a different thing entirely.

If you want a rough sense of what a penalty might look like before you speak to anyone, our penalty calculator gives a starting estimate, though the real figure depends heavily on the disclosure route and quality factors described above.

Avoiding This Situation Before HMRC Gets Involved

The cheapest way to deal with an HMRC penalty is to never trigger one. For landlords who suspect they might have gaps in their rental income reporting, whether from a single let property or a growing portfolio, a few practical steps matter more than people expect.

Get Ahead of a Nudge Letter

If you haven’t received one yet but suspect your position isn’t fully compliant, an unprompted disclosure through the Let Property Campaign is almost always cheaper than waiting. Once a letter arrives, the disclosure is classed as prompted and the penalty range moves against you.

Keep Records HMRC Would Recognise

Bank statements showing rent received, mortgage interest certificates, and invoices for allowable expenses all matter when calculating potential lost revenue accurately, rather than HMRC estimating a figure in your absence. Our guide to allowable expenses for property investors is worth reading even if you’re not currently under review, since it affects how much profit is actually taxable in the first place.

Understand Your Local HMRC Activity

HMRC compliance activity around the Let Property Campaign isn’t evenly spread across the country. We work regularly with landlords facing enquiries in Reading, Windsor, Oxford, London, and Slough, and the pattern of nudge letters we see in each area gives us a reasonably clear picture of where HMRC is currently focusing attention.

Frequently Asked Questions

Can HMRC reduce or cancel a penalty entirely?

Yes. HMRC can apply what’s called special reduction where it considers this right because of special circumstances, and this can apply on top of standard reductions for quality of disclosure. It’s discretionary rather than guaranteed, which is why the way a case is presented matters.

What’s the difference between a prompted and unprompted disclosure?

An unprompted disclosure means you told HMRC before they had any reason to suspect an issue. A prompted disclosure, such as one made after a nudge letter, starts from a higher penalty range because HMRC had already identified you as a possible risk before you came forward.

What counts as a reasonable excuse for not notifying HMRC?

HMRC recognises things like serious illness, a genuine misunderstanding of a legal obligation, or events like fire, flood or theft that prevented compliance. A vague belief that “someone else was handling it,” on its own, rarely qualifies as a reasonable excuse, though it can support an argument for special reduction if backed by evidence.

What happens if I ignore an HMRC penalty notice?

Interest continues to accrue and HMRC can escalate to enforcement action, including debt recovery. You generally have 30 days from the date of the penalty notice to appeal or challenge it, and missing that window makes the process considerably harder.

Do I need a specialist accountant for a Let Property Campaign disclosure?

You can register and disclose without one, but the penalty calculation depends heavily on how the disclosure is presented, not just what’s disclosed. An accountant experienced with HMRC’s quality-of-disclosure factors and special reduction criteria can materially change the outcome, as this case shows.

How much rental income can trigger an HMRC investigation?

There’s no fixed threshold. HMRC’s Connect system cross-references property records, mortgage data, and letting agent reports against tax filings, so even modest undeclared rental profit can surface. The safer approach is registering for Self Assessment as soon as letting income begins, regardless of the amount.

Every case is different, and penalty outcomes depend on individual circumstances, evidence, and how a disclosure is handled from the first letter onward.

Felix & Co. work with landlords and property investors across Slough, Reading, Windsor, London and Oxford on exactly this kind of disclosure.

Book a Free Consultation Call