Categories
Blogs Guides

10 Everyday Situations That Turn Into Tax Errors for Landlords

Not every landlord sets out to become one. Plenty of people end up letting a property because of a relationship change, a job relocation, an inheritance, or simply because selling felt like the wrong move at the time. The problem is that HMRC doesn’t treat “accidental” landlords any differently from professional ones — the rental income still needs to be declared, and the tax errors that follow from not realising this are some of the most common reasons Landlord Tax Mistakes end up needing the Let Property Campaign.

Below are ten real-world situations where landlords typically go wrong, and what should actually happen in each case. If you recognise your own circumstances in any of them, it’s worth acting sooner rather than later.


1. Moving In With a Partner

The situation: Someone moves into their partner’s home and decides to rent out their own property rather than sell it. Because the rent roughly covers the mortgage payment, they assume there’s nothing to tax.

Where it goes wrong: Only the interest portion of a mortgage repayment counts as an allowable expense, and even that relief is restricted to the basic rate of income tax — the capital repayment portion doesn’t count at all. Rental profit still needs to be worked out and declared, and if this has been going on for a while, the Let Property Campaign is the route to correct past years.

2. Inheriting a Property

The situation: Someone inherits a house and decides to let it rather than sell, using a local agent to manage tenants, collect rent, and handle repairs, with costs deducted before the balance is paid out.

Where it goes wrong: It’s easy to assume that because an agent is “handling everything,” there’s no personal tax obligation. In reality, the legal responsibility for declaring rental profit sits with the landlord, not the agent — regardless of how long the letting has been running. Where several years have passed undeclared, the LPC covers exactly this scenario.

3. Buying Property as an Investment

The situation: A property is bought specifically for rental income, without a clear picture of what tax obligations come with it.

Where it goes wrong: Beyond declaring the annual rental profit, investment purchases also carry a Capital Gains Tax question further down the line if the property is ever sold. Both need factoring in from the start, not worked out retrospectively once a sale is already underway.

4. Divorce or Separation

The situation: A jointly owned home is rented out rather than sold following a separation, with both parties moving into smaller properties and an agent handling the letting.

Where it goes wrong: Each party is responsible for declaring their own share of the rental profit on their individual Self Assessment return — it isn’t automatically split or handled as a joint filing, and the specific ownership split needs reflecting accurately.

5. Relocating for Work

The situation: A married couple moves to a different area for a job and lets out their previous home, without declaring the resulting rental income.

Where it goes wrong: Both partners need to declare their respective share of the rental income individually. A change of address doesn’t pause the reporting obligation — it simply adds rental income onto whatever else is already being declared.

6. Moving Into a Care Home

The situation: Someone moves into residential care and lets their own home to help cover care costs, without treating the rental income as taxable.

Where it goes wrong: It’s a common but incorrect assumption that income used to cover care fees is somehow exempt. It isn’t — rental profit is taxable regardless of what it’s ultimately spent on, and needs to be declared like any other letting.

7. Jointly Owned Investment Property

The situation: A couple jointly buys a property to renovate and let, with one partner paying tax at a higher rate than the other.

Where it goes wrong: Jointly owned lettings need careful allocation of income and allowable expenses between owners, following the correct ownership-share rules — this becomes more important, not less, when the owners sit in different tax bands.

8. Buying a Property for a Family Member at University

The situation: Parents buy a flat for their child during university, charging no rent — but the child takes in flatmates who pay rent covering more than the mortgage.

Where it goes wrong: Even where the original intention was rent-free family accommodation, rental income generated by flatmates is still taxable to whoever owns the property. PAYE employees in this position often don’t realise they now also need to report rental profit through Self Assessment.

9. Serving in the Armed Forces

The situation: Someone posted overseas rents out their UK family home to a friend, without considering how UK tax rules apply from abroad.

Where it goes wrong: This typically falls under the Non-Resident Landlord rules, and both the property owner and any joint owner need to establish their reporting obligations and declare rental profit through Self Assessment as appropriate — being posted abroad doesn’t remove the requirement.

10. Tied Accommodation

The situation: New landlords of a pub move into the flat above it as tied accommodation, then let out their own house to a family member at a rent matching their mortgage payment.

Where it goes wrong: As with the “moving in together” scenario, only the mortgage interest is an allowable expense, restricted to the basic rate — the full mortgage payment isn’t deductible. Letting to family doesn’t change the reporting requirement either, even at a modest, cost-covering rent.

Landlord Tax Mistakes

The Common Thread

Every one of these situations shares the same root cause: an assumption that a particular kind of rental arrangement — informal, family-related, agent-managed, or simply small — falls outside HMRC’s radar. None of them do. If any of these scenarios sound familiar, working out the correct rental profit and using the Let Property Campaign to disclose past years is generally the most cost-effective way to resolve it, particularly compared with waiting for HMRC to raise the question first. Our guide to voluntary disclosure sets out exactly how much that difference in timing is worth.

For a full walk through of eligibility, the disclosure process, and what to expect, our complete Let Property Campaign guide covers everything in one place, and our property tax guide is a good starting point for the underlying rules on rental income generally.

Getting It Right the First Time

Becoming a landlord, whether by choice or by circumstance, brings tax obligations that are easy to overlook and expensive to correct after the fact. If your situation matches any of the scenarios above, the safest next step is professional guidance on what needs declaring, for which years, and how to bring things up to date with the least possible cost.

10 Everyday Situations That Turn Into Tax Errors for Landlords
Book Your Comprehensive Property Tax Review

Categories
Articles Blogs FAQs Guides

The Heat is On: HMRC’s Landlord Crackdown and the Urgency of Voluntary Disclosure

HM Revenue & Customs (HMRC) has unequivocally ramped up its efforts to tackle tax non-compliance in the private rented sector (PRS). Using sophisticated data analytics, matching information from the Land Registry, local authorities, deposit schemes, and third-party platforms, HMRC is closing the net on landlords who have undeclared rental income or have underpaid tax. The Heat is On: HMRC’s Landlord Crackdown and the Urgency of Voluntary Disclosure

The message is clear: the era of ‘flying under the radar’ is over.

In this intensified compliance environment, letting agents are being called upon to play a crucial, proactive role. They are the key link between the authorities and the landlords, and they must now urge their clients with undisclosed liabilities to use the dedicated route for correction: the Let Property Campaign (LPC), a form of voluntary disclosure. Failure to do so exposes landlords to severe penalties and agents to reputational risk within an increasingly regulated industry. This article outlines the severity of the crackdown, the advantages of voluntary disclosure, and the vital steps letting agents must take immediately.

Why the Pressure on Landlords is Unprecedented

HMRC’s crackdown is underpinned by advanced data-matching technology and a focused enforcement strategy. The results speak for themselves, with the amount of unpaid tax recovered through compliance activities rising significantly year-on-year.

The Data Advantage and Increased Risk

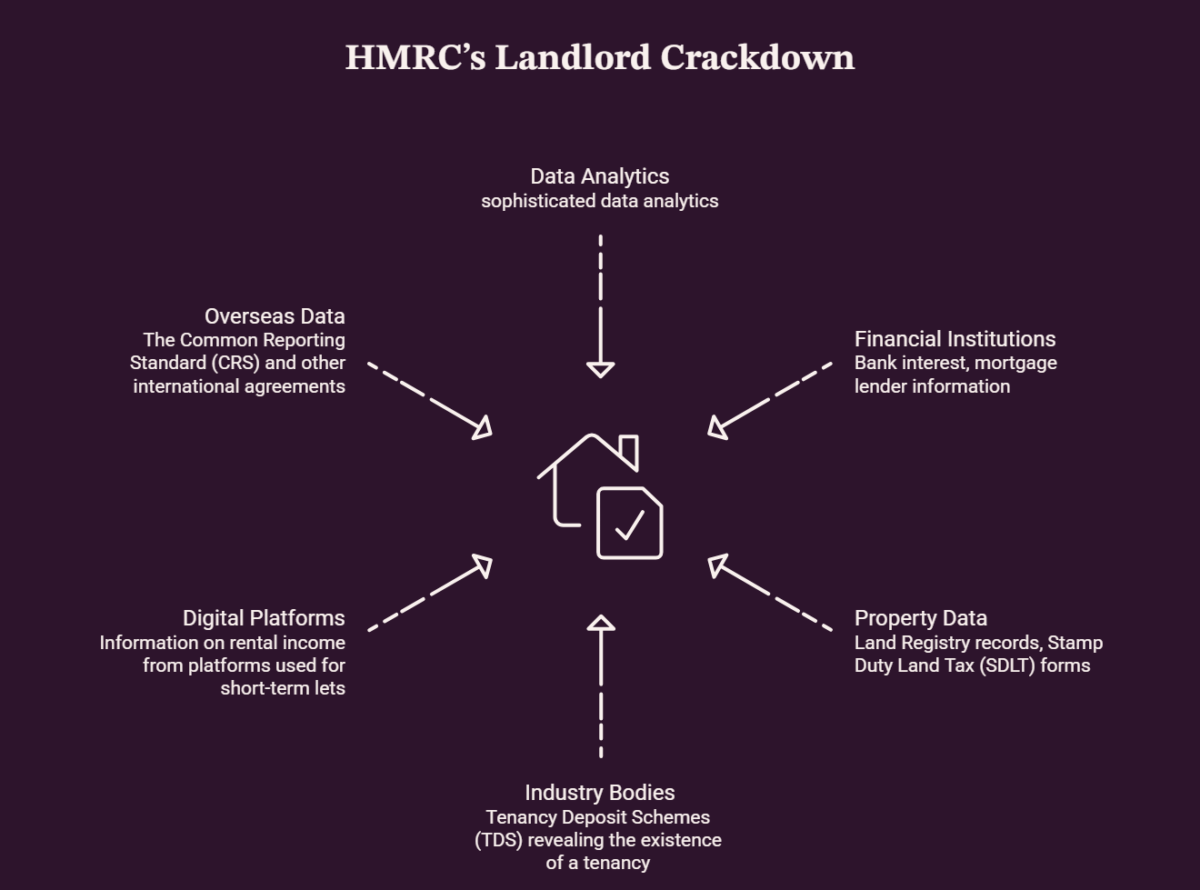
HMRC’s ability to identify non-compliant landlords has never been greater. They have the power to cross-reference data from multiple sources:

  • Financial Institutions: Bank interest, mortgage lender information.
  • Property Data: Land Registry records, Stamp Duty Land Tax (SDLT) forms.
  • Industry Bodies: Tenancy Deposit Schemes (TDS) revealing the existence of a tenancy.
  • Digital Platforms: Information on rental income from platforms used for short-term lets.
  • Overseas Data: The Common Reporting Standard (CRS) and other international agreements for landlords with offshore properties or bank accounts.

If a landlord’s tax return (or lack thereof) does not match the information HMRC holds, they will issue a ‘Nudge Letter’—a clear signal that the landlord has been identified and must take action. At this stage, the opportunity for reduced penalties through voluntary disclosure becomes more restricted.

The High Cost of Discovery vs. Disclosure

The difference in penalties for a landlord who is ‘prompted’ by HMRC (i.e., receives a letter) versus one who makes a ‘unprompted’ voluntary disclosure is vast and financially significant.

CircumstancePenalty Range (% of Unpaid Tax)Disclosure Route
Voluntary Disclosure0%–30%Let Property Campaign (LPC)
Prompted Disclosure (After ‘Nudge Letter’)20%–70%Formal Enquiry
Deliberate ConcealmentUp to 100% (or 200% for offshore income)Formal Enquiry/Prosecution

The key advantage of the LPC is the mitigation of penalties. A full, cooperative, and honest voluntary disclosure, made before HMRC’s intervention, offers the best possible terms for regularising tax affairs.

The Letting Agent’s New Role: Promoter of Compliance

Letting agents operate at the heart of the rental transaction and are in a unique position of trust and influence with their landlord clients. Their professional duty of care now extends to providing robust, general guidance on tax compliance.

Three Essential Actions for Letting Agents

Letting agents must proactively steer their clients toward compliance, not just to protect the landlord but to safeguard their own professional reputation and adhere to their professional bodies’ standards.

  1. Integrate Tax Awareness into Onboarding:
    • Mandate of Disclosure: Ensure all new landlord agreements explicitly state that the landlord is responsible for declaring all rental income to HMRC.
    • General Advisory: Provide a generic, written warning (disclaimer) in welcome packs or management contracts about the requirement to declare income and the penalties for non-compliance, directing them to the LPC. Crucially, agents should not offer specific tax advice, only general guidance to seek professional counsel.
  2. Actively Promote the Let Property Campaign (LPC):
    • Client Communication: Issue a targeted communication campaign to all existing landlords, highlighting HMRC’s crackdown data and the financial benefits of the LPC.
    • Referral Network: Establish relationships with specialist tax advisors who can handle LPC disclosures, providing a professional and safe pathway for clients.
  3. Maintain Meticulous Records:
    • Data Readiness: Agents should assume that HMRC will eventually ask for their complete records. Ensure all transactional data—rent received, expenses paid, start/end dates of tenancies—is accurate and readily available. This protects the agent and helps the landlord with their disclosure.

Addressing Common Landlord Misconceptions

Many landlords fall into non-compliance not through deliberate evasion, but through ignorance or simple oversight. Agents must address these common points:

  • ‘Accidental Landlords’: The myth that renting out a single inherited property or one that couldn’t be sold is not ‘commercial’ and therefore doesn’t need to be declared. All rental income must be declared.
  • ‘Zero Profit’: The belief that because allowable expenses (like mortgage interest) reduce profit to zero, there is no need to file a tax return. The income must still be reported on a Self Assessment tax return.
  • The Agent Reports It: The mistaken belief that the letting agent is responsible for reporting the rental income to HMRC. The legal responsibility always rests with the individual landlord.

Navigating the Let Property Campaign (LPC) for a Client

For any landlord who has undeclared rental income from UK or overseas residential property, the LPC is the formal path to resolution. Agents should guide clients through the process:

  1. Notification: The landlord (or their tax advisor) must notify HMRC of their intention to disclose using the online Digital Disclosure Service (DDS). HMRC will then issue a Disclosure Reference Number (DRN).
  2. Calculation: The landlord has 90 days from the date of the DRN to calculate the full undeclared income, allowable expenses, and the resultant unpaid tax for all relevant years. The period covered can be up to 20 years if the error was deliberate, but often less for careless mistakes (up to 6 years) or genuine errors (up to 4 years).
  3. Disclosure & Payment: The full disclosure form and payment of the tax, interest, and calculated penalty must be submitted within the 90-day window.

    HM Revenue & Customs (HMRC)
    Voluntary Disclosure

By pushing for the LPC now, letting agents help their clients avoid a future costly, stressful, and potentially public formal investigation by HMRC, reinforcing the agent’s position as a trustworthy and compliant partner in property management.

Frequently Asked Questions (FAQs) for Landlord Voluntary Disclosure

What is the HMRC Let Property Campaign (LPC)?

The LPC is a voluntary disclosure initiative by HMRC that encourages individual landlords (who own residential property in the UK or abroad) to ‘come clean’ about undeclared or underpaid rental income on the best possible penalty terms.

How far back must a landlord disclose under the LPC?

The disclosure period depends on the landlord’s behaviour:

  • 4 years for genuine mistakes (reasonable care taken).
  • 6 years for careless errors.
  • Up to 20 years for deliberate tax evasion or concealment.

What are the penalties if HMRC finds undeclared income before I disclose?

If HMRC discovers the unpaid tax before the landlord makes a disclosure (known as a ‘prompted’ disclosure), the penalty is significantly higher, typically ranging from 20% to 70% of the tax due, and up to 100% or more for deliberate offshore non-compliance. Voluntary disclosure offers much lower, often zero, penalties for unprompted, cooperative disclosures.

Can a letting agent give me tax advice for the LPC?

No. Letting agents are not qualified or regulated to provide specific tax advice. Their role is to provide general guidance about compliance and strongly urge the landlord to seek specialist advice from a qualified accountant or tax solicitor to handle the complex LPC submission.

Does the LPC cover commercial properties or undeclared business income?

No. The LPC is specifically for income from residential property lettings. Disclosures for commercial property or other types of undeclared income must be made through HMRC’s general Digital Disclosure Service (DDS).

What is a ‘Nudge Letter,’ and how should a landlord respond?

A ‘Nudge Letter’ is a communication from HMRC informing a landlord that their data suggests they have undeclared rental income. This counts as a prompted intervention. A landlord should immediately seek professional tax advice, as the penalties will be higher than a truly unprompted voluntary disclosure, but action is essential to avoid a full, much more severe investigation.

Learn More


Categories
FAQs Guides News

The Benefits of Outsourcing Accounting Services for Property Investors

In the dynamic world of property investment, time is money. As a property investor, your focus should be on identifying lucrative opportunities and growing your portfolio, not getting bogged down by the complexities of accounting. Outsourcing your accounting needs to a professional accounting firm in the UK can be a game-changer, providing you with expert support, ensuring compliance, and delivering significant cost savings for investors.

Why Outsourced Accounting is a Smart Move for Property Investors

Imagine you’re juggling multiple properties across different regions. Each property comes with its own set of financial records, tax obligations, and regulatory requirements. Managing all this can feel like trying to navigate a maze blindfolded. That’s where outsourced accounting for property investors comes into play, acting as your guiding light through the financial labyrinth.

1. Access to Expert Knowledge and Experience

Outsourcing connects you with professionals who specialize in accounting services in the UK, particularly tailored for property investors and SMEs.

  • Specialized Expertise: These professionals understand the intricacies of property taxation, capital gains, and VAT implications.
  • Up-to-Date Compliance: They stay abreast of the latest tax laws and regulations, ensuring you remain compliant with HMRC requirements.

Real-Life Example: Sarah, a property investor in London, found herself overwhelmed by tax complexities. By outsourcing to a professional firm, she not only remained compliant but also discovered tax relief opportunities she wasn’t aware of, saving her thousands of pounds.

2. Significant Cost Savings for Investors

While it might seem counterintuitive, outsourcing can lead to substantial cost reductions.

  • Eliminate Overheads: No need to hire full-time, in-house accountants, saving on salaries, benefits, and training costs.
  • Avoid Costly Mistakes: Professionals help prevent errors that could result in fines or missed deductions.

Statistic: According to a study by Deloitte, businesses can save up to 40% on operational costs by outsourcing accounting functions.

3. Enhanced Focus on Core Investment Activities

Time spent on accounting is time taken away from expanding your investment portfolio.

  • Efficiency Boost: Free up your schedule to focus on market research, property acquisitions, and networking.
  • Peace of Mind: With experts handling your finances, you can invest with confidence, knowing your accounting is in good hands.

Analogy: Think of outsourcing as hiring a seasoned captain for your ship, allowing you to chart new territories without worrying about navigating stormy seas.

4. Access to Advanced Technology and Systems

Professional accounting firms utilize cutting-edge software and systems.

  • Real-Time Financial Reporting: Gain access to up-to-date financial information anytime, anywhere.
  • Data Security: Robust systems ensure your sensitive financial data is protected against breaches.

Expert Insight: John Miller, a senior accountant at a leading professional accounting firm in the UK, notes, “Our clients benefit from sophisticated accounting platforms that offer insights and analytics not typically available in-house.”

5. Scalability and Flexibility

As your property portfolio grows, your accounting needs will evolve.

  • Adaptable Services: Outsourced firms can easily scale their services to match your growth.
  • Customized Solutions: Receive tailored SME accounting solutions that fit your specific requirements.

6. Improved Compliance and Reduced Risk

Navigating tax laws and regulations can be daunting.

  • Regulatory Compliance: Professionals ensure all filings are accurate and submitted on time.
  • Audit Support: In the event of an HMRC audit, your outsourced team can provide necessary documentation and representation.

Case Study: When David’s property company faced an unexpected audit, his outsourced accounting firm managed the process smoothly, resulting in a clean bill of health from HMRC.

Addressing Common Concerns About Outsourcing

“Won’t I lose control over my finances?”

Outsourcing doesn’t mean relinquishing control; it means partnering with experts.

  • Transparency: Reputable firms provide regular reports and maintain open communication.
  • Collaboration: You remain involved in decision-making processes, with the added benefit of expert advice.

“Is outsourcing only for large companies?”

Not at all. SME accounting solutions are specifically designed to support small and medium-sized enterprises, including individual property investors.

How to Choose the Right Professional Accounting Firm in the UK

Selecting the right partner is crucial.

  • Experience with Property Investors: Ensure the firm has a proven track record in the property sector.
  • Comprehensive Services: Look for firms offering a full suite of services, from bookkeeping to strategic financial planning.
  • Client Testimonials: Seek out reviews or speak to other investors about their experiences.

Tip: Schedule a consultation to discuss your needs and gauge the firm’s understanding and responsiveness.

The Long-Term Benefits of Outsourced Accounting

Beyond immediate cost savings and efficiency gains, outsourcing offers long-term advantages.

  • Strategic Financial Planning: Experts can help you plan for growth, investment diversification, and retirement.
  • Tax Optimization: Ongoing advice ensures you’re taking advantage of all available tax benefits.
  • Business Continuity: With a dedicated team managing your finances, there’s no disruption due to staff turnover or absence.

Analogy: Outsourcing is like having a co-pilot who not only helps navigate but also plans the journey ahead, ensuring you reach your destination smoothly.

Empower Your Property Investment Journey

Outsourcing your accounting needs is more than a tactical move; it’s a strategic decision that can propel your property investment business to new heights. By leveraging the expertise of a professional accounting firm in the UK, you unlock benefits that extend far beyond number-crunching.

Take the Next Step Towards Financial Excellence

Don’t let accounting challenges hinder your investment success. Contact us today to discover how our tailored accounting services in the UK can support your property investment goals.

Frequently Asked Questions

1. What are the main benefits of outsourcing accounting for property investors?

Answer: Outsourcing provides access to expert knowledge, significant cost savings, enhanced focus on core investment activities, advanced technology, scalability, improved compliance, and reduced risk.

2. How can outsourcing lead to cost savings for investors?

Answer: By eliminating the need for in-house accounting staff, you save on salaries, benefits, and training. Outsourcing also helps avoid costly mistakes and ensures all tax deductions are maximized.

3. Is outsourcing accounting services suitable for small property investors?

Answer: Yes, outsourcing offers SME accounting solutions tailored to the needs of small and medium-sized property investors, providing expert support without the overhead of an in-house team.

4. Will I lose control over my financial decisions if I outsource?

Answer: No, you remain in control of your finances. Outsourced firms work collaboratively with you, providing transparency and regular updates to inform your decisions.

5. How do I choose the right professional accounting firm in the UK?

Answer: Look for firms with experience in the property sector, a comprehensive range of services, positive client testimonials, and a responsive, communicative approach.

6. Can outsourcing help with tax compliance and avoiding penalties?

Answer: Absolutely. Professional accountants stay updated on tax laws, ensuring compliance with HMRC regulations and helping you avoid fines or legal issues.

7. What services do outsourced accounting firms typically offer?

Answer: Services often include bookkeeping, tax planning, financial reporting, payroll management, VAT returns, and strategic financial advice.

8. How does outsourcing accounting enhance my focus on investment activities?

Answer: By handling time-consuming accounting tasks, outsourcing frees up your time to focus on identifying new investment opportunities and growing your portfolio.

9. Are my financial data and information secure with an outsourced firm?

Answer: Reputable firms implement robust data security measures to protect your sensitive financial information from breaches or unauthorized access.

10. Can outsourced accounting services scale with my business growth?

Answer: Yes, outsourced services are flexible and can easily adapt to your changing needs as your property investment portfolio expands.

Categories
Articles Blogs FAQs Guides

How to Reduce Property Tax Legally: A UK Landlord’s Guide for 2026

Every UK landlord pays property tax somewhere along the way. It shows up when you buy, when you let, and again when you sell.

The good news: HMRC offers real reliefs and allowances. Used correctly, they cut your bill without breaking a single rule.

This guide covers the legitimate strategies that actually work in 2026, from allowable expenses to Capital Gains Tax planning.

Claim Every Allowable Expense

The simplest way to reduce property tax is also the most overlooked. Many landlords miss deductions they are fully entitled to claim.

An expense qualifies if it is incurred wholly and exclusively for letting the property. Common allowable costs include:

  • Letting agent and management fees
  • Landlord insurance and accountancy fees
  • Repairs and maintenance that restore, not improve, the property
  • Ground rent, service charges, and council tax paid by the landlord
  • Marketing, advertising, and property-related travel

Improvements, like a loft conversion or a new kitchen extension, do not count as a running cost. Keep those receipts anyway. They can reduce Capital Gains Tax when you eventually sell.

Use the Property Income Allowance

Landlords with modest rental income can claim a flat £1,000 property income allowance instead of itemizing expenses. This works well for a single room or a low-cost let, where actual expenses fall below that figure.

You cannot claim both the allowance and itemised expenses on the same income. Compare both routes each year and pick whichever produces the lower tax bill.

Understand the Mortgage Interest Restriction

Since April 2020, individual landlords cannot deduct mortgage interest directly from rental income. Instead, they receive a 20% basic-rate tax credit on finance costs.

This rule, often called Section 24, pushes many landlords into a higher tax band than their true cash profit suggests. It applies to individuals, not to limited companies, which explains why incorporation has become popular for larger portfolios.

Pension contributions offer one legal workaround. Contributing to a pension reduces your adjusted net income, which can pull your rental profit back under the higher-rate threshold.

Rental Profit Tax Treatment: Individual vs Limited Company

StructureMortgage Interest TreatmentTax on Profit
Individual landlord20% tax credit onlyIncome Tax up to 45%
Limited companyFully deductibleCorporation Tax 19%–25%

Portfolio size and personal tax rate decide which structure saves more overall.

Split Ownership With a Spouse or Civil Partner

Married couples and civil partners can transfer property ownership, or a share of it, between themselves without triggering Capital Gains Tax or Stamp Duty on the transfer itself.

Using a Deed of Trust alongside HMRC’s Form 17, couples can allocate rental income toward whichever partner pays the lower tax rate. This uses two personal allowances and two basic-rate bands instead of one.

![Suggested image: An illustration of a house split between two overlapping circles representing joint ownership, minimal flat design]

Plan Capital Gains Tax Before You Sell

Selling a rental property can trigger Capital Gains Tax on the increase in value since purchase. A few legal strategies reduce that bill.

  • Use your annual exempt amount. Individuals get a £3,000 tax-free allowance each year, and it cannot be carried forward.
  • Transfer assets to a spouse first. Transfers between spouses are tax-free, effectively doubling the exempt amount to £6,000 before a joint sale.
  • Time the disposal. Splitting a sale across two tax years can use two separate annual exemptions.
  • Offset losses. Capital losses from other assets can reduce a taxable property gain in the same year.
  • Claim Private Residence Relief. If the property was ever your main home, part of the gain may be exempt.

Current CGT rates on residential property sit at 18% for basic-rate taxpayers and 24% for higher and additional-rate taxpayers.

Consider the Rent a Room Scheme

If you let a furnished room in your own home, the Rent a Room Scheme lets you earn up to £7,500 a year completely tax-free. No expense claims are needed, since the allowance already covers your costs.

Compare this against claiming actual expenses if your costs regularly exceed the scheme’s threshold.

Claim Replacement of Domestic Items Relief

Landlords who replace furniture, appliances, or furnishings in a let property can deduct the cost of a like-for-like replacement from rental income. This relief applies even though buying the original item would not have qualified.

Keep receipts for both the old and new item to support your claim if HMRC ever asks questions.

Stay Compliant With Making Tax Digital

From April 2026, landlords with combined property and self-employment income over £50,000 must follow Making Tax Digital for Income Tax rules. This means quarterly digital updates instead of one annual tax return.

Staying compliant matters here for a simple reason: legitimate property tax reduction depends on accurate, well-documented records. Digital software makes it far easier to track allowable expenses as they happen, rather than reconstructing them months later.

Frequently Asked Questions

Can I deduct mortgage interest from rental income?

Not directly. Since April 2020, individual landlords receive a 20% basic-rate tax credit on mortgage interest instead of a direct deduction. This can push rental profit into a higher tax band than actual cash profit suggests. Limited companies still deduct finance costs in full, which is why many larger portfolios incorporate.

What expenses can landlords claim against tax?

Landlords can claim letting agent fees, insurance, accountancy costs, repairs, ground rent, service charges, and property-related travel. Expenses must be incurred wholly and exclusively for letting the property. Capital improvements, like an extension, don’t qualify as running costs but can reduce Capital Gains Tax on a future sale.

How does the property income allowance work?

The £1,000 property income allowance lets landlords deduct a flat amount instead of itemizing expenses. It suits landlords with low running costs, such as a single let room. You cannot claim both the allowance and actual expenses on the same rental income in one tax year.

Can I transfer property to my spouse to reduce tax?

Yes. Transfers between spouses and civil partners are exempt from Capital Gains Tax and Stamp Duty. Combined with a Deed of Trust and Form 17, couples can allocate rental income to the lower-earning partner, reducing the household’s overall property tax bill legally and effectively.

How much is Capital Gains Tax on selling a rental property?

Individuals pay 18% Capital Gains Tax on gains within the basic-rate band, and 24% above it, after the £3,000 annual exempt amount. Transferring part ownership to a spouse before sale, or splitting a disposal across tax years, can legally reduce the final property tax bill.

Is buying property through a limited company more tax efficient?

Often, yes, for higher-rate taxpayers and larger portfolios. Limited companies pay Corporation Tax at 19%–25% and deduct mortgage interest in full, unlike individual landlords. Smaller portfolios and basic-rate taxpayers may find personal ownership simpler once mortgage and admin costs are considered.

What is the Rent a Room Scheme?

The Rent a Room Scheme lets homeowners earn up to £7,500 a year tax-free from letting a furnished room in their own home. No expense claims are required, since the allowance already accounts for running costs. It only applies to your main residence, not a separate rental property.

Do I need to register for Making Tax Digital as a landlord?

From April 2026, landlords with combined property and self-employment income above £50,000 must follow Making Tax Digital for Income Tax, filing quarterly digital updates. The threshold drops to £30,000 in April 2027. Limited company landlords are not affected by this rule at this stage.

How to Reduce Property Tax Legally: A UK Landlord’s Guide for 2026
Book Your Comprehensive Property Tax Review


Categories
Articles Blogs FAQs Guides

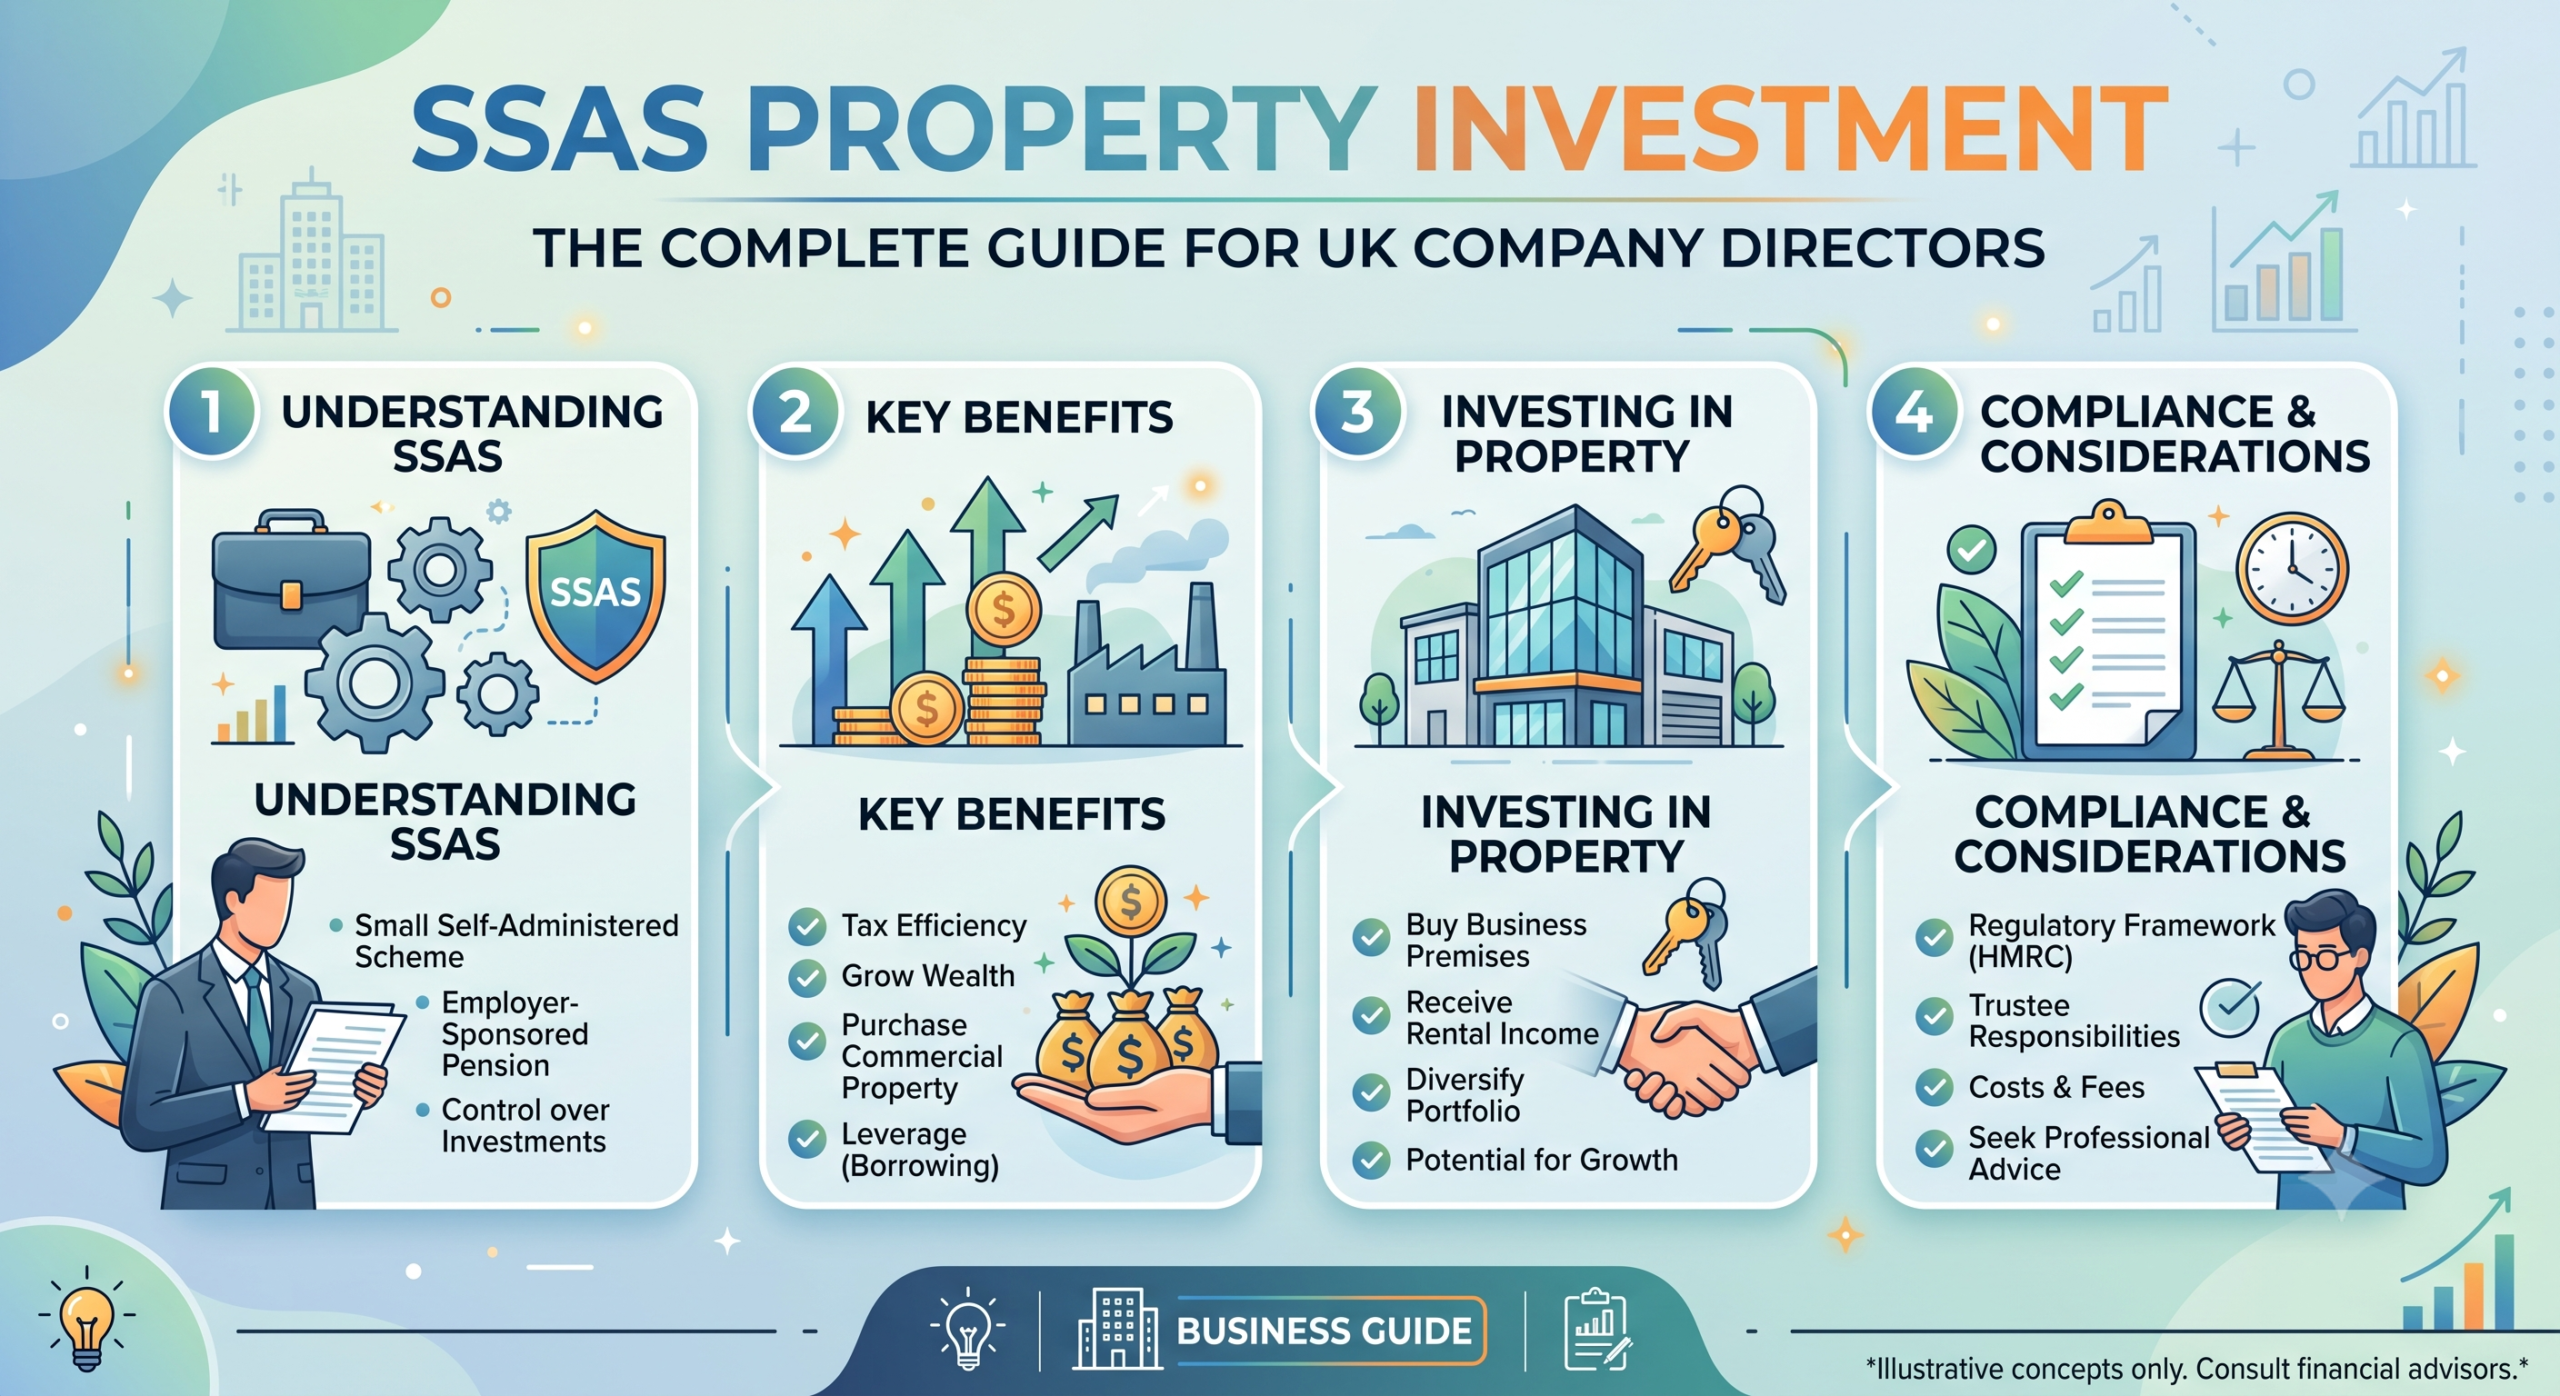
SSAS Property Investment: The Complete Guide for UK Company Directors

If you run a limited company, SSAS property investment lets you buy commercial premises through your own pension scheme. Rent flows into your pension, not a landlord’s pocket. Growth builds up tax-free. You keep control over every decision.

This guide breaks down how it works, what HMRC allows, and where directors get it wrong.

What Is a SSAS Pension?

A Small Self-Administered Scheme (SSAS) is an occupational pension trust. A limited company sets it up for its directors, senior staff, and sometimes family members.

Unlike a workplace pension, a SSAS gives members direct control. Members usually act as trustees too. That means you decide where the money goes.

This control is the whole point of SSAS property investment. A standard pension hands you a fund menu. A SSAS lets you buy an actual building.

How SSAS Property Investment Works

Trustees can use scheme funds, plus borrowing, to purchase premises. The company can then lease that property back from the pension.

Three features make this strategy work:

  • Rental income lands in the pension tax-free
  • Growth on the property is free of Capital Gains Tax
  • Contributions attract Corporation Tax relief for the company

The result is a building your business uses, sitting inside a tax-efficient wrapper.

The Commercial-Only Rule

HMRC only allows commercial property inside a SSAS. This includes offices, warehouses, retail units, factories, and land with planning permission for commercial use.

Residential property is banned. Direct ownership of a house, flat, or buy-to-let triggers an unauthorised payment charge. That penalty runs as high as 55%.

There is one narrow exception. A residential unit tied to a commercial use, like a flat above a shop occupied by staff, may qualify. The rules here are strict, and the flat’s occupant cannot be connected to any SSAS member.

How Much Can a SSAS Borrow?

Trustees can borrow up to 50% of the scheme’s net asset value. Lenders typically secure this as a commercial mortgage against the property itself.

SSAS Net AssetsMaximum Borrowing (50%)Total Buying Power
£400,000£200,000£600,000
£600,000£300,000£900,000
£1,000,000£500,000£1,500,000

This borrowing limit gets tested once, at the point the loan is taken out. It does not get retested if property values later fall.

SSAS vs SIPP for Property Investment

Both a SSAS and a SIPP (Self-Invested Personal Pension) can hold commercial property. The two structures differ in important ways.

FeatureSSASSIPP
Who can joinCompany directors and familyAny individual
Trustee controlMembers are usually trusteesProvider acts as trustee
Pooling fundsMultiple members can pool pensionsCannot pool with others
Loan to sponsoring companyYes, up to 50% of net assetsNot permitted

The loan back facility is the biggest difference. It lets a SSAS lend money directly to the business that set it up, something a SIPP cannot do.

Tax Benefits of SSAS Property Investment

Directors choose SSAS property investment because the tax treatment beats owning property personally or through the trading company.

  • No Income Tax on rent. Rental payments from the tenant company go straight into the pension.
  • No Capital Gains Tax. Selling the property inside the scheme creates no CGT liability.
  • Corporation Tax relief. Employer contributions into the SSAS reduce the company’s taxable profit.
  • Asset protection. The property sits outside the trading company, away from business creditors.

These benefits only apply while the scheme follows HMRC’s rules exactly.

Risks and Compliance Traps

A SSAS rewards careful trustees. It punishes careless ones.

Unauthorized payments. Buying residential property, letting a member use scheme assets personally, or breaching connected-party rules all trigger tax charges.

Trading vs investment. Holding one commercial unit for rental income counts as investment. Buying, developing, and flipping properties on rotation can look like trading. HMRC treats trading activity differently, and it can lose its tax-free status.

Concentration risk. Tying most of your pension into one building leaves your retirement fund exposed if the tenant company struggles.

Valuation and lease terms. Rent must be set at an independent, arm’s-length market rate. An artificially low rent can also count as an unauthorized payment.

How to Set Up a SSAS for Property Investment

  1. Appoint a professional trustee. Most schemes need a qualified SSAS practitioner alongside the member trustees.
  2. Register the scheme with HMRC. The SSAS becomes a registered pension scheme once approved.
  3. Transfer or contribute funds. Members can transfer old pensions in, and the company can make contributions.
  4. Instruct a solicitor and surveyor. Property purchases need an independent valuation and full legal searches.
  5. Agree a formal lease. The company signs a commercial lease with the SSAS at market rent.

A Simple Example

Sarah transfers £400,000 from old pensions into a SSAS. Her company adds £100,000 as an employer contribution, gaining Corporation Tax relief.

The scheme now holds £500,000 in cash. Trustees buy a freehold office building outright, with no borrowing needed.

The company signs a lease at £36,000 a year in rent. That rent flows into Sarah’s pension tax-free, growing her retirement fund while her business gets a permanent home.

Is SSAS Property Investment Right for You?

This route suits company directors who:

  • Own or lease commercial premises already
  • Want long-term control over pension investments
  • Have enough pension value to make property purchase practical
  • Are comfortable taking professional trustee advice

It suits fewer people who need short-term access to their pension fund, since property is an illiquid asset.

Frequently Asked Questions

Can a SSAS buy residential property?

No, not directly. HMRC bans SSAS schemes from holding residential property, and doing so triggers an unauthorised payment charge. There are narrow exceptions, such as staff accommodation tied to a commercial building. SSAS property investment stays restricted to commercial premises, land, and specific mixed-use arrangements approved under HMRC rules.

How much can a SSAS pension borrow?

A SSAS can borrow up to 50% of its net asset value at the date the loan is made. A scheme worth £600,000 can therefore borrow £300,000, giving £900,000 of buying power. This limit gets tested once, not retested if property values fall later.

Is a SSAS a good idea for property investment?

For company directors with sufficient pension value, SSAS property investment can be tax-efficient and flexible. Rent and growth build up tax-free, and trustees control every decision. It suits long-term investors comfortable with an illiquid asset, but it needs proper professional advice before setup.

How does a SSAS pension work?

A limited company establishes the SSAS as a trust for its directors and senior staff. Members typically act as trustees, giving them direct control over investment decisions, including SSAS property purchases, employer loanbacks, and other permitted assets, all within strict HMRC pension rules.

What is the difference between a SSAS and a SIPP?

A SSAS is set up by a company for multiple members, who usually act as trustees and can pool funds together. A SIPP is an individual pension. Only a SSAS can lend money back to its sponsoring company, making it the preferred structure for SSAS property strategies among business owners.

Can a SSAS lend money to a company?

Yes. A SSAS can lend up to 50% of its net asset value back to the sponsoring employer. The loan needs a first legal charge over an asset of equal value, a maximum five-year term, and interest at at least 1% above average bank base rates.

What type of commercial property can a SSAS hold?

A SSAS can hold offices, factories, warehouses, retail units, hotels, pubs, and commercial land, including development sites with the right planning permission. Direct residential property remains prohibited under HMRC’s investment-regulated pension scheme rules, keeping SSAS property investment firmly commercial in scope.

What happens if a SSAS breaks the residential property rules?

Breaching the rules creates an unauthorized payment. HMRC can charge tax of up to 55% on the value involved, alongside a possible scheme sanction charge. This makes professional trustee oversight essential for any SSAS property purchase, especially where a property has mixed commercial and residential use.

SSAS Property Investment: The Complete Guide for UK Company DirectorsBook Your Comprehensive Property Tax Review


Categories
Articles Blogs FAQs Guides

Property Investment Through a Limited Company: The Complete UK Guide

More UK landlords now buy through a limited company than at any point before. Mortgage interest rules changed. Personal tax rates climbed. A company structure started to look far more attractive.

This guide walks through the tax benefits, the real costs, and how to decide if incorporation suits your portfolio.

Why Landlords Choose a Limited Company

A limited company is a separate legal entity. It owns the property, not you personally. Profits get taxed under Corporation Tax rules instead of Income Tax.

For higher-rate taxpayers, this shift matters. Companies pay Corporation Tax at 19% on profits up to £50,000, and 25% on profits over £250,000, with a tapered rate in between. Personal Income Tax on rental profit can reach 45%.

Company ownership also protects your personal assets. Because a limited company is a separate legal entity, any liabilities linked to the property fall on the company, not on you as director or shareholder.

Tax Benefits of Buying Property Through a Limited Company

Three tax advantages drive most incorporation decisions.

  • Lower tax on profits. Corporation Tax rates sit below higher and additional Income Tax bands.
  • Full mortgage interest relief. Companies can still deduct finance costs, including mortgage interest, from rental profits in full, unlike individual landlords.
  • Flexible profit extraction. Profit can stay inside the company until you need it, rather than being taxed the year you earn it personally.

These benefits compound as your portfolio grows, which is why incorporation appeals most to landlords planning to scale.

The Real Costs and Disadvantages

Nothing here comes free. A limited company structure carries extra costs that shrink or eliminate the tax gain for some landlords.

Higher Mortgage Costs

Lenders view limited companies as riskier borrowers than individual homeowners because of their reduced personal liability. Expect fewer lender choices and slightly higher rates.

Administrative Burden

Running a limited company means filing accurate accounting records, annual accounts, tax returns, and sometimes holding formal meetings. Most landlords pay an accountant to manage this.

Stamp Duty on Transfers

Incorporating an existing portfolio triggers Stamp Duty Land Tax, calculated on market value regardless of whether cash actually changes hands.

Transferring an Existing Buy-to-Let Into a Limited Company

Moving property you already own into a company counts as a sale in HMRC’s eyes, even between you and your own business.

TaxWhat Happens on Transfer
Stamp Duty Land TaxCharged on the property’s market value, not the price actually paid, even where no money changes hands
Capital Gains TaxTreated as a disposal at market value, so any gain since purchase can trigger a CGT bill
Incorporation ReliefCan defer both SDLT and CGT, but HMRC generally expects around 20 hours a week of active property management to qualify

Because both taxes hit at once, transferring an existing portfolio needs careful modelling before you commit.

Getting a Mortgage as a Limited Company

Company mortgages, often called SPV (Special Purpose Vehicle) mortgages, work differently to personal buy-to-let loans.

Lenders assess the company’s rental income, your personal guarantee, and your track record as a director. Rates run slightly higher than personal buy-to-let deals, and the lender pool is smaller.

Most brokers recommend setting up a company limited by shares, with a SIC code that clearly states property investment as the business activity.

How to Set Up a Limited Company for Property Investment

  1. Register with Companies House. Choose a name, a registered address, and a property-related SIC code.
  2. Appoint directors and shareholders. One person can hold both roles.
  3. Open a business bank account. Keep company and personal finances fully separate.
  4. Arrange a company mortgage. Speak to a specialist broker who deals with SPV lenders.
  5. Instruct an accountant. Corporation Tax, VAT thresholds, and annual filings need ongoing management.

Is a Limited Company Right for Your Portfolio?

A limited company structure tends to suit:

  • Higher and additional-rate taxpayers
  • Landlords planning to grow beyond one or two properties
  • Investors who plan to reinvest profit rather than draw it out immediately
  • Anyone prioritising limited liability protection

Basic-rate taxpayers with a single investment property often find direct personal ownership simpler and cheaper overall. Portfolio size and your personal tax rate decide which route wins.

Frequently Asked Questions

Is it worth buying property through a limited company?

It depends on your tax rate and portfolio size. Higher-rate taxpayers and landlords planning multiple properties usually benefit most from limited company property investment, thanks to lower Corporation Tax rates and full mortgage interest relief. Basic-rate taxpayers with one property often find personal ownership simpler and cheaper.

What are the tax benefits of buying property through a limited company?

A limited company pays Corporation Tax on rental profit instead of Income Tax, and rates sit lower than higher personal tax bands. Companies also deduct full mortgage interest from profits, and can retain earnings inside the business rather than paying personal tax immediately on every pound earned.

Can I transfer my buy-to-let property into a limited company?

Yes, but HMRC treats the move as a sale at market value. This can trigger Stamp Duty Land Tax and Capital Gains Tax at the same time, even though the same person effectively still owns the asset. Model both costs carefully before transferring an existing limited company portfolio.

Do I pay stamp duty when transferring property to a limited company?

Usually, yes. Stamp Duty Land Tax applies to the property’s market value on transfer, regardless of the price paid or whether cash changes hands at all. Larger portfolios can face substantial SDLT bills, making professional advice essential before any limited company transfer.

How much corporation tax do I pay on rental income?

Companies pay 19% Corporation Tax on profits up to £50,000, rising to 25% on profits above £250,000, with a tapered rate between the two thresholds. This structure often beats personal Income Tax rates for higher earners running limited company property investment.

What are the disadvantages of buying property through a limited company?

Limited companies face higher mortgage rates, a smaller pool of lenders, and ongoing administrative costs like annual accounts and Corporation Tax filings. Stamp duty on transfers and less favourable lending terms can offset tax savings for smaller, lower-rate landlords.

Can I get a mortgage as a limited company?

Yes, through specialist SPV (Special Purpose Vehicle) mortgage products designed for limited company property investment. Lenders assess the company’s projected rental income alongside a personal guarantee from directors. Expect slightly higher rates and fewer lender options than standard personal buy-to-let mortgages.

Do I pay Capital Gains Tax when transferring property into a company?

Generally, yes. HMRC treats the transfer as a disposal at market value, so any increase in the property’s value since purchase can create a Capital Gains Tax bill. Incorporation Relief may defer this for active property businesses meeting strict HMRC conditions.

Property Investment Through a Limited Company: The Complete UK Guide Book Your Comprehensive Property Tax Review
Categories
Articles Blogs FAQs Guides

Stop Letting Messy Bookkeeping Bleed Your Property Profits

Accurate and complete record keeping is the foundation of financial health for any real estate business. When managing rentals, tracking numbers carelessly leads to regulatory non-compliance, missed tax deductions, and stressful tax seasons.

Property investors must manage multiple financial and operational timelines simultaneously. Missing gas safety certificate renewals, insurance end dates, or mortgage fixed-term expirations creates major operational liabilities. Establishing a dedicated property system keeps these moving parts under strict control.

Without a centralized, organized way to track your incoming rent and outbound expenses, calculating true net profitability becomes guesswork.

Three Costly Results of Messy Bookkeeping record keeping

1. Compliance Penalties and Audits

Inadequate record keeping causes errors or omissions on your self-assessment tax returns. If HMRC initiates an inquiry into your property affairs, missing supporting documents can result in substantial fines.

2. Overlooked Expenses and High Tax Bills

Without meticulous documentation, you will overlook allowable deductions like minor maintenance work, insurance, or letting agent fees. Missing an allowable expense artificially inflates your reported net profit, which increases your overall tax bill and reduces your net cash flow.

3. Frozen Decision Making

Vague financial data prevents you from analyzing your real-world portfolio performance. You cannot easily spot properties with high maintenance costs, evaluate current rental yields, or confidently secure financing for your next acquisition.

Risk CategoryImpact of Poor BookkeepingResolution via Automated System
HMRC ComplianceFinancial fines, penalties, and stressful multi-year auditsAutomated digital trails with uploaded receipts
Tax OptimizationMissing allowable expenses, which increases tax liabilityReal-time expense logging categorized by property
Portfolio MetricsBlind decision-making and inaccurate cash flow trackingInstant yield, profit, and loss reporting dashboards

Strategies to Modernize Your Property System

Utilize Dedicated Software

Generic spreadsheets quickly fail as you scale. Cloud accounting tools like Xero or QuickBooks let you link bank feeds directly, log outbound expenses instantly, and export clean reports directly to your accountant. For specialized portfolio management, dedicated property platforms like Lendlord help consolidate tenant records and key certificate dates in one hub.

Consistent Bank Reconciliation

Reconcile your corporate bank accounts, incoming rental slips, and property expenses weekly. Frequent reviews help catch transaction anomalies, banking errors, or late tenant payments before they affect your liquidity.

Keep Every Piece of Documentation

Maintain a secure digital archive of all vendor receipts, contractor invoices, letting agreements, and finance documents. Cloud storage options make it simple to snap photos of receipts immediately, ensuring you always have clear audit trails.

1.Separate Bank Accounts:

Day 1.

Open a dedicated business bank account solely for property transactions to eliminate mixed personal spending.

2.Migrate to Cloud Software:

Day 2 – 5.

Set up a profile on Xero, QuickBooks, or Lendlord and link your dedicated property bank feed.

3.Digitalize Physical Receipts:

Day 6.

Scan your paper receipts using a mobile scanning app and attach them directly to historical transactions.

4.Schedule Reconciliation Reviews:

Monthly.

Block out the first Monday of every month to reconcile every transaction and verify your portfolio yield data.

Stop Bad Record Keeping
Record Keeping

Frequently Asked Questions

What happens if a small business tax has poor record keeping

Submitting inaccurate details on property tax returns triggers formal adjustment notifications from HMRC. You will be required to pay the missing tax alongside calculated interest. Depending on whether your record keeping was careless or intentionally misleading, HMRC levies percentage-based penalties on the underpaid amount. An organized property system avoids these reporting mistakes.

How many years can HMRC investigate?

The formal look-back timeline depends directly on the quality of your record-keeping habits. For basic reporting errors where reasonable care was taken, the limit is four years. If HMRC discovers careless errors or omitted income, the window expands to six years. Deliberate evasion extends the audit window to twenty years.

Can HMRC find me after 20 years?

Yes, modern data matching makes historical tax evasion highly discoverable. The tax authority uses automated software to cross-reference land registry deeds, local council housing records, and mortgage applications against individual tax profiles. Maintaining a transparent property system prevents old omissions from resurfacing as modern legal issues.

What if my rental business made a loss 5 years ago?

Historical losses remain valid for tax optimization but must be officially filed within the statutory four-year window to be carried forward. These documented losses can then be offset against current or future rental profits to lower your taxable income. A robust property system keeps these older calculations organized.

My partner and I aren’t married. How does that affect the tax?

Unmarried joint owners are taxed based on their actual beneficial interest in the property, which matches the legal ownership split on the deed. Unlike married couples, unmarried partners cannot freely shift income splits using an HMRC Form 17. A proper property system tracks individual tax bands to ensure accurate distributions.

Does HMRC really know if I’m renting out my old flat?

Yes, the tax authority accesses deep third-party data pools. They consistently scan tenant deposit scheme registries, local authority licensing logs, and online rental listings. If a property address shifts status without a corresponding section on your self-assessment, automated flags identify the missing rental income.

I only plan to rent it for a year. Do I still need to tell HMRC?

Yes, short rental windows do not exempt you from UK tax regulations. Any gross property earnings above the basic one thousand pound annual property allowance must be declared through self-assessment. Tracking short-term letting details within an explicit property system ensures you stay fully compliant with temporary tenancies.

Can I deduct mortgage interest from my rental income?

No, residential landlords cannot deduct finance costs or mortgage interest directly from rental revenues. Tax relief for finance costs is restricted to a basic twenty percent tax credit applied directly against your final liability. A professional property system tracks this rule to prevent major cash flow surprises for higher-rate taxpayers.

To streamline your portfolio and avoid common compliance mistakes, contact Felix Accountants to design a clean, automated tracking framework.

Record keeping System Guide: Stop Bad Record Keeping Book Your Comprehensive Property Tax Review

Categories
Articles Blogs FAQs Guides News

Trying to do everything yourself

When you start a new property venture, it is tempting to handle every single task yourself. You might be bootstrapping, trying to minimize expenses while navigating initial growth. You handle company registration, website design, tenant screenings, and bookkeeping. However, as your portfolio expands, the operational demands on your time multiply rapidly. Moving from working in your business to working on your business requires a reliable property system to sustain expansion.

Successful property investors view their operations as an entity distinct from their individual identity. They design systematic frameworks that allow their businesses to run smoothly without requiring their constant, hands-on intervention.

Value-Based Time Allocation

Every daily task carries a different notional value. Some operational duties are worth ten pounds an hour, while high-level strategic acquisitions are worth one thousand pounds an hour.

To achieve sustainable scale, you must dedicate your focus to those high-value, thousand-pound activities. This shift means intentionally shifting lower-value administrative tasks to external specialists or trusted software tools.

Task LevelValue Per HourTypical ExamplesOperational Treatment
Low£10 – £20Initial lead entry, social media posting, filing receiptsAutomate or delegate to freelancers
Medium£50 – £100Documenting standard procedures, detailed deal analysisDelegate to specialized team members
High£1000+Strategic joint ventures, capital raising, final acquisition decisionsRetain for principal investor

Core Elements of a Scalable Property System

Delegating tasks before establishing clear processes often leads to costly organizational errors. Before hiring assistants on platforms like Fiverr, Upwork, or People Per Hour, you need to document exactly how you want each operation performed. Clear documentation ensures external support delivers work that matches your personal standards.

1. Documenting Lead Sourcing Procedures

Create an exact checklist detailing how your business sources potential real estate leads. Specify the target geographic areas, maximum purchase thresholds, and acceptable rental yield percentages. When a freelancer understands these parameters, they can filter out irrelevant opportunities, leaving you with highly qualified options.

2. Standardizing Bookkeeping and Compliance

Accurate financial record-keeping keeps your business compliant with regulatory changes. For example, HMRC requires landlords with gross property income exceeding fifty thousand pounds to register for Making Tax Digital (MTD) by April 2026. Having a standardized process for scanning receipts and recording rental income prevents severe penalties.

Important Operational Rule: Always separate your personal and business expenditures completely to avoid accounting complications and potential regulatory scrutiny.

1.Audit Current Time Use:

Week 1.

Track every task you perform for seven days to identify low-value administrative friction points.

2.Draft Standard Operating Procedures:

Week 2.

Write step-by-step instructions for tasks like tenant communications and basic expense tracking.

3.Select Your Outsourcing Platform:

Week 3.

Create accounts on Upwork or specialized virtual assistant platforms to find matching talent.

4.Implement Quality Control Metrics:

Ongoing.

Review the completed work against your documented standards weekly to refine the operational loop.Property System Guide scale Your Portfolio

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture files an inaccurate tax return, HMRC sends a formal notification outlining the financial discrepancy. You will face standard interest charges on the unpaid balance, along with potential penalties calculated based on whether the error was accidental or deliberate. Implementing a secure property system minimizes these financial risks.

How many years can HMRC investigate?

The look-back period depends directly on landlord behavior. If you took reasonable care, HMRC looks back four years. For careless bookkeeping, the window expands to six years. Deliberate tax evasion or failure to notify allows an investigation going back twenty years.

Can HMRC find me after 20 years?

Yes, modern digital tracking makes discovery highly likely. The HMRC Connect system automatically cross-references Land Registry records, bank accounts, and council tax databases to expose undeclared rental streams. Relying on professional property system accounting ensures you do not trigger automated audits.

What if my rental business made a loss 5 years ago?

Legitimate historical property losses fall within the standard investigation window but do not create immediate tax liabilities. You can actively carry forward these documented losses to offset your future rental profits. Keeping your documentation updated via an organized property system protects these valuable deductions.

My partner and I aren’t married. How does that affect the tax?

If the property title belongs strictly to one individual, that person is liable for one hundred percent of the rental income tax. Jointly owned properties typically split the incoming tax obligations fifty-fifty. A structured property system maps these ownership structures to maintain precise tax compliance.

Does HMRC really know if I’m renting out my old flat?

Yes, automated data matching leaves clear digital trails. HMRC regularly tracks changing voter registries, tenancy deposit protection data, and mortgage classifications. An unannounced change in your address often triggers an automated warning letter if no rental income appears on your self-assessment.

I only plan to rent it for a year. Do I still need to tell HMRC?

Yes, all short-term rental income above the one thousand pound annual property allowance must be formally declared. Failing to notify the tax authority because of a short rental timeline still results in automated penalties. Consistent execution through a solid property system avoids these simple compliance oversights.

Can I deduct mortgage interest from my rental income?

Individual residential landlords cannot deduct mortgage interest payments directly from their rental earnings. The old deduction system has been replaced with a fixed twenty percent tax credit. Integrating your portfolio with a professional property system helps track how this restriction impacts higher-rate taxpayers.

If you want to free up your schedule and reduce administrative friction, visit Felix Accountants to establish a compliant framework for your growing business.

Trying to do everything yourselfBook Your Comprehensive Property Tax Review
Categories
Articles Blogs Guides

Landlord Tax Expenses: The Complete UK Property Deduction Guide

Not claiming all the expenses, you can.

Landlords often pay more tax than necessary because they fail to claim legitimate business expenses. UK tax legislation changes frequently, but the core principle remains consistent: you can deduct costs that are incurred wholly and exclusively for your property business. Reducing your taxable profit directly lowers your final tax bill.

Thorough record-keeping ensures you do not leave money on the table. When you track every transaction, you protect your profit margins and maintain tax compliance.

What Counts as a Allowable Property Expense?

HM Revenue and Customs (HMRC) allows you to deduct revenue expenses from your rental income. A revenue expense is money spent on the day-to-day running of the property. This differs from capital expenditures, which involve improving the property or purchasing assets.

Maintenance and Repairs

You can deduct the cost of updates that restore the property to its original condition. Payments to contractors for fixing leaks, treating damp, or repairing broken windows qualify fully. However, replacing a standard laminate countertop with premium granite counts as an improvement, which is a capital expense rather than a revenue deduction.

Professional and Administrative Fees

Running a rental business involves administrative overheads. You can deduct letting agent management fees, legal fees for renewing tenancies, and professional fees paid to accountants. Subscriptions to property management software, professional insurance policies, and specialized industry magazines are also fully allowable.

Travel and Communication

Travel undertaken solely for property business purposes is deductible. This includes visiting the property for inspections or meeting contractors. You can claim flat-rate mileage allowances rather than tracking actual fuel costs, which is often more efficient.

Phone calls made specifically to resolve tenant emergencies or manage bookings are also valid deductions. If you use a single phone line for personal and business use, you must look at your itemized bills to separate and claim only the business portion.

Smart Landlord Tax Deductions You Might Miss

Many property owners overlook specific home-office and travel deductions because standard guidance rarely highlights them.

Business Mileage Rates

You can claim 45p per mile for the first 10,000 miles driven in a tax year for business trips using your personal car. This rate drops to 25p per mile after that threshold. This reimbursement can be paid from a business bank account to yourself tax-free, lowering your overall property profits.

Use of Home as an Office

If you manage your portfolio from a dedicated workspace at home, you can claim a proportion of your household bills. You can calculate actual costs based on the number of rooms used and time spent, or use HMRC simplified flat-rate expenses for business use of home. This reduces your taxable income by recognizing that administrative work happens outside the rental property itself.

Non-Allowable Expenses and Dual Purpose Pitfalls

HMRC strictly rejects expenses that serve a dual purpose. For an expense to be deductible, it cannot have a hidden personal benefit.

  • Clothing: You cannot claim for ordinary clothes or business suits worn to meet tenants, as these items serve a everyday personal function. Only specialized safety gear or branded uniforms qualify.
  • Food and Drink: Meals consumed during normal working days are private expenses. You cannot deduct the cost of your lunch while visiting a local property.
  • Private Travel: Trips that combine a property inspection with a family holiday cannot be claimed. If you cannot separate the business travel from the personal journey, the entire expense becomes non-allowable.

    Property Expenses
    Expense

Frequently Asked Questions

What expenses can I claim as a landlord UK?

Landlords can claim revenue expenses incurred wholly and exclusively for managing properties. These include letting agent fees, accountant costs, property repairs, insurance, and specific travel expenses. Capital improvements do not qualify for immediate revenue deduction.

Can I claim travel expenses as a landlord?

You can claim travel expenses if the journey is solely for property management purposes. Landlords usually use the standard HMRC mileage rate of 45p per mile to calculate these costs. Personal trips or mixed-purpose journeys are strictly excluded.

Are legal fees tax deductible for rental property?

Legal fees for subletting, renewing a tenancy agreement for less than fifty years, or evicting tenants are deductible. However, legal costs associated with buying or altering properties are capital expenses and cannot reduce your ongoing rental income tax.

Can I claim internet as a rental expense?

You can claim a proportion of your internet costs if you use your home connection to manage your property portfolio. You must calculate the business use percentage accurately, as HMRC does not allow deductions for the personal portion of dual-purpose utilities.

How do property expenses reduce my tax bill?

Deducting legitimate property expenses reduces the net profit figure that you report to HMRC. Since your income tax is calculated solely on net profit rather than gross revenue, maximizing your allowable claims directly lowers your total tax liability.

Landlord Tax Expenses: The Complete UK Property Deduction Guide Book Your Comprehensive Property Tax Review


Categories
Blogs FAQs Guides

Let Property Campaign Disclosure Process: A Practical Guide

The Let Property Campaign (LPC) provides residential landlords with a route to bring their UK tax affairs up to date by disclosing previously undeclared rental income to HM Revenue & Customs (HMRC).

HMRC introduced the campaign in 2013 to encourage landlords to correct their tax affairs voluntarily. It may be relevant if you have received an HMRC nudge letter or discovered that you have not reported rental income correctly.

Making a complete disclosure can help you establish the correct tax liability and may reduce penalties, depending on the circumstances. The amount payable will depend on the tax years involved, your rental profits, the nature of the error and whether your disclosure is prompted or unprompted.

Understanding the Let Property Campaign disclosure process before you begin can help you prepare the necessary records, meet HMRC’s deadline and avoid common mistakes.

Let Property Campaign Disclosure Process: Overview

StepActionKey tasks and outputs
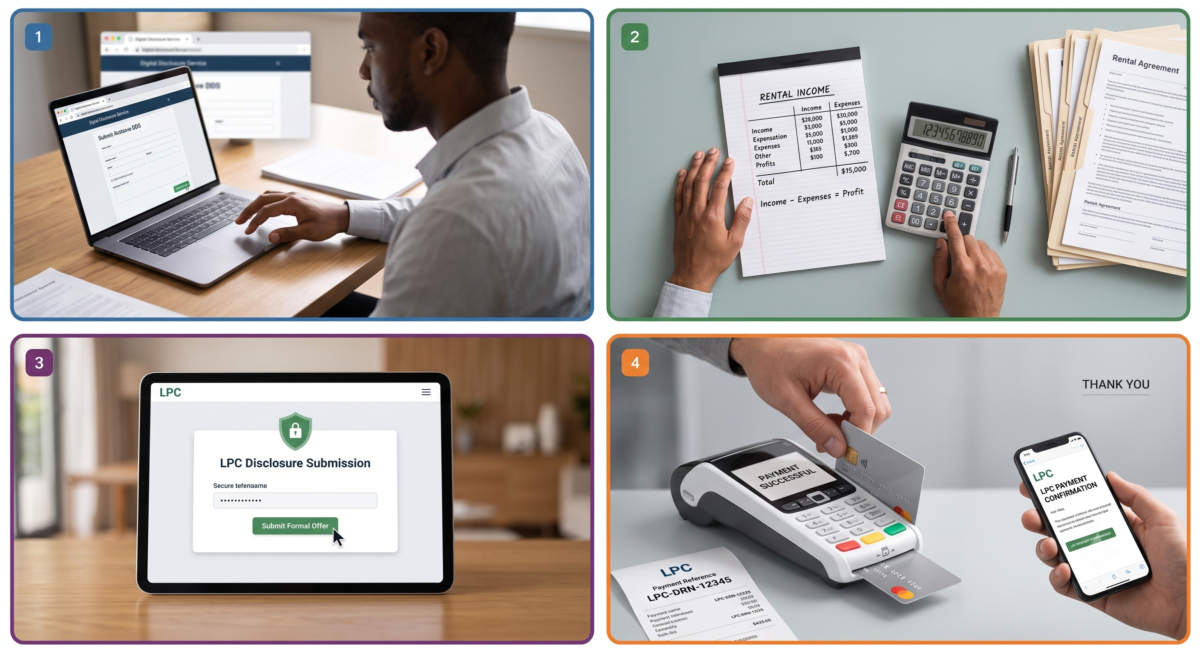
1. Notify HMRCSubmit the Digital Disclosure Service (DDS) notificationHMRC issues a disclosure reference number and payment reference number after notification.
2. Calculate tax and penaltiesCalculate rental profits and outstanding liabilitiesEstablish the tax, interest and any applicable penalties for the relevant years within the 90-day window.
3. Submit formal disclosureSend the completed disclosure and formal offer to HMRCHMRC reviews the submission and may ask for more details.
4. Settle the liabilityPay the amount due or discuss payment difficulties with HMRC beforehandPay by HMRC’s deadline or discuss payment difficulties with HMRC beforehand.

What Is the Difference Between Notifying HMRC and Making the Disclosure?

Notification is the first stage. You tell HMRC that you intend to put right unpaid tax from residential letting, but you do not have to provide all the rental figures at that point.

HMRC then issues reference numbers and a notification acknowledgement. The disclosure is the later stage, when you calculate the relevant income, expenses, tax, interest and any penalties and present the full explanation.

You must check the deadline on the acknowledgement. HMRC’s Let Property Campaign guidance says the disclosure must be made within 90 days of the date you receive that acknowledgement, and it explains what to do if the amount cannot be paid in full.

Keep the acknowledgement with your records and note its date. If you have several properties or years to correct, prepare one clear schedule for each year. The aim is a complete, consistent explanation that HMRC can review.

Eligibility for Let Property Campaign Disclosure

The Let Property Campaign covers individuals with undeclared income from residential property. You may be eligible if you have received rental income that was not correctly reported to HMRC.

Examples include:

  • Renting out a room in your main home where the Rent a Room relief conditions or limits have not been correctly applied.
  • Renting out one or multiple residential properties.
  • Living abroad while renting out UK residential property.
  • Living in the UK while renting out residential property overseas, where the relevant UK tax rules apply.
  • Receiving income from a holiday home that you rent out, even if you also use the property personally.

Eligibility depends on your circumstances and the type of property and income involved.

Can My Spouse and I Make One Joint Rental Income Disclosure?

HMRC says that a single Let Property Campaign disclosure cannot include more than one person. If spouses or other co-owners each have undeclared rental income, they need separate notifications and disclosures for their respective shares.

Before completing either form, compare the tenancy agreements and ownership records with the amounts shown in any previous tax returns. Agree a consistent schedule of gross rent, relevant costs and the tax years involved, then check how the income should be attributed to each person.

Do not simply assume that all jointly held properties must be reported in the same way without reviewing the facts. If one owner has already reported their share, that does not remove the need to review the other owner’s position.

Felix & Co. can help both owners prepare a clear record of what each person needs to disclose.

Exceptions

The Let Property Campaign is intended for residential landlords and does not cover every type of property or taxpayer.

It is generally not the appropriate route for:

  • Commercial property income, such as income from shops, commercial garages or storage units.
  • Rental income belonging to companies or other entities rather than an individual landlord.

Trusts and other ownership arrangements can require specific consideration. Check the current HMRC guidance to establish the correct disclosure route for your circumstances.

HMRC Nudge Letters

HMRC uses information from a range of sources to identify potential discrepancies between property ownership, rental activity and reported income. These sources may include property records and information supplied by third parties.

If HMRC identifies a possible discrepancy, it may send a letter asking you to review your tax position.

If you receive a nudge letter, read it carefully and note any response deadline. Check which tax years and properties it refers to, gather the relevant records and establish whether your previous tax returns were complete.

Do not assume that every letter has the same legal status or that receiving one automatically prevents you from making a disclosure through the campaign. Your options depend on the nature of HMRC’s contact and whether a formal enquiry or compliance check has begun.

For more information, read our guide to prompted versus unprompted disclosure.

How to Start a Let Property Campaign Disclosure

Following the correct steps helps you prepare an accurate disclosure and respond to HMRC’s requirements.

Step 1: Notify HMRC

Start by informing HMRC of your intention to disclose previously undeclared rental income. Submit your notification through the official Digital Disclosure Service (DDS) on GOV.UK.

If you are reporting income on behalf of someone who has died, make it clear that you are acting for the estate and follow HMRC’s instructions for that situation.

At this stage, you are notifying HMRC of your intention to disclose. You do not need to complete the full rental income calculation as part of the initial notification.

HMRC will issue a disclosure reference number and payment reference number. Keep these details safe and use the relevant reference when communicating with HMRC or making payments.

Information to Prepare

Personal details: When notifying HMRC, provide the information requested by the current HMRC notification service. At this stage you are notifying your intention to disclose; detailed rental figures are prepared for the later disclosure.

Property details: Prepare the addresses, years let, ownership shares, rent received and relevant records for the calculation stage. HMRC may ask for further details during the disclosure process.

You should also begin collecting tenancy agreements, rental statements, expense receipts, previous tax returns and correspondence with HMRC.

Step 2: Calculate the Tax Owed

After receiving your notification acknowledgement, you generally have 90 days to prepare and submit your formal disclosure. Check the exact deadline stated in HMRC’s acknowledgement and guidance.

For each relevant tax year, calculate your total rental income and deduct the allowable expenses for that year.

Depending on your circumstances, allowable expenses may include:

  • Letting agent fees.
  • Repairs and maintenance.
  • Property insurance.
  • Relevant safety certificates and compliance costs.
  • Other qualifying costs incurred wholly and exclusively for the rental business.

The rules for expenses, finance costs, property allowances and reliefs can vary according to the tax year and the nature of your letting activity. Do not automatically deduct every payment connected with a property.

Calculate the taxable rental profit using the rules applicable to each year. Then establish the tax due, taking account of your other income, relevant allowances, reliefs and the tax rates applicable to that period.

Do not include income that has already been correctly declared, except where a correction to the original figures is required.

You should also calculate any interest and applicable penalties. These depend on the facts of your case, including the tax years involved, the type of error and your behaviour.

Preparing clear supporting calculations for each year makes it easier to explain the figures if HMRC requests further information.

For help preparing the documents for your rental disclosure, ensure that your records are complete and consistent before submitting your figures.

Step 3: Submit the Formal Disclosure

Once you have completed your calculations, prepare the formal disclosure using HMRC’s prescribed process.

Your disclosure should explain the rental income that was omitted, the relevant tax years, the calculations supporting your figures and the circumstances that led to the original error.

Include the tax, interest and applicable penalties in accordance with HMRC’s requirements, and make the appropriate formal offer.

A formal disclosure does not mean HMRC has automatically accepted your calculations. HMRC will review the information and may ask you or your adviser to provide clarification or additional evidence.

Ensure that the figures agree with your supporting records and that any estimates are clearly explained.

Step 4: Arrange Payment

You must deal with the outstanding liability in line with HMRC’s deadline and payment instructions.

Use the payment reference number provided by HMRC when making the payment. Check the amount and reference carefully to help ensure that your payment is allocated correctly.

If you cannot pay the full amount immediately, contact HMRC as early as possible to discuss whether a Time to Pay arrangement is available. Explain your financial circumstances and provide any information HMRC requests.

Do not assume that requesting an instalment arrangement automatically changes your disclosure deadline or payment obligations. Confirm the arrangements and any relevant deadlines directly with HMRC.

What Happens After HMRC Receives My Disclosure?

HMRC reviews the disclosure and may ask you or your adviser to explain amounts, estimates or the reason for the original omission.

Its published guidance says that, where HMRC is satisfied that a full disclosure has been made, it will write to accept the offer. This is not a promise of immediate acceptance or an agreed processing time for every case.

Keep the submitted calculation, proof of payment and correspondence in a secure folder. If HMRC asks questions, answer accurately and provide the relevant working papers rather than changing figures without explanation.

Once the earlier years have been dealt with, check what needs reporting through the normal tax return process in future. If HMRC has contacted you already, the correspondence should also be reviewed when deciding how the disclosure should be described.

Ask Felix & Co. to review the documents if you need help responding.

Penalties Under the Let Property Campaign

HMRC may charge penalties when rental income has not been correctly reported or a taxpayer has failed to notify HMRC of a tax liability.

The penalty depends on the applicable legislation, the tax year, the type of failure and the circumstances. HMRC considers factors such as whether the error was careless or deliberate, whether information was concealed and whether the disclosure was prompted by HMRC.

A voluntary disclosure may help reduce the penalty where the relevant conditions are met, but it does not guarantee a particular reduction or eliminate the underlying tax and interest.

How Cooperation Can Affect Penalties

When determining the reduction available for certain penalties, HMRC may consider the quality of your disclosure and your cooperation.

  • Telling: Explain clearly what was wrong and provide a complete account of the missing income.
  • Helping: Answer questions and cooperate with HMRC in checking the relevant figures.
  • Giving access to records: Respond to HMRC’s requests for relevant information and supporting evidence.

The applicable penalty rules and reduction calculations should be checked against the legislation and HMRC guidance relevant to your case.

Penalties for Failure to Notify

A failure-to-notify penalty may apply if you did not tell HMRC about a tax liability when required to do so.

The potential penalty depends on the relevant tax regime, when notification was required, the nature of the behaviour and whether the disclosure was prompted or unprompted.

Non-deliberate failure to notify, timing and penalty position should be checked against the relevant legislation and year.

Other categories, including deliberate and deliberate-and-concealed behaviour, also require a case-specific assessment. Do not rely on a single percentage range without confirming that it applies to the particular tax year and circumstances.

Penalties for Inaccurate Tax Returns

Different rules may apply if you submitted Self Assessment tax returns but omitted rental income or entered incorrect figures.

The outcome depends on whether you took reasonable care, made a careless error or deliberately submitted an inaccurate return. The distinction matters because the applicable penalty rules and potential reductions can differ.

If you discover an error in a previously submitted return, establish which years are affected and whether HMRC has already contacted you. Then determine the appropriate correction and disclosure route.

For a more detailed explanation, read our guide to Let Property Campaign penalties.

What If HMRC Has Already Written to Me About Undeclared Rent?

You may still need to correct the tax position after HMRC contacts you, but you should not assume the disclosure is unprompted.

HMRC looks at the circumstances, including what you had reason to believe it had already discovered. Read the letter carefully and keep its date, any attached certificate and the stated response deadline.

Check what information HMRC is asking for, and do not send a guess simply to meet the date. Compare the years mentioned with your rental records and decide whether you need advice before responding.

Penalty treatment depends on the type of error, the facts and the quality of the disclosure, so a fixed percentage should not be promised.

A complete explanation is still worthwhile even where HMRC has made contact. Felix & Co. can help you work through the letter and supporting records.

Frequently Asked Questions

How does HMRC find out about undeclared rental income?

HMRC can compare information from different sources to identify potential discrepancies between property ownership, rental activity and declared income. Information from property records and third parties may contribute to compliance checks.

A discrepancy does not automatically establish that tax is owed, but it may lead HMRC to request further information or investigate the circumstances.

How far back can HMRC look into undeclared rental income?

The period HMRC can assess depends on the relevant tax legislation, the type of error and the circumstances.

Different time limits may apply where reasonable care was taken, where a loss of tax arose through careless behaviour, or where the loss was deliberate. Longer periods can apply in certain cases involving deliberate behaviour.

Do not assume a single look-back period applies to every Let Property Campaign disclosure. Review the relevant years with reference to the rules applicable to your case.

What happens if I ignore an HMRC nudge letter?

Ignoring HMRC correspondence can make it harder to resolve a potential tax discrepancy and may increase the risk of further compliance action.

Read the letter, establish what HMRC is asking for and respond by the stated deadline where required. If you are unsure how to proceed, seek professional advice before sending an incomplete or inaccurate response.

Does an LPC disclosure need to include other income sources?

The disclosure should follow HMRC’s requirements and cover the liabilities that need to be corrected. If you have other previously undeclared income or gains, you should establish whether these need to be reported through the same or a different disclosure route.

Do not assume that every type of income can automatically be included in a Let Property Campaign disclosure. Check the relevant HMRC guidance for the particular income and circumstances.

Can I pay my tax liability in instalments?

You may be able to arrange a Time to Pay agreement with HMRC if you cannot afford to pay the full liability immediately.

Contact HMRC as early as possible, explain your circumstances and confirm what arrangements are available. Do not assume that an instalment request automatically extends your disclosure deadline or changes your obligations.

Can I use the Let Property Campaign if HMRC has already started investigating me?

You should not assume that the campaign remains available if HMRC has already opened a formal enquiry or compliance check.

The correct route depends on the nature and stage of HMRC’s contact. Review the correspondence and obtain advice if necessary before deciding how to disclose the outstanding liability.

Even where the campaign is not available, correcting the position and cooperating with HMRC may remain important when the applicable penalty rules are considered.

What should I do if I am unsure how to calculate my rental profits?

Start by gathering rental statements, tenancy agreements, expense records, ownership documents and previous tax returns. Organise the information by property and tax year.

Check which costs are allowable, how any property finance costs should be treated and how the rental income should be attributed between co-owners. Professional advice can help identify errors before the disclosure is submitted.

Get Help With Your Let Property Campaign Disclosure

Correcting undeclared rental income can involve several tax years, detailed calculations and decisions about interest, penalties and payment arrangements.

The right approach depends on your rental history, ownership structure, previous tax returns and any correspondence you have received from HMRC.

Felix & Co. can help you review your rental tax position, organise the supporting records and understand the steps involved in making an accurate disclosure.

Ask Felix & Co. to review your rental tax position before submitting your disclosure.
LPC Disclosure Guide: Step-by-Step HMRC Process  Book Your Comprehensive Property Tax Review