Categories
Articles Articles Blogs Let Property Campaign

Let Property Campaign: How Should You Deal With Rental Income From a Property Abroad?

Overseas rental income disclosure can be relevant if you are UK resident and have not reported rent from property abroad. Paying tax in the country where the property sits does not automatically settle your UK tax position. This guide explains which records to check and when the Let Property Campaign might be suitable. And the Let Property Campaign extends to exactly this situation. Here’s how it works, and what makes overseas disclosures a little different from a straightforward UK-only case.

Not sure how to bring an overseas rental property up to date with HMRC? Book a free 15-minute consultation with Felix Accountants. Book your free call here.

Do You Need to Declare Rent From a Property Abroad?

Whether rent from an overseas property is taxable in the UK depends first on your UK tax residence status and any relevant reliefs. UK residents are normally taxed on foreign income, including overseas rent, but residence cannot be determined by a simple day-count rule alone.

Does the Let Property Campaign Cover Overseas Property?

Yes. The Let Property Campaign is open to individual landlords with undeclared residential rental income from property in the UK or abroad. This means a UK resident with an undisclosed overseas rental property is generally eligible to use exactly the same voluntary disclosure route as someone with an undeclared UK buy-to-let, subject to the usual eligibility rules — the campaign is for individuals, not companies or trusts.

Avoiding Double Taxation

If tax has been paid overseas, Foreign Tax Credit Relief may be available against UK tax on the same income. The amount depends on the relevant double-taxation agreement and the tax involved; it may not remove the entire UK liability. Report the overseas income where required and retain evidence of foreign tax paid.

Why HMRC’s Reach Now Extends Well Beyond UK Borders

HMRC can receive information from overseas authorities under lawful information-sharing arrangements. This does not mean HMRC automatically receives every property or rental transaction. Rather than guessing what HMRC may know, check whether the income was correctly reported in the UK.

Let Property Campaign vs the Worldwide Disclosure Facility

HMRC can receive information from overseas authorities under lawful information-sharing arrangements. This does not mean HMRC automatically receives every property or rental transaction. Rather than guessing what HMRC may know, check whether the income was correctly reported in the UK. Our guide on the common mistakes people make using the Worldwide Disclosure Facility is worth reviewing if your situation extends beyond rental income alone — for example, if it also involves undeclared overseas investment income or foreign bank interest, where the WDF may be the more appropriate channel.

Why Penalties Can Be Higher for Overseas Non-Disclosure

Offshore tax errors can involve different legislation, behaviour assessments and penalties, depending on the tax year and circumstances. Do not assume the same penalty applies to every overseas-property case

How Many Years Do You Need to Go Back?

As with UK property, the look-back period depends on the reason for non-disclosure rather than simply how long the property has been let. Our guide on how many years you need to declare sets out the general framework, and the same principles apply to overseas property, though the practical process of gathering years of foreign records, converted into sterling, often takes longer to prepare than an equivalent UK disclosure.

What You’ll Need to Gather for an Overseas Property Disclosure

  • Rental income received each year, converted to GBP using the correct exchange rate for each period
  • Evidence of any local tax paid on the same rental income, to support a foreign tax credit claim
  • Records of allowable expenses — many of the same categories apply as for UK property, such as agent fees, insurance, and repairs
  • Details of the letting arrangement, including dates and any local property management or agency involved

What About Non-Residents Renting Out UK Property?

The reverse situation also applies. UK residents aren’t the only ones with cross-border obligations — non-residents renting out UK property have their own reporting requirements under the Non-Resident Landlord Scheme, and can also use the Let Property Campaign to correct historic undeclared UK rental income. Our guide on expat tax rules for non-resident landlords covers this side of the picture if it’s more relevant to your situation.

How Felix Accountants Can Help

Overseas disclosures involve extra layers most UK-only cases don’t — currency conversion, foreign tax credits, and sometimes limited or differently formatted local records. We help UK residents bring overseas rental property fully up to date through the Let Property Campaign, calculating what’s genuinely owed after accounting for tax already paid abroad, and managing the disclosure process with HMRC. See our full Let Property Campaign guide for the wider disclosure process this sits within.

Frequently Asked Questions

Do I need to declare rent from an overseas property if I’ve already paid tax on it abroad?

Offshore tax errors can involve different legislation, behaviour assessments and penalties, depending on the tax year and circumstances. Do not assume the same penalty applies to every overseas-property case

Can I use the Let Property Campaign for a property outside the UK?

Yes. The campaign covers undeclared residential rental income from property in the UK or abroad, provided you’re an individual landlord rather than a company or trust.

Is it riskier to leave overseas rental income undeclared than UK rental income?

In some respects yes. Penalties for uncorrected offshore non-compliance can be significantly higher than standard UK penalties, and international data-sharing has made overseas income increasingly visible to HMRC.

How does HMRC find out about rental income from a property abroad?

HMRC may receive certain overseas information through international arrangements. It is not possible to infer which data was obtained about an individual property without evidence. Accurate reporting and good records remain the safest starting point.

Should I use the Let Property Campaign or the Worldwide Disclosure Facility?

For most cases involving only undeclared rental income from residential property, the Let Property Campaign is usually the appropriate and more specialised route. The Worldwide Disclosure Facility tends to suit broader offshore income or asset disclosures.

How do I report overseas rental income on a UK tax return?

If you are UK resident and required to report foreign rental income, HMRC normally expects you to use the foreign section of your Self Assessment return. You should keep a schedule showing gross rent, expenses, any overseas tax paid and the figures translated into pounds sterling using an appropriate method for the year concerned. Keep the foreign tax assessment or payment evidence if you want to claim credit relief. The correct UK treatment can differ where you qualify for a special foreign income relief or your residence position changed during the period.

How do I report overseas rental income on a UK tax return?

If you are UK resident and required to report foreign rental income, HMRC normally expects you to use the foreign section of your Self Assessment return. You should keep a schedule showing gross rent, expenses, any overseas tax paid and the figures translated into pounds sterling using an appropriate method for the year concerned.

Keep the foreign tax assessment or payment evidence if you want to claim credit relief. The correct UK treatment can differ where you qualify for a special foreign income relief or your residence position changed during the period.

What if my overseas rental records are incomplete?

Missing overseas statements do not mean you should invent numbers or abandon a disclosure. First ask the foreign bank, local letting agent or managing company for statements covering the relevant years. Obtain tenancy agreements, rent receipts, invoices for maintenance and proof of any local tax paid. Create a separate annual schedule and document how each amount was translated into sterling. If older documents genuinely cannot be recovered, HMRC’s Let Property Campaign guidance allows you to explain how reasonable estimates were reached and may ask to see your workings. Do not apply a standard expense percentage without a genuine basis.

Bring your overseas rental property up to date with HMRC. Book your free 15-minute consultation with Felix Accountants.
Categories
Blogs News Property Tax News

Capital Gains Tax on UK Property: Essential Facts

Selling a property can generate a substantial profit, but it may also create a Capital Gains Tax (CGT) liability. Understanding the rules before completing a sale can help property owners calculate their potential tax bill, identify available reliefs and avoid missing important HMRC deadlines.

Whether you own a buy-to-let property, a second home or an investment property, the tax treatment depends on your circumstances and the type of property you sell.

In this guide, Felix & Co Accountants explains seven essential facts about Capital Gains Tax on UK property in 2026, including current residential property rates, allowable costs, tax-free allowances and reporting requirements.

What Is Capital Gains Tax on UK Property?

Capital Gains Tax is a tax on the profit you make when you dispose of an asset that has increased in value. For property owners, it commonly applies to the sale of rental properties, second homes, investment properties and certain land.

You do not usually pay CGT on the sale of your main home if you qualify for full Private Residence Relief.

For example, suppose you bought a buy-to-let property for £200,000 and later sold it for £300,000. The initial difference is £100,000, but your taxable gain may be lower after deducting eligible buying, selling and improvement costs and applying any available reliefs.

The tax is generally calculated on the chargeable gain rather than the entire sale proceeds.

Understanding how the gain is calculated is important because the final tax liability depends on more than the difference between the purchase price and the selling price.

Who Needs to Pay Capital Gains Tax When Selling Property?

You may need to pay Capital Gains Tax if you sell or otherwise dispose of a property that is not fully covered by an applicable exemption or relief.

This commonly affects:

  • Landlords: Individuals selling buy-to-let properties may owe CGT on their chargeable gains.
  • Second-home owners: A holiday home or another residential property may be subject to CGT.
  • Property investors: Gains from investment properties and certain land disposals may be taxable.
  • People selling inherited property: CGT may arise if the property increases in value after inheritance and is subsequently sold.
  • Non-UK residents: Special reporting and tax rules apply to UK property and land disposals.

The tax treatment depends on the ownership structure, the property’s use and the owner’s circumstances.

What about selling your main residence?

Private Residence Relief can eliminate CGT on a qualifying main home. Full relief is generally available where the relevant conditions are met, including occupying the property as your only or main residence throughout ownership and meeting the applicable requirements concerning use and grounds.

If you have rented out part of your home, used part of it exclusively for business or spent periods living elsewhere, the position may be more complicated.

Read the official HMRC Private Residence Relief guidance to understand the conditions that apply.

What Are the Capital Gains Tax Rates on UK Property in 2026?

For individuals disposing of residential property that does not qualify for full Private Residence Relief, the applicable CGT rates depend on the tax year, taxable income and available basic-rate Income Tax band.

For the 2026/27 tax year, the main residential property CGT rates for individuals are:

  • 18% on the portion of the taxable gain falling within the available basic-rate band.
  • 24% on the portion falling above the available basic-rate band.

Your taxable gain is added to your taxable income when determining how much of the gain falls within each band. Consequently, a person may pay both rates on different portions of the same gain.

The annual exempt amount for individuals is £3,000 for the 2026/27 tax year. This allowance reduces the amount of chargeable gains subject to tax; it is not a tax credit worth £3,000.

Different rules apply to companies, trusts and certain other ownership arrangements.

For current rates and official examples, consult HMRC’s Capital Gains Tax rates and allowances guidance.

Which Capital Gains Tax Reliefs and Allowances Can You Claim?

Appropriate reliefs and allowable costs can reduce the chargeable gain on a property disposal. However, eligibility depends on the circumstances.

Private Residence Relief

Private Residence Relief can reduce or eliminate CGT when you sell a property that qualifies as your main home.

The amount of relief depends on factors such as how long you occupied the property as your main residence and whether any periods or parts of the property fall outside the qualifying conditions.

Annual exempt amount

Individuals generally have a £3,000 annual exempt amount for 2026/27. If your total relevant gains fall within the available allowance, you may not have CGT to pay, although reporting obligations can still apply in particular circumstances.

The allowance applies to qualifying gains across relevant assets, not separately to every property sold.

Allowable buying and selling costs

Eligible costs may include estate agent fees, solicitors’ fees and certain expenses incurred when acquiring or disposing of the property.

These costs must meet the relevant tax rules and be supported by appropriate records.

Capital improvement costs

Qualifying expenditure on improvements that enhance the property may be deductible when calculating the gain, provided the expenditure meets HMRC’s requirements.

For example, the cost of constructing an extension may qualify, whereas ordinary maintenance and decorating costs generally do not count as deductible capital improvement expenditure for CGT purposes.

Other reliefs

Depending on the circumstances, additional reliefs may be relevant to particular disposals. Do not assume that a relief applies simply because a property was rented out or owned for a long period.

Check the specific eligibility conditions before including any relief in your calculation.

How Do You Calculate Capital Gains Tax on a Property Sale?

The calculation generally starts with the sale proceeds and deducts the property’s acquisition cost and eligible expenditure. Applicable reliefs and the annual exempt amount are then considered when determining the taxable gain.

A simplified illustration is shown below.

CalculationAmount
Property sale price£300,000
Original purchase price£200,000
Eligible buying, selling and improvement costs£10,000
Illustrative gain before annual exemption and other reliefs£90,000
Annual exempt amount, assuming none has been used elsewhere£3,000
Illustrative taxable gain£87,000

This example assumes that the £10,000 of costs is fully allowable, that no other reliefs or losses apply and that the full £3,000 annual exempt amount is available.

The resulting £87,000 is the illustrative taxable gain, not the amount of tax payable.

The actual CGT liability depends on the applicable rates, the seller’s taxable income, any available basic-rate band and other relevant tax circumstances.

For a detailed calculation, use the official HMRC property gain calculator and guidance.

What Is the 60-Day Capital Gains Tax Reporting Deadline?

One of the most important rules for UK residential property sellers is the requirement to report and pay CGT within 60 days of completion where tax is due under the applicable rules.

This means you should not automatically wait until the next Self Assessment filing deadline to deal with a taxable residential property disposal.

Missing the deadline can result in interest and penalties.

Before selling, gather the following information:

  • Property purchase and sale prices.
  • Acquisition and completion dates.
  • Eligible buying, selling and improvement costs.
  • Details of any applicable reliefs or exemptions.
  • Ownership percentages where the property is jointly owned.

UK residents generally do not need to report gains through the property reporting service if their total gains are below the tax-free allowance, subject to the applicable rules. Non-UK residents have separate reporting obligations and generally must report UK property and land disposals even when no tax is due.

If you are already required to submit a Self Assessment return, you may also need to include the disposal in that return.

For the precise requirements, see HMRC’s guidance on reporting and paying CGT on UK property.

How Can Property Owners Reduce Capital Gains Tax Errors?

Careful preparation before a sale can help you calculate the correct gain and avoid preventable reporting problems.

Consider the following steps:

  1. Review the property’s acquisition cost. Keep the original purchase documents and any relevant valuation records.
  2. Collect supporting invoices. Identify eligible buying, selling and capital improvement costs.
  3. Check available reliefs. Determine whether Private Residence Relief or another applicable relief may reduce the gain.
  4. Calculate the taxable gain. Account for allowable costs, losses, the annual exempt amount and the relevant tax rates.
  5. Confirm reporting deadlines. Establish whether a UK property CGT return and payment are required within 60 days of completion.
  6. Check ownership arrangements. Each joint owner generally calculates and reports their own share of the gain.
  7. Seek professional advice where necessary. Complicated ownership structures, periods of letting, inherited properties and non-resident disposals can require more detailed calculations.

Good record keeping and early planning can make the sale process easier and help you avoid unexpected tax liabilities.

Frequently Asked Questions About Capital Gains Tax on UK Property

Do I pay Capital Gains Tax when selling my main home?

Not usually if you qualify for full Private Residence Relief. If the property was rented out, used exclusively for business or not occupied as your main residence throughout the relevant period, some of the gain may be taxable.

What is the Capital Gains Tax allowance for 2026/27?

The annual exempt amount for individuals is £3,000 for the 2026/27 tax year. It applies to relevant gains collectively rather than providing a separate allowance for each property.

What are the residential property CGT rates in 2026?

For individuals, the main rates are 18% and 24%, depending on how the taxable gain falls within the available basic-rate Income Tax band. The calculation depends on taxable income and the circumstances of the disposal.

Can I deduct renovation costs from my property gain?

Some capital improvement costs may be deductible, provided they meet the relevant rules. Ordinary repairs and maintenance generally do not qualify as capital improvement expenditure for CGT purposes.

When must I report Capital Gains Tax on a UK property sale?

Where CGT is due on a qualifying UK residential property disposal, the deadline is generally 60 days after completion. Specific reporting rules apply to non-residents and other circumstances.

Can an accountant help reduce my Capital Gains Tax bill?

An accountant can help calculate the gain correctly, identify eligible costs and reliefs, check reporting obligations and explain the tax implications of a proposed sale. Any reduction must be based on legitimate reliefs and the applicable tax rules.

Need Help With Capital Gains Tax on UK Property?

Selling a property can involve complex calculations, especially where the property has been rented out, inherited, jointly owned or used as a main residence at different times.

Felix & Co Accountants can help you review your property sale, identify relevant reliefs, calculate your potential CGT liability and understand the reporting deadlines that apply.

Contact Felix & Co Accountants before completing your property sale to discuss your circumstances and plan for the relevant tax obligations.

Capital Gains Tax can significantly affect the proceeds you retain when selling a UK property. Understanding the current rates, the annual exempt amount, allowable costs and available reliefs can help you make informed decisions.

The most effective approach is to calculate the potential gain before selling, maintain accurate records and confirm your reporting obligations early.

Because tax rules and individual circumstances vary, check current HMRC guidance or obtain professional advice before relying on a particular calculation.

Capital Gains Tax on UK Property: 7 Essential Facts

Book Your Comprehensive Property Tax Review

Categories
Blogs Guides

10 Everyday Situations That Turn Into Tax Errors for Landlords

Not every landlord sets out to become one. Plenty of people end up letting a property because of a relationship change, a job relocation, an inheritance, or simply because selling felt like the wrong move at the time. The problem is that HMRC doesn’t treat “accidental” landlords any differently from professional ones — the rental income still needs to be declared, and the tax errors that follow from not realising this are some of the most common reasons Landlord Tax Mistakes end up needing the Let Property Campaign.

Below are ten real-world situations where landlords typically go wrong, and what should actually happen in each case. If you recognise your own circumstances in any of them, it’s worth acting sooner rather than later.


1. Moving In With a Partner

The situation: Someone moves into their partner’s home and decides to rent out their own property rather than sell it. Because the rent roughly covers the mortgage payment, they assume there’s nothing to tax.

Where it goes wrong: Only the interest portion of a mortgage repayment counts as an allowable expense, and even that relief is restricted to the basic rate of income tax — the capital repayment portion doesn’t count at all. Rental profit still needs to be worked out and declared, and if this has been going on for a while, the Let Property Campaign is the route to correct past years.

2. Inheriting a Property

The situation: Someone inherits a house and decides to let it rather than sell, using a local agent to manage tenants, collect rent, and handle repairs, with costs deducted before the balance is paid out.

Where it goes wrong: It’s easy to assume that because an agent is “handling everything,” there’s no personal tax obligation. In reality, the legal responsibility for declaring rental profit sits with the landlord, not the agent — regardless of how long the letting has been running. Where several years have passed undeclared, the LPC covers exactly this scenario.

3. Buying Property as an Investment

The situation: A property is bought specifically for rental income, without a clear picture of what tax obligations come with it.

Where it goes wrong: Beyond declaring the annual rental profit, investment purchases also carry a Capital Gains Tax question further down the line if the property is ever sold. Both need factoring in from the start, not worked out retrospectively once a sale is already underway.

4. Divorce or Separation

The situation: A jointly owned home is rented out rather than sold following a separation, with both parties moving into smaller properties and an agent handling the letting.

Where it goes wrong: Each party is responsible for declaring their own share of the rental profit on their individual Self Assessment return — it isn’t automatically split or handled as a joint filing, and the specific ownership split needs reflecting accurately.

5. Relocating for Work

The situation: A married couple moves to a different area for a job and lets out their previous home, without declaring the resulting rental income.

Where it goes wrong: Both partners need to declare their respective share of the rental income individually. A change of address doesn’t pause the reporting obligation — it simply adds rental income onto whatever else is already being declared.

6. Moving Into a Care Home

The situation: Someone moves into residential care and lets their own home to help cover care costs, without treating the rental income as taxable.

Where it goes wrong: It’s a common but incorrect assumption that income used to cover care fees is somehow exempt. It isn’t — rental profit is taxable regardless of what it’s ultimately spent on, and needs to be declared like any other letting.

7. Jointly Owned Investment Property

The situation: A couple jointly buys a property to renovate and let, with one partner paying tax at a higher rate than the other.

Where it goes wrong: Jointly owned lettings need careful allocation of income and allowable expenses between owners, following the correct ownership-share rules — this becomes more important, not less, when the owners sit in different tax bands.

8. Buying a Property for a Family Member at University

The situation: Parents buy a flat for their child during university, charging no rent — but the child takes in flatmates who pay rent covering more than the mortgage.

Where it goes wrong: Even where the original intention was rent-free family accommodation, rental income generated by flatmates is still taxable to whoever owns the property. PAYE employees in this position often don’t realise they now also need to report rental profit through Self Assessment.

9. Serving in the Armed Forces

The situation: Someone posted overseas rents out their UK family home to a friend, without considering how UK tax rules apply from abroad.

Where it goes wrong: This typically falls under the Non-Resident Landlord rules, and both the property owner and any joint owner need to establish their reporting obligations and declare rental profit through Self Assessment as appropriate — being posted abroad doesn’t remove the requirement.

10. Tied Accommodation

The situation: New landlords of a pub move into the flat above it as tied accommodation, then let out their own house to a family member at a rent matching their mortgage payment.

Where it goes wrong: As with the “moving in together” scenario, only the mortgage interest is an allowable expense, restricted to the basic rate — the full mortgage payment isn’t deductible. Letting to family doesn’t change the reporting requirement either, even at a modest, cost-covering rent.

Landlord Tax Mistakes

The Common Thread

Every one of these situations shares the same root cause: an assumption that a particular kind of rental arrangement — informal, family-related, agent-managed, or simply small — falls outside HMRC’s radar. None of them do. If any of these scenarios sound familiar, working out the correct rental profit and using the Let Property Campaign to disclose past years is generally the most cost-effective way to resolve it, particularly compared with waiting for HMRC to raise the question first. Our guide to voluntary disclosure sets out exactly how much that difference in timing is worth.

For a full walk through of eligibility, the disclosure process, and what to expect, our complete Let Property Campaign guide covers everything in one place, and our property tax guide is a good starting point for the underlying rules on rental income generally.

Getting It Right the First Time

Becoming a landlord, whether by choice or by circumstance, brings tax obligations that are easy to overlook and expensive to correct after the fact. If your situation matches any of the scenarios above, the safest next step is professional guidance on what needs declaring, for which years, and how to bring things up to date with the least possible cost.

10 Everyday Situations That Turn Into Tax Errors for Landlords
Book Your Comprehensive Property Tax Review

Categories
Articles Blogs FAQs Guides

The Heat is On: HMRC’s Landlord Crackdown and the Urgency of Voluntary Disclosure

HM Revenue & Customs (HMRC) has unequivocally ramped up its efforts to tackle tax non-compliance in the private rented sector (PRS). Using sophisticated data analytics, matching information from the Land Registry, local authorities, deposit schemes, and third-party platforms, HMRC is closing the net on landlords who have undeclared rental income or have underpaid tax. The Heat is On: HMRC’s Landlord Crackdown and the Urgency of Voluntary Disclosure

The message is clear: the era of ‘flying under the radar’ is over.

In this intensified compliance environment, letting agents are being called upon to play a crucial, proactive role. They are the key link between the authorities and the landlords, and they must now urge their clients with undisclosed liabilities to use the dedicated route for correction: the Let Property Campaign (LPC), a form of voluntary disclosure. Failure to do so exposes landlords to severe penalties and agents to reputational risk within an increasingly regulated industry. This article outlines the severity of the crackdown, the advantages of voluntary disclosure, and the vital steps letting agents must take immediately.

Why the Pressure on Landlords is Unprecedented

HMRC’s crackdown is underpinned by advanced data-matching technology and a focused enforcement strategy. The results speak for themselves, with the amount of unpaid tax recovered through compliance activities rising significantly year-on-year.

The Data Advantage and Increased Risk

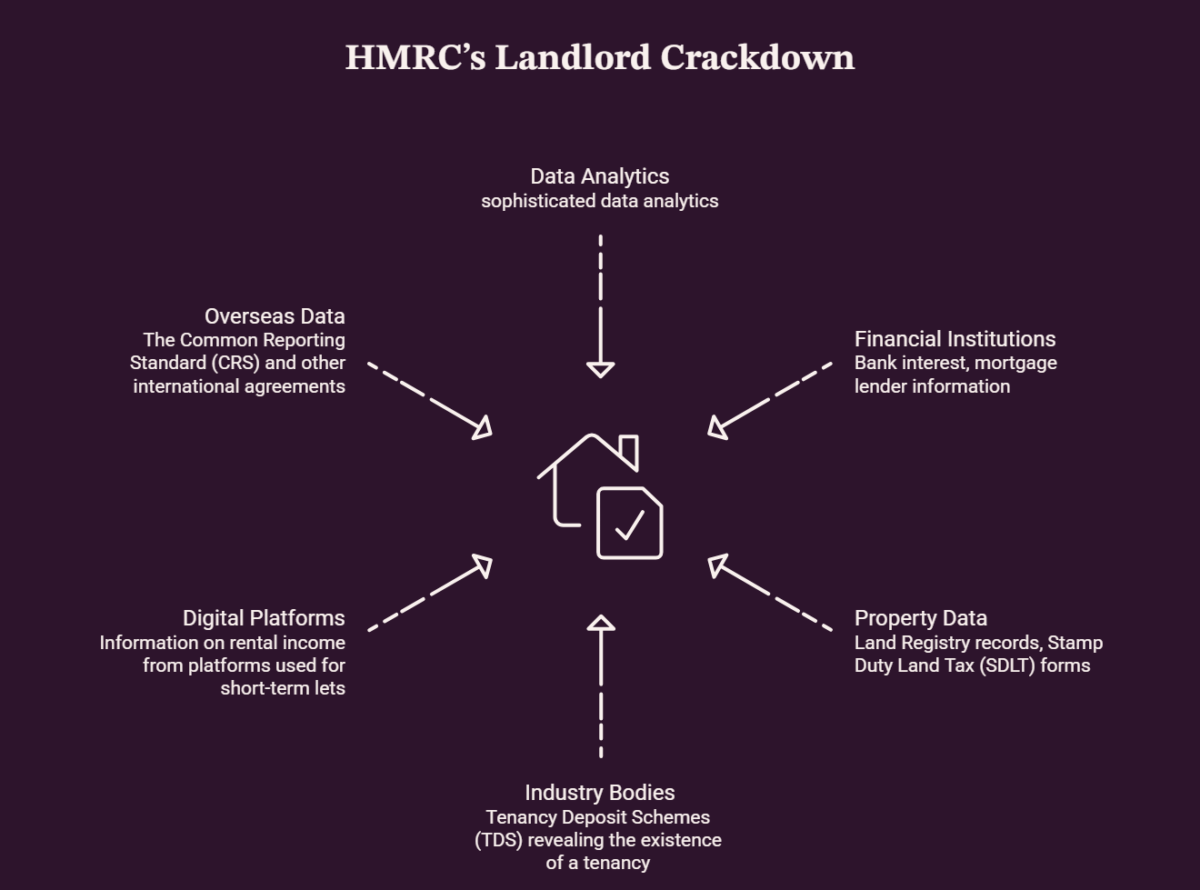
HMRC’s ability to identify non-compliant landlords has never been greater. They have the power to cross-reference data from multiple sources:

  • Financial Institutions: Bank interest, mortgage lender information.
  • Property Data: Land Registry records, Stamp Duty Land Tax (SDLT) forms.
  • Industry Bodies: Tenancy Deposit Schemes (TDS) revealing the existence of a tenancy.
  • Digital Platforms: Information on rental income from platforms used for short-term lets.
  • Overseas Data: The Common Reporting Standard (CRS) and other international agreements for landlords with offshore properties or bank accounts.

If a landlord’s tax return (or lack thereof) does not match the information HMRC holds, they will issue a ‘Nudge Letter’—a clear signal that the landlord has been identified and must take action. At this stage, the opportunity for reduced penalties through voluntary disclosure becomes more restricted.

The High Cost of Discovery vs. Disclosure

The difference in penalties for a landlord who is ‘prompted’ by HMRC (i.e., receives a letter) versus one who makes a ‘unprompted’ voluntary disclosure is vast and financially significant.

CircumstancePenalty Range (% of Unpaid Tax)Disclosure Route
Voluntary Disclosure0%–30%Let Property Campaign (LPC)
Prompted Disclosure (After ‘Nudge Letter’)20%–70%Formal Enquiry
Deliberate ConcealmentUp to 100% (or 200% for offshore income)Formal Enquiry/Prosecution

The key advantage of the LPC is the mitigation of penalties. A full, cooperative, and honest voluntary disclosure, made before HMRC’s intervention, offers the best possible terms for regularising tax affairs.

The Letting Agent’s New Role: Promoter of Compliance

Letting agents operate at the heart of the rental transaction and are in a unique position of trust and influence with their landlord clients. Their professional duty of care now extends to providing robust, general guidance on tax compliance.

Three Essential Actions for Letting Agents

Letting agents must proactively steer their clients toward compliance, not just to protect the landlord but to safeguard their own professional reputation and adhere to their professional bodies’ standards.

  1. Integrate Tax Awareness into Onboarding:
    • Mandate of Disclosure: Ensure all new landlord agreements explicitly state that the landlord is responsible for declaring all rental income to HMRC.
    • General Advisory: Provide a generic, written warning (disclaimer) in welcome packs or management contracts about the requirement to declare income and the penalties for non-compliance, directing them to the LPC. Crucially, agents should not offer specific tax advice, only general guidance to seek professional counsel.
  2. Actively Promote the Let Property Campaign (LPC):
    • Client Communication: Issue a targeted communication campaign to all existing landlords, highlighting HMRC’s crackdown data and the financial benefits of the LPC.
    • Referral Network: Establish relationships with specialist tax advisors who can handle LPC disclosures, providing a professional and safe pathway for clients.
  3. Maintain Meticulous Records:
    • Data Readiness: Agents should assume that HMRC will eventually ask for their complete records. Ensure all transactional data—rent received, expenses paid, start/end dates of tenancies—is accurate and readily available. This protects the agent and helps the landlord with their disclosure.

Addressing Common Landlord Misconceptions

Many landlords fall into non-compliance not through deliberate evasion, but through ignorance or simple oversight. Agents must address these common points:

  • ‘Accidental Landlords’: The myth that renting out a single inherited property or one that couldn’t be sold is not ‘commercial’ and therefore doesn’t need to be declared. All rental income must be declared.
  • ‘Zero Profit’: The belief that because allowable expenses (like mortgage interest) reduce profit to zero, there is no need to file a tax return. The income must still be reported on a Self Assessment tax return.
  • The Agent Reports It: The mistaken belief that the letting agent is responsible for reporting the rental income to HMRC. The legal responsibility always rests with the individual landlord.

Navigating the Let Property Campaign (LPC) for a Client

For any landlord who has undeclared rental income from UK or overseas residential property, the LPC is the formal path to resolution. Agents should guide clients through the process:

  1. Notification: The landlord (or their tax advisor) must notify HMRC of their intention to disclose using the online Digital Disclosure Service (DDS). HMRC will then issue a Disclosure Reference Number (DRN).
  2. Calculation: The landlord has 90 days from the date of the DRN to calculate the full undeclared income, allowable expenses, and the resultant unpaid tax for all relevant years. The period covered can be up to 20 years if the error was deliberate, but often less for careless mistakes (up to 6 years) or genuine errors (up to 4 years).
  3. Disclosure & Payment: The full disclosure form and payment of the tax, interest, and calculated penalty must be submitted within the 90-day window.

    HM Revenue & Customs (HMRC)
    Voluntary Disclosure

By pushing for the LPC now, letting agents help their clients avoid a future costly, stressful, and potentially public formal investigation by HMRC, reinforcing the agent’s position as a trustworthy and compliant partner in property management.

Frequently Asked Questions (FAQs) for Landlord Voluntary Disclosure

What is the HMRC Let Property Campaign (LPC)?

The LPC is a voluntary disclosure initiative by HMRC that encourages individual landlords (who own residential property in the UK or abroad) to ‘come clean’ about undeclared or underpaid rental income on the best possible penalty terms.

How far back must a landlord disclose under the LPC?

The disclosure period depends on the landlord’s behaviour:

  • 4 years for genuine mistakes (reasonable care taken).
  • 6 years for careless errors.
  • Up to 20 years for deliberate tax evasion or concealment.

What are the penalties if HMRC finds undeclared income before I disclose?

If HMRC discovers the unpaid tax before the landlord makes a disclosure (known as a ‘prompted’ disclosure), the penalty is significantly higher, typically ranging from 20% to 70% of the tax due, and up to 100% or more for deliberate offshore non-compliance. Voluntary disclosure offers much lower, often zero, penalties for unprompted, cooperative disclosures.

Can a letting agent give me tax advice for the LPC?

No. Letting agents are not qualified or regulated to provide specific tax advice. Their role is to provide general guidance about compliance and strongly urge the landlord to seek specialist advice from a qualified accountant or tax solicitor to handle the complex LPC submission.

Does the LPC cover commercial properties or undeclared business income?

No. The LPC is specifically for income from residential property lettings. Disclosures for commercial property or other types of undeclared income must be made through HMRC’s general Digital Disclosure Service (DDS).

What is a ‘Nudge Letter,’ and how should a landlord respond?

A ‘Nudge Letter’ is a communication from HMRC informing a landlord that their data suggests they have undeclared rental income. This counts as a prompted intervention. A landlord should immediately seek professional tax advice, as the penalties will be higher than a truly unprompted voluntary disclosure, but action is essential to avoid a full, much more severe investigation.

Learn More


Categories
Articles Articles Blogs Let Property Campaign

Corporation Tax and Director Expenses: Which Costs Can Your Company Reimburse?

One of the most common questions from new company directors is deceptively simple: what can I actually claim back from my own company? The underlying rule is straightforward in principle — expenses must be incurred “wholly and exclusively” for business purposes — but applying it in practice, especially where personal and business use overlap, is where most of the genuine complexity lives.

Not sure which of your costs your company can reimburse? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
The “Wholly and Exclusively” Rule

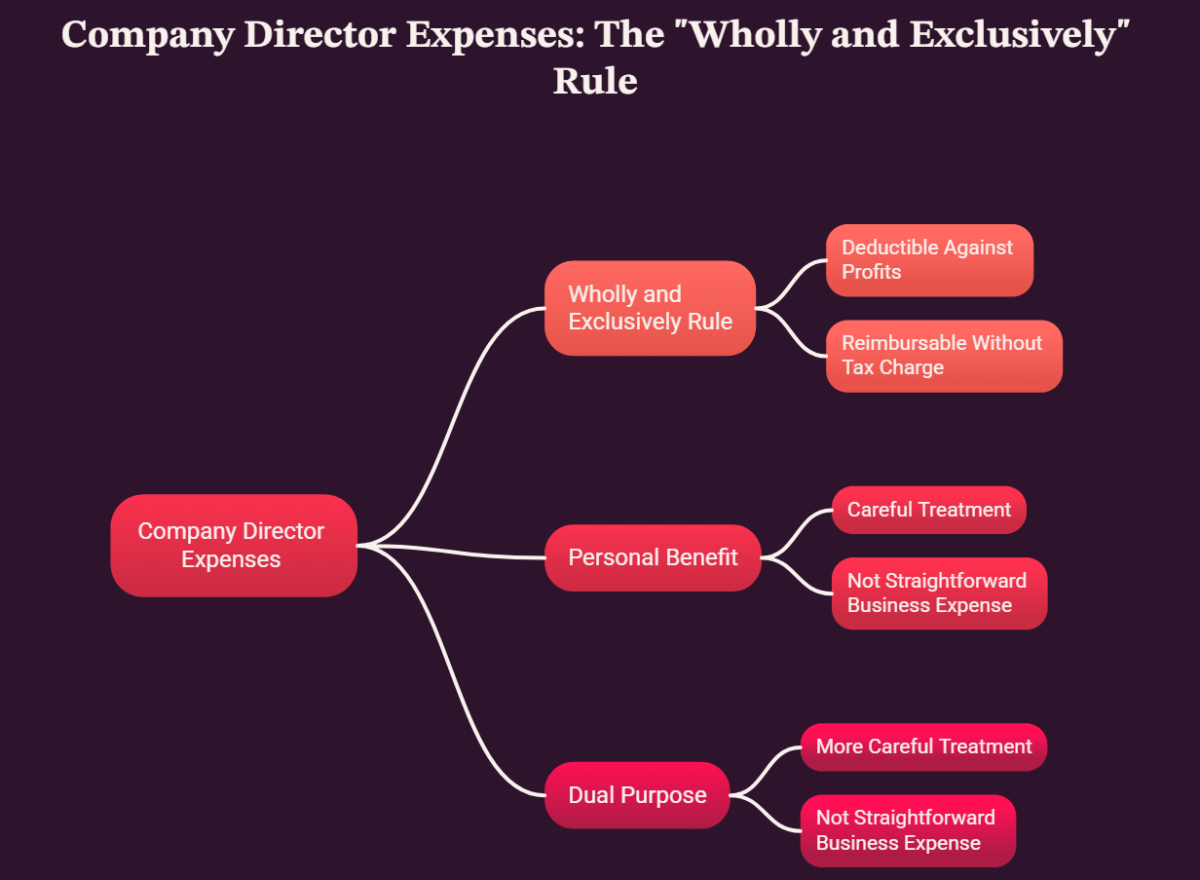
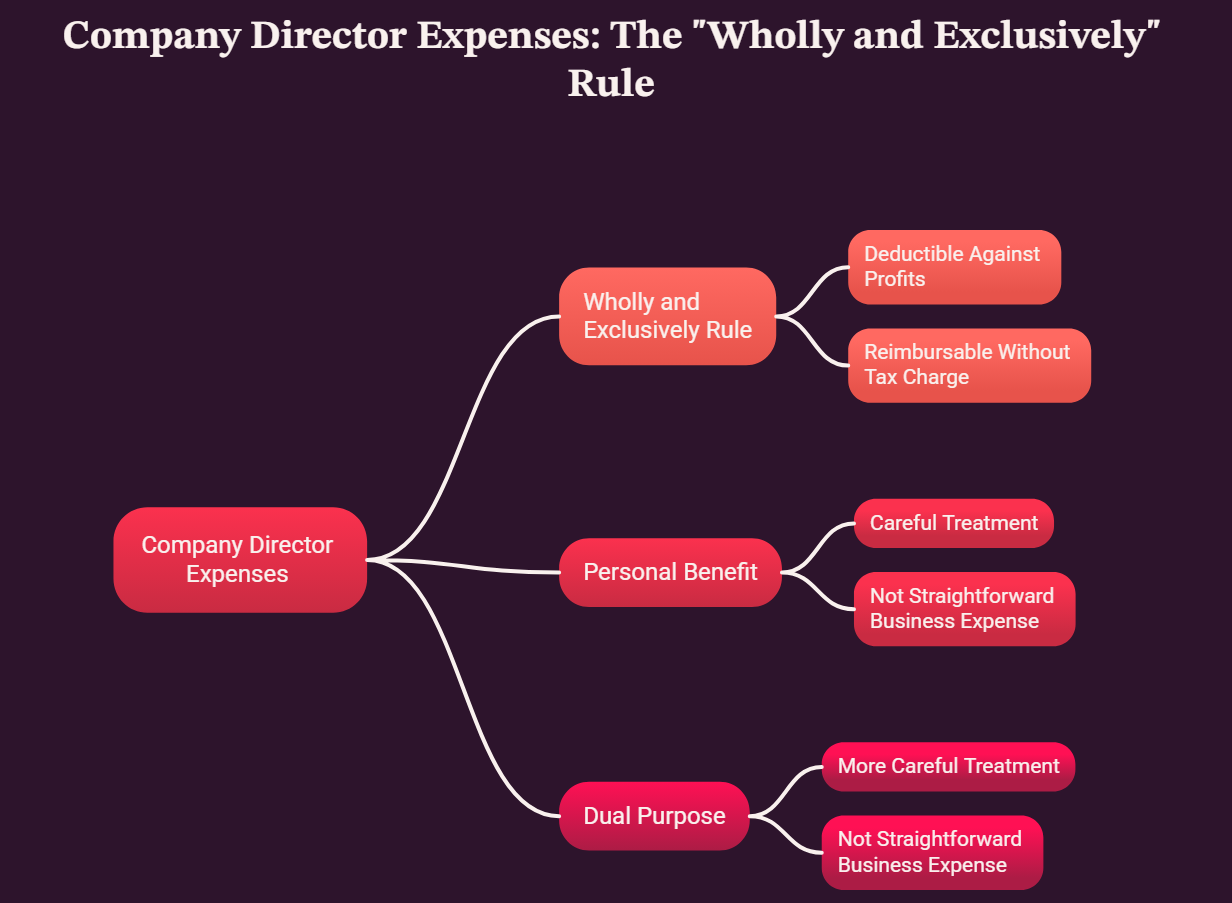
For a cost to be deductible against company profits (reducing Corporation Tax) and reimbursable to a director without creating a personal tax charge, it generally needs to have been incurred wholly and exclusively for the purposes of the company’s trade. Costs with any significant personal benefit or dual purpose need much more careful treatment, and some can’t be claimed as a straightforward business expense at all, even if there’s a genuine business element involved. Our full guide on allowable limited company expenses covers the general framework this sits within.

Straightforward Reimbursable Expenses

These generally cause few complications, as long as they’re genuinely business-related:

  • Travel costs for business journeys (excluding ordinary commuting to a permanent workplace)
  • Business mileage, using HMRC’s approved mileage rates when using a personal vehicle for company business
  • Accommodation and subsistence costs while travelling for business
  • Professional subscriptions and memberships relevant to the trade
  • Office supplies, software subscriptions, and equipment used for the business
  • Business insurance premiums
  • Training costs directly relevant to the role, in most circumstances

Our guide on claiming business mileage from your own company covers the specific approved mileage rates and record-keeping needed to support this particular claim.

Working From Home

Directors working from home can generally claim a modest, flat-rate contribution toward household costs, or a more detailed calculation based on actual additional costs (such as extra heating and electricity) attributable to business use of part of the home, provided it’s calculated on a reasonable, defensible basis rather than an arbitrary figure.

Company Cars: A More Complicated Area

Company cars are one of the most commonly misunderstood areas of director expenses. If a company provides a car that’s available for the director’s personal use (not just business use), this generally creates a taxable “benefit in kind,” reported on a P11D, with the director paying Income Tax on the benefit and the company paying Class 1A National Insurance. The tax cost of this varies significantly depending on the car’s list price and CO2 emissions, which is why fully electric or low-emission vehicles are often considerably more tax-efficient as a company car than a typical petrol or diesel model. Our guide on running your car in a tax-effective way covers this comparison in more detail, including when using your own car and claiming mileage is more efficient than a company-provided vehicle.

Business Entertainment: Generally Not Deductible

This catches a lot of directors out. Client entertainment costs — taking a client to dinner, for example — are generally not deductible against Corporation Tax at all, even though they’re a genuine, arguably necessary business cost. This is a specific, long-standing exclusion in the tax rules, distinct from the general “wholly and exclusively” test that governs most other expenses. Staff entertainment, by contrast, can qualify for a specific annual exemption (subject to a per-head limit) for events such as a Christmas party, provided the conditions are met.

Home-to-Work Travel

Ordinary commuting between home and a permanent workplace generally isn’t a deductible business expense, regardless of the distance involved. This is one of the more counter-intuitive rules for new directors, particularly where a director works primarily from a home office but occasionally travels to a separate business premises — the specific facts of where the “permanent workplace” is considered to be can significantly affect what’s claimable.

Reimbursing Genuine Personal Expenditure With a Business Element

Where a cost has both a business and personal element — a broadband contract used for both work and personal browsing, for example — only the business proportion can generally be claimed, and it needs to be calculated on a reasonable, justifiable basis. Claiming the full cost of something with genuine dual use, rather than an apportioned business element, is a common area where directors inadvertently create a benefit in kind or an incorrect Corporation Tax deduction.

What Happens When Something Isn’t a Clean Business Expense?

Where a cost doesn’t meet the wholly-and-exclusively test, or has a personal benefit element, it typically falls into one of a few categories:

  • Taxable benefit in kind: reported on a P11D, with Income Tax paid by the director and Class 1A National Insurance paid by the company
  • Not deductible for Corporation Tax at all: some costs, like client entertainment, simply aren’t allowable regardless of how they’re reimbursed
  • Treated as a dividend or salary: if a payment doesn’t fit any genuine expense category, it may need to be treated as personal income instead, with the corresponding tax treatment

Keeping the Right Records

Whatever the expense, clear supporting records matter — receipts, a note of the business purpose, and (for mixed-use costs) a documented basis for the apportionment. This protects both the Corporation Tax deduction and the director’s personal tax position if HMRC ever asks questions about a specific claim.

Pension Contributions: A Particularly Tax-Efficient Option

Separately from routine expense reimbursement, company pension contributions made directly on a director’s behalf are generally a deductible business expense for the company and don’t create a personal Income Tax or National Insurance charge for the director, making this one of the more tax-efficient ways to extract value from company profits. Our guide on using pension contributions for tax relief covers this in more detail.

wholly and exclusively

How Felix Accountants Can Help

We help directors work out exactly what can be reimbursed cleanly, what needs to go through P11D reporting, and how to structure genuinely mixed-use costs correctly. See our wider business tax services for how this fits into your company’s broader Corporation Tax position.

Frequently Asked Questions

Can my company pay for my commute to the office?

Generally no. Ordinary commuting between home and a permanent workplace isn’t a deductible business expense, regardless of distance.

Can I claim client entertainment as a business expense?

No, client entertainment costs are generally not deductible for Corporation Tax purposes, even though they’re a genuine business activity.

What happens if my company provides me with a car I can use personally?

This generally creates a taxable benefit in kind, reported on a P11D, with Income Tax paid by you and Class 1A National Insurance paid by the company, based on the car’s list price and emissions.

Can I claim the full cost of my home broadband if I use it for work?

Only the business-use proportion is generally claimable, calculated on a reasonable, justifiable basis, rather than the full personal and business cost combined.

Is it better to have a company car or claim mileage using my own car?

It depends on the specific vehicle, its emissions, and how much personal use is involved — for many directors, using a personal car and claiming approved mileage rates is more tax-efficient than a company-provided car, particularly for higher-emission vehicles.

Let’s clarify exactly what your company can reimburse. Book your free 15-minute consultation with Felix Accountants.
Categories
Articles Blogs Let Property Campaign News

What Should You Do If You Cannot Reconstruct Your Rental Income?

If you have realised you owe tax on rental income but your records are incomplete, perhaps because bank statements have been lost, rent was paid in cash or a letting agent has since closed, it does not prevent you from using the Let Property Campaign. HMRC’s own guidance says that where records are incomplete you should make your best estimate of the undisclosed income and be ready to explain how you arrived at it. The real task is producing an estimate that is reasonable, well evidenced and complete enough for HMRC to accept.

Missing records? Talk it through before you estimate.

Every gap in the paperwork can usually be approached in more than one way. Book a free 15-minute consultation with Felix Accountants to discuss what records you still have, what can be recovered and how a defensible estimate might be built for your disclosure.

Can You Make a Let Property Campaign Disclosure Without Full Records?

Yes. The HMRC Let Property Campaign guidance specifically addresses landlords who do not have all the business records they need. In summary, HMRC says:

  • if records are incomplete, you should make your best estimate of the undisclosed income and gains;
  • HMRC may ask you to explain how you worked out any estimates, so you should keep your calculations;
  • bank statements for the disclosure period will probably help, and if you do not have them you should contact your bank as soon as possible for copies;
  • if copy statements cannot be obtained at all, you can use more recent statements as a guide to income and expenditure, although HMRC may ask why earlier statements were unavailable.

In other words, missing records change how you calculate the figures, not whether you can come forward. What HMRC will not accept is a disclosure that is materially incorrect or incomplete. If you are new to the process, our step-by-step guide to the LPC disclosure process explains the notification and disclosure stages in more detail.

Why “I Can’t Reconstruct It” Is Rarely the Full Story

Most landlords who say they cannot reconstruct their rental income actually mean they cannot reconstruct it exactly. That is a very different position from having no information at all. You almost always know some of the following:

  • when you bought or inherited the property and when you first let it;
  • roughly what rent was agreed, and when it changed;
  • whether the property was ever empty, used by family or sold;
  • whether an agent was involved and what percentage they charged.

Those facts, combined with whatever third-party evidence can still be recovered, are usually enough to produce a credible year-by-year estimate. The aim is not perfection. It is a figure that a reasonable person, looking at your working papers, would accept as a fair reflection of what happened.

Step 1: Build a Timeline of What You Do Know

Before looking for documents, write down the history of each property. A simple timeline often reveals which years are genuinely uncertain and which are not.

  1. Ownership: purchase or inheritance date, your ownership share and any joint owners.
  2. Letting periods: the date each tenancy started and ended, including renewals.
  3. Rent levels: the agreed monthly rent at each point and when it increased.
  4. Voids and non-letting periods: times the property was empty, being refurbished or occupied by you or family.
  5. Management: whether you self-managed or used an agent, and the agent’s fee basis.
  6. Finance: the mortgage lender, loan amount and whether the mortgage was repayment or interest-only.

Remember that joint owners each make their own disclosure. HMRC’s guidance confirms that a disclosure cannot include details for more than one person, so a married couple with a jointly owned property would each disclose their own share.

Step 2: Recover Third-Party Evidence

Evidence created by someone else carries more weight than figures produced from memory. The table below shows common sources and what they can help establish.

Record every request you make, including the date and the response. If a bank or agent tells you records no longer exist, keep that reply. It helps answer the question HMRC is likely to ask about why the evidence is unavailable. Good habits from here on matter too; our guide to keeping proper business records covers what to retain going forward.

Step 3: Choose a Reasonable Estimation Method

There is no single prescribed formula. The right method depends on what evidence survives. In practice, one or more of the following approaches is usually used, and combining them gives a useful cross-check.

Extrapolating from years where records exist

If you have reliable figures for recent years, those can be used as a guide to earlier years, adjusted for known changes such as rent increases, voids or a change of agent. This mirrors HMRC’s own suggestion of using more recent statements where older ones cannot be obtained.

Using the contractual rent and occupancy periods

Where tenancy agreements survive but bank records do not, rental income can be estimated by multiplying the agreed rent by the months the property was actually let. Any arrears you genuinely never received, or periods when the property was empty, should be supported by whatever evidence exists.

Cross-checking against local market rents

If no agreements exist for a period, the typical rent for a comparable property in the same area at that time can be used as a sense check. It should not be used to understate income. If the market suggests a higher figure than your recollection, you need a clear reason for using the lower one.

Estimating expenses with extra care

Expenses deserve more caution than income. An estimate that inflates income is rarely challenged; an estimate that inflates costs often is. Claim costs you can reasonably support, such as agent fees at an evidenced percentage, insurance premiums confirmed by the insurer, or mortgage interest from lender statements. Only allowable property expenses can be deducted, and you cannot claim any expense already claimed against income previously reported to HMRC.

Mortgage interest also needs care across different years. For individual landlords, relief for residential finance costs was restricted in stages from 2017-18, and from 2020-21 onwards it is given as a basic rate tax reduction rather than a deduction from rental profit. Mortgage capital repayments are never deductible.

A Worked Example

A landlord has let a flat since spring 2016 but never registered for Self Assessment. Their bank only provides statements back to 2020. However, they still hold the original tenancy agreement at £850 per month, a 2019 renewal at £900 per month and an agent’s terms of business showing a 10% management fee. A council tax bill shows the flat was empty for two months in 2018.

PeriodEvidence availableEstimation approach
2016 to 2019Original tenancy agreement, agent terms, council tax bill£850 x months let, less the evidenced two-month void; agent fee at 10%
2019 to 2020Renewal agreement£900 x months let; agent fee at 10%
2020 onwardsBank statements, agent remittancesActual figures from statements; used to sense-check earlier estimates

Because this landlord never notified HMRC, the disclosure may need to go back to when the letting began, subject to the maximum periods explained in our guide on how many years of rental income landlords must disclose. Every assumption above would be written into a short explanatory note kept with the working papers.

Document Your Estimates Properly

An estimate without an explanation looks like a guess. An estimate with an explanation looks like a considered calculation. We recommend preparing a short “basis of preparation” note for each property, covering:

  • which years are based on actual records and which are estimated;
  • the method used for each estimated period and why it was chosen;
  • the evidence relied on, with copies kept on file;
  • the steps taken to recover missing records and the responses received;
  • any assumptions made where the method could have produced a range, and why the figure used is reasonable.

Keep this note even after HMRC accepts your disclosure. If HMRC later asks how a figure was calculated, you will be able to answer quickly and consistently.

Common Mistakes When Records Are Missing

  • Estimating on the low side. An optimistic estimate can make the whole disclosure look incomplete. If there is a genuine range, the figure you use should be one you can justify.
  • Ignoring cash rent. Cash received and never banked is still taxable income and should be included.
  • Leaving out other undisclosed income. The campaign requires you to include other income and gains you have not told HMRC about, such as untaxed interest or gains on property sales.
  • Double counting. Income already declared on a tax return should not be included again, and expenses already claimed cannot be claimed twice.
  • Claiming mortgage capital. Only the interest element can attract relief, and the way relief is given depends on the tax year.
  • Waiting too long to start. Once HMRC acknowledges your notification, you have 90 days to disclose and pay. Record requests to banks can take weeks, so they should be made immediately. Our 90-day deadline preparation guide sets out a practical timetable.
  • Choosing a behaviour category that does not fit the facts. Whether the error was careless or deliberate affects both the number of years and the penalty, and it must reflect what actually happened.

How Penalties and Interest Apply to Estimated Figures

Estimated figures are treated in the same way as actual figures. Interest runs from the date the tax should have been paid, and penalties are calculated as a percentage of the additional tax. HMRC’s fact sheets on penalties for inaccuracies and penalties for failure to notify explain the ranges and reductions. The quality of your disclosure, including how openly you explain any estimates, is one of the factors that affects the reduction available. You can read more in our article on Let Property Campaign penalties.

HMRC also publishes a tax, interest and penalties calculator that can help once the tax for each year has been worked out manually.

What If HMRC Questions Your Figures?

HMRC expects most disclosures to be self-explanatory, but it may contact you or your adviser to clarify points or ask for evidence. Full co-operation is a condition of the campaign. If you have kept clear working papers, answering these questions is usually straightforward.

If, after submitting, you realise something has been missed, HMRC’s guidance says you should contact them immediately to amend the disclosure. Disclosures later found to be materially incorrect are likely to attract significantly higher penalties, which is another reason to take care with estimates at the outset.

How Felix Accountants Can Help

Reconstructing rental income is part detective work and part tax calculation. At Felix Accountants, we help landlords identify which records can still be recovered, choose an appropriate estimation method for each period, prepare year-by-year computations and write the explanatory notes that support the figures. Our Let Property Campaign disclosure service covers the process from notification through to HMRC’s acceptance letter, and our article on why specialist Let Property Campaign advice matters explains where professional input tends to make the biggest difference.

Unsure whether your records are good enough to disclose? Arrange a free 15-minute call and we will talk through your situation in confidence.

Let Property Campaign

Missing records are a common obstacle, but they are not a reason to delay. HMRC’s guidance allows a best estimate, provided it is reasonable, supported by whatever evidence can be recovered and explained clearly. Start by building a timeline, request third-party records straight away, choose a sensible method for each gap and document every assumption. That approach gives your disclosure the best chance of being accepted without further enquiry.

Frequently Asked Questions

Can I use the Let Property Campaign if I have no bank statements?

Yes. HMRC’s guidance says you should make your best estimate where records are incomplete. Request copies from your bank first. If they cannot be obtained, more recent statements can be used as a guide, but HMRC may ask why the older statements were unavailable.

Will HMRC accept estimated rental income?

HMRC’s guidance allows estimates where records are incomplete, but they must be reasonable and you should keep your calculations, because HMRC may ask how you worked them out. Disclosures that are materially incorrect or incomplete are unlikely to be accepted.

How do I estimate rent if I have lost my tenancy agreements?

Other evidence can often fill the gap, such as deposit protection records, agent correspondence, messages with tenants or bank entries. Local market rents for similar properties at the time can be used as a cross-check, but should not be used to understate income.

Can I claim expenses if I do not have receipts?

Allowable expenses can sometimes be estimated where there is reasonable supporting evidence, such as insurer confirmations, lender statements or an agent’s fee terms. Expense estimates attract more scrutiny than income estimates, so claims should be cautious and well explained.

Does having incomplete records affect my penalty?

Penalties depend mainly on your behaviour and whether the disclosure is unprompted. However, the quality of your disclosure, including how openly you explain estimates and co-operate with HMRC, affects the reductions available.

Do joint owners need separate disclosures?

Yes. HMRC’s guidance states that a disclosure cannot include details for more than one person, so each joint owner discloses their own share of the income and needs their own notification.

Categories
Articles Articles Blogs Let Property Campaign

VAT Invoices: What Information Must a UK VAT Invoice Contain?

Not every invoice a VAT-registered business sends out is automatically a valid “VAT invoice” in HMRC’s eyes — and if it isn’t, your customer may not be able to reclaim the VAT they’ve paid you, which can quickly become an awkward conversation. Getting the format right isn’t complicated once you know the rules, but missing even one required field can cause real problems for your customer’s VAT recovery.

Want your invoice templates checked for VAT compliance? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
When Do You Need to Issue a VAT Invoice?

Once your business is VAT-registered, you must issue a compliant VAT invoice for every standard-rated, reduced-rated or zero-rated sale, regardless of your business structure. For B2B transactions between VAT-registered businesses, a full VAT invoice is generally expected as standard. For retail sales directly to consumers, you’re not always required to issue one automatically, but if a VAT-registered customer asks for one in order to reclaim input VAT, you’re required to provide it.

The Three Types of VAT Invoice

HMRC recognises three formats, and which applies depends on the value of the supply:

  • Full VAT invoice: required for supplies where the total, including VAT, exceeds £250
  • Simplified VAT invoice: permitted for supplies totalling £250 or less, including VAT
  • Modified VAT invoice: used for certain retail supplies over £250, showing VAT-inclusive line amounts rather than net amounts, generally with the customer’s agreement

It’s worth flagging that the £250 threshold is VAT-inclusive, not the net figure — a gross total of £250.01 pushes you into full invoice territory, with no rounding tolerance.

What a Full VAT Invoice Must Include

A full VAT invoice needs to contain all of the following:

  • A unique, sequential invoice number
  • The date of issue and the tax point (the time of supply, which determines which VAT period the sale falls into)
  • Your business name, address, and VAT registration number
  • Your customer’s name and address
  • A description of the goods or services supplied
  • For each line item: the quantity, the unit price excluding VAT, the applicable VAT rate, and the amount payable excluding VAT
  • The rate of any cash or early payment discount offered
  • The total amount payable, excluding VAT
  • The total amount of VAT charged, shown in sterling

If a single invoice covers items at more than one VAT rate — say, some standard-rated and some zero-rated goods — each rate needs to be shown separately, with its own net amount and VAT amount, rather than a single blended figure.

What a Simplified VAT Invoice Must Include

For supplies of £250 or less, a simplified invoice requires considerably fewer fields:

  • Your business name, address, and VAT registration number
  • The date (time) of supply
  • A description of the goods or services
  • The VAT rate charged per item
  • The total amount payable, including VAT

Notably, a simplified invoice doesn’t need to show the customer’s name and address, or a separate net-of-VAT figure — this is why till receipts and hospitality bills, for smaller transactions, are usually valid VAT documents without the full level of detail. Exempt supplies shouldn’t be included on a simplified invoice alongside taxable ones.

What a Modified VAT Invoice Must Include

A modified invoice is used for larger retail supplies (over £250) where the retailer’s systems are set up to show VAT-inclusive amounts rather than net figures. It includes the same information as a full VAT invoice, but line items and totals are shown inclusive of VAT, alongside a clear statement of the total amount including VAT.

Common Reasons a VAT Invoice Gets Rejected

  • Missing or incorrect VAT registration number
  • Address details for either party incomplete or missing entirely
  • VAT shown as a single blended figure where multiple rates actually applied
  • No unique invoice number, or duplicated numbering across different periods
  • The tax point date missing, or clearly inconsistent with when the supply actually took place

Any of these can give HMRC grounds to challenge input VAT recovery for the recipient, which is why it’s worth periodically checking your invoice template against the current requirements rather than assuming it’s still correct.

Invoice Numbering

Every VAT invoice needs a unique, sequential number. If you restart your numbering each calendar year without a distinguishing prefix, you risk creating duplicate invoice numbers across different years, which can cause confusion in your own records as well as HMRC’s. Using a consistent prefix (such as the year, or a customer reference) alongside a running sequence avoids this problem.

Documents That Are Not Valid VAT Invoices

It’s worth being clear that a pro-formal invoice, a statement of account, or a delivery note are not acceptable substitutes for a proper VAT invoice — HMRC doesn’t accept these as valid evidence for reclaiming input VAT, regardless of how much detail they contain. If you’re issuing a pro-formal ahead of a formal invoice, make sure it’s clearly labelled as such and followed up with a genuine VAT invoice once payment terms are agreed.

Timing: When Must You Issue the Invoice?

VAT invoices generally need to be issued within 30 days of the time of supply (the tax point), which is usually the earlier of the date goods or services were provided, or the date payment was received, subject to specific rules for certain types of supply.

VAT Invoices and Making Tax Digital

Regardless of invoice format, VAT-registered businesses need to keep digital records of their sales and purchases under Making Tax Digital, with invoice data typically flowing into MTD-compatible accounting software rather than being tracked manually alongside a separate digital record.

What If You’re Selling Property or Involved in Property Development?

VAT treatment for property transactions has its own additional complexities on top of the standard invoicing rules described here, particularly around whether a supply is standard-rated, zero-rated, or exempt. Our guides on VAT and property in the UK and VAT implications for property developers and investors cover this in more detail if your invoicing involves property transactions specifically.

How Felix Accountants Can Help

We help VAT-registered businesses review and correct their invoice templates, make sure the right format is used for the right transaction value, and set up systems that keep invoicing compliant as your business grows. See our wider taxation services for how accurate VAT invoicing fits into your broader compliance position.

Frequently Asked Questions

What’s the difference between a full and simplified VAT invoice?

A full VAT invoice is required for supplies over £250 (including VAT) and needs the customer’s details plus a full breakdown of net, VAT, and total amounts. A simplified invoice, for £250 or less, needs fewer fields and doesn’t require the customer’s name and address.

Do I need to issue a VAT invoice for every sale?

You must for B2B transactions with other VAT-registered businesses. For retail sales to consumers, it’s not always automatic, but you must provide one if a VAT-registered customer asks for it.

Can I use a pro-formal invoice to reclaim VAT?

No. HMRC doesn’t accept pro-formal invoices, statements, or delivery notes as valid VAT invoices for reclaiming input tax.

What happens if my VAT invoice is missing required information?

HMRC can refuse the recipient’s input VAT recovery if the invoice doesn’t meet the required format, so it’s worth checking your templates carefully against the current requirements.

How soon after a sale must I issue a VAT invoice?

Generally within 30 days of the time of supply (the tax point), which is usually the earlier of the goods/services being provided or payment being received.

Let’s get your invoice templates HMRC-compliant. Book your free 15-minute consultation with Felix Accountants.
Categories
Articles Articles Blogs Let Property Campaign

Self Assessment Tax Return for Multiple Income Sources: How to Report Everything Correctly

Plenty of people today have income from more than one place — a full-time job plus some freelance work on the side, a rental property alongside a business, or dividends from a small investment portfolio layered on top of a salary. The good news is that all of this generally goes on a single Self Assessment return, using different supplementary pages for each type of income. The key is making sure every source is captured correctly and nothing falls through the gaps.

Juggling several income sources and want it reported correctly? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Why Multiple Income Sources Still Mean One Return

A common misconception is that different income types need entirely separate tax returns. In reality, a single Self Assessment return covers your entire tax position for the year, built up from a main return plus a series of “supplementary pages” specific to each type of income you have. Your overall tax liability is then calculated on your total income across all sources, taking into account your personal allowance and the tax bands that apply as your combined income rises.

Employment Income (Already Taxed Through PAYE)

If you’re employed, your salary is generally already taxed at source through PAYE, but it still needs to be reported on your Self Assessment return if you’re required to file one for another reason — for example, because of rental or self-employment income. This isn’t double taxation; it’s simply reporting the full picture so HMRC can calculate your overall position correctly, including whether your combined income pushes you into a higher tax band or affects things like the personal allowance taper for high earners.

Self-Employment or Freelance Income

Self-employment income, including freelance and side-hustle earnings, is reported on the self-employment supplementary pages, where you declare your total income and deduct allowable business expenses to arrive at your taxable profit. Our guide on allowable self-employed expenses covers what can be claimed here, and our article on how tax actually works for a side hustle is a useful starting point if this is a newer income source for you.

Rental Income

Rental income from UK property goes on its own dedicated property income pages, separate from employment or self-employment income, with its own set of allowable expenses and its own rules — including the restricted mortgage interest relief that applies to individually owned residential lettings. Our guide to filing taxes as a landlord covers this specific supplementary page in more depth.

Dividend and Investment Income

Dividends, whether from a personal share portfolio or from your own limited company, are reported separately from other income and benefit from their own tax-free dividend allowance before the applicable dividend tax rates apply. Interest from savings similarly has its own reporting section and its own personal savings allowance, which varies depending on your overall tax band.

Partnership Income

If you’re a partner in a business partnership, your share of the partnership’s profit is reported on its own supplementary page, separate from any personal self-employment income you might also have outside the partnership. Our guide on understanding partnership agreements covers how partnership profit-sharing typically works, which feeds directly into what each partner needs to report individually.

Income From Outside IR35 Contracting

If some of your income comes from contracting work, it’s worth being clear on whether IR35 (off-payroll working rules) applies to that engagement, since this affects whether the income is treated as employment income (with tax already deducted by the fee-payer) or self-employment income reported and taxed through your own return. Our guide on understanding IR35 and off-payroll working rules explains this distinction, which matters for correctly categorising this type of income on your return.

Making Sure Your Personal Allowance Is Applied Correctly

With multiple income sources, particularly where some income is taxed at source (like PAYE salary) and some isn’t (like rental or self-employment profit), it’s worth checking that your personal allowance and tax bands are being applied sensibly across your total income, rather than assuming each income source is taxed in isolation. Our guide on maximising your personal tax-free allowance covers how this works in practice, including the taper that reduces the personal allowance for higher earners.

A Practical Checklist Before You File

  • Have you included every income source, even smaller or occasional ones?
  • Have you selected the correct supplementary pages for each income type?
  • Have you double-checked which expenses relate to which income source, rather than mixing them together?
  • Have you accounted for any income already taxed at source, so it isn’t accidentally taxed twice?
  • Have you checked whether your combined income affects other allowances, such as the Child Benefit high income charge or the personal allowance taper?

Why Errors Are More Common With Multiple Income Sources

The more income sources involved, the easier it is for something to be missed, double-counted, or reported in the wrong section — particularly where income arrives through different channels (bank transfers, platform payments, letting agent statements) and isn’t consolidated until tax return time. Our guide on understanding the UK tax year and key deadlines is a useful companion for planning ahead, particularly if you’re juggling records from several sources throughout the year rather than gathering them all at once in January.

How Felix Accountants Can Help

We regularly prepare Self Assessment returns for people with several income sources, making sure everything is captured on the right supplementary pages, allowable expenses are correctly matched to the right income type, and your overall tax position is calculated accurately across the full picture — rather than treating each income source in isolation.

Frequently Asked Questions

Do I need a separate tax return for each type of income I have?

No. A single Self Assessment return covers all your income for the year, using different supplementary pages for each income type, such as employment, self-employment, property, and dividends.

Do I need to report my salary if it’s already taxed through PAYE?

Yes, if you’re required to file a Self Assessment return for another reason, your PAYE income still needs to be included so HMRC can calculate your total tax position correctly.

Can rental income and self-employment expenses be mixed together on the same page?

No. Each income type has its own supplementary pages and its own specific allowable expenses, and mixing them together can lead to an incorrect calculation.

Does having multiple income sources increase my chance of an HMRC enquiry?

Not inherently, but more income sources do increase the chance of an accidental omission or misreporting, so it’s worth taking extra care to ensure everything is captured correctly.

What happens if I forget to include one of my income sources?

You can correct this by amending your return, generally within 12 months of the filing deadline, or through a formal correction process if more time has passed.

Let’s get all your income reported correctly, in one place. Book your free 15-minute consultation with Felix Accountants.

Categories
FAQs Guides News

The Benefits of Outsourcing Accounting Services for Property Investors

In the dynamic world of property investment, time is money. As a property investor, your focus should be on identifying lucrative opportunities and growing your portfolio, not getting bogged down by the complexities of accounting. Outsourcing your accounting needs to a professional accounting firm in the UK can be a game-changer, providing you with expert support, ensuring compliance, and delivering significant cost savings for investors.

Why Outsourced Accounting is a Smart Move for Property Investors

Imagine you’re juggling multiple properties across different regions. Each property comes with its own set of financial records, tax obligations, and regulatory requirements. Managing all this can feel like trying to navigate a maze blindfolded. That’s where outsourced accounting for property investors comes into play, acting as your guiding light through the financial labyrinth.

1. Access to Expert Knowledge and Experience

Outsourcing connects you with professionals who specialize in accounting services in the UK, particularly tailored for property investors and SMEs.

  • Specialized Expertise: These professionals understand the intricacies of property taxation, capital gains, and VAT implications.
  • Up-to-Date Compliance: They stay abreast of the latest tax laws and regulations, ensuring you remain compliant with HMRC requirements.

Real-Life Example: Sarah, a property investor in London, found herself overwhelmed by tax complexities. By outsourcing to a professional firm, she not only remained compliant but also discovered tax relief opportunities she wasn’t aware of, saving her thousands of pounds.

2. Significant Cost Savings for Investors

While it might seem counterintuitive, outsourcing can lead to substantial cost reductions.

  • Eliminate Overheads: No need to hire full-time, in-house accountants, saving on salaries, benefits, and training costs.
  • Avoid Costly Mistakes: Professionals help prevent errors that could result in fines or missed deductions.

Statistic: According to a study by Deloitte, businesses can save up to 40% on operational costs by outsourcing accounting functions.

3. Enhanced Focus on Core Investment Activities

Time spent on accounting is time taken away from expanding your investment portfolio.

  • Efficiency Boost: Free up your schedule to focus on market research, property acquisitions, and networking.
  • Peace of Mind: With experts handling your finances, you can invest with confidence, knowing your accounting is in good hands.

Analogy: Think of outsourcing as hiring a seasoned captain for your ship, allowing you to chart new territories without worrying about navigating stormy seas.

4. Access to Advanced Technology and Systems

Professional accounting firms utilize cutting-edge software and systems.

  • Real-Time Financial Reporting: Gain access to up-to-date financial information anytime, anywhere.
  • Data Security: Robust systems ensure your sensitive financial data is protected against breaches.

Expert Insight: John Miller, a senior accountant at a leading professional accounting firm in the UK, notes, “Our clients benefit from sophisticated accounting platforms that offer insights and analytics not typically available in-house.”

5. Scalability and Flexibility

As your property portfolio grows, your accounting needs will evolve.

  • Adaptable Services: Outsourced firms can easily scale their services to match your growth.
  • Customized Solutions: Receive tailored SME accounting solutions that fit your specific requirements.

6. Improved Compliance and Reduced Risk

Navigating tax laws and regulations can be daunting.

  • Regulatory Compliance: Professionals ensure all filings are accurate and submitted on time.
  • Audit Support: In the event of an HMRC audit, your outsourced team can provide necessary documentation and representation.

Case Study: When David’s property company faced an unexpected audit, his outsourced accounting firm managed the process smoothly, resulting in a clean bill of health from HMRC.

Addressing Common Concerns About Outsourcing

“Won’t I lose control over my finances?”

Outsourcing doesn’t mean relinquishing control; it means partnering with experts.

  • Transparency: Reputable firms provide regular reports and maintain open communication.
  • Collaboration: You remain involved in decision-making processes, with the added benefit of expert advice.

“Is outsourcing only for large companies?”

Not at all. SME accounting solutions are specifically designed to support small and medium-sized enterprises, including individual property investors.

How to Choose the Right Professional Accounting Firm in the UK

Selecting the right partner is crucial.

  • Experience with Property Investors: Ensure the firm has a proven track record in the property sector.
  • Comprehensive Services: Look for firms offering a full suite of services, from bookkeeping to strategic financial planning.
  • Client Testimonials: Seek out reviews or speak to other investors about their experiences.

Tip: Schedule a consultation to discuss your needs and gauge the firm’s understanding and responsiveness.

The Long-Term Benefits of Outsourced Accounting

Beyond immediate cost savings and efficiency gains, outsourcing offers long-term advantages.

  • Strategic Financial Planning: Experts can help you plan for growth, investment diversification, and retirement.
  • Tax Optimization: Ongoing advice ensures you’re taking advantage of all available tax benefits.
  • Business Continuity: With a dedicated team managing your finances, there’s no disruption due to staff turnover or absence.

Analogy: Outsourcing is like having a co-pilot who not only helps navigate but also plans the journey ahead, ensuring you reach your destination smoothly.

Empower Your Property Investment Journey

Outsourcing your accounting needs is more than a tactical move; it’s a strategic decision that can propel your property investment business to new heights. By leveraging the expertise of a professional accounting firm in the UK, you unlock benefits that extend far beyond number-crunching.

Take the Next Step Towards Financial Excellence

Don’t let accounting challenges hinder your investment success. Contact us today to discover how our tailored accounting services in the UK can support your property investment goals.

Frequently Asked Questions

1. What are the main benefits of outsourcing accounting for property investors?

Answer: Outsourcing provides access to expert knowledge, significant cost savings, enhanced focus on core investment activities, advanced technology, scalability, improved compliance, and reduced risk.

2. How can outsourcing lead to cost savings for investors?

Answer: By eliminating the need for in-house accounting staff, you save on salaries, benefits, and training. Outsourcing also helps avoid costly mistakes and ensures all tax deductions are maximized.

3. Is outsourcing accounting services suitable for small property investors?

Answer: Yes, outsourcing offers SME accounting solutions tailored to the needs of small and medium-sized property investors, providing expert support without the overhead of an in-house team.

4. Will I lose control over my financial decisions if I outsource?

Answer: No, you remain in control of your finances. Outsourced firms work collaboratively with you, providing transparency and regular updates to inform your decisions.

5. How do I choose the right professional accounting firm in the UK?

Answer: Look for firms with experience in the property sector, a comprehensive range of services, positive client testimonials, and a responsive, communicative approach.

6. Can outsourcing help with tax compliance and avoiding penalties?

Answer: Absolutely. Professional accountants stay updated on tax laws, ensuring compliance with HMRC regulations and helping you avoid fines or legal issues.

7. What services do outsourced accounting firms typically offer?

Answer: Services often include bookkeeping, tax planning, financial reporting, payroll management, VAT returns, and strategic financial advice.

8. How does outsourcing accounting enhance my focus on investment activities?

Answer: By handling time-consuming accounting tasks, outsourcing frees up your time to focus on identifying new investment opportunities and growing your portfolio.

9. Are my financial data and information secure with an outsourced firm?

Answer: Reputable firms implement robust data security measures to protect your sensitive financial information from breaches or unauthorized access.

10. Can outsourced accounting services scale with my business growth?

Answer: Yes, outsourced services are flexible and can easily adapt to your changing needs as your property investment portfolio expands.

Categories
Articles Articles Let Property Campaign

Let Property Campaign for Inherited Rental Property: What Should Beneficiaries Consider?

Inheriting a rental property brings its own particular set of tax questions, and they don’t always arrive at a convenient time — often in the middle of dealing with probate, grief, and a range of other practical matters. Two distinct situations tend to come up: discovering that the person who died had undeclared rental income of their own, and working out your own tax position once you become the new landlord. Both are manageable, but each involves a slightly different process.

Inherited a rental property and not sure where the tax position stands? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Situation One: The Deceased Had Undeclared Rental Income

If, while dealing with the estate, you discover that the person who died had rental income that was never declared to HMRC during their lifetime, this generally becomes a matter for the estate to resolve, typically handled by the executor or personal representative as part of the estate administration process. This isn’t the same as the beneficiary’s own Let Property Campaign disclosure — it relates to the deceased’s own historic tax position and is generally corrected before the estate can be finalised and distributed to beneficiaries.

Executors have a legal duty to ensure the deceased’s tax affairs are in order before completing the estate administration, and outstanding tax liabilities, including undeclared rental income, are generally paid from the estate’s assets before distribution. If this is discovered, it’s worth addressing it promptly, since delaying can hold up probate and the eventual distribution of the estate to beneficiaries.

Situation Two: Your Own Rental Income From an Inherited Property

If you’ve inherited a property and decided to keep letting it out, you become responsible for reporting the rental income from the date you inherited it — typically the date of death, or the date the property was formally transferred to you, depending on the specific circumstances of the estate administration. This is exactly the kind of situation that creates “accidental landlords,” and it’s a common pathway into needing a Let Property Campaign disclosure a few years down the line if the reporting obligation wasn’t recognised at the time. Our guide on being an accidental landlord covers this pattern more generally.

Why Beneficiaries Sometimes Miss This Obligation

It’s genuinely easy to overlook. Many beneficiaries inherit a share of a property alongside other assets and don’t think of themselves as “becoming a landlord” in any formal sense, particularly where a letting agent continues managing the property much as before. But from a tax perspective, inheriting a share of a let property and continuing to receive rental income creates the same reporting obligation as buying a rental property outright.

The Probate Value and Its Relevance

When a property is inherited, its market value at the date of death (the “probate value”) becomes the new base cost for Capital Gains Tax purposes for the beneficiary — this is a completely separate matter from Income Tax on rental profits, but it’s worth understanding both together since they often surface at the same time. If the property is later sold, Capital Gains Tax is calculated based on the increase in value from the probate value, not from whatever the original deceased owner originally paid for it.

What If the Property Is Jointly Inherited?

Where a property is inherited by multiple beneficiaries — siblings, for example — each beneficiary is generally responsible for reporting their own share of the rental income, based on their share of the inheritance. This is similar in principle to any other jointly owned property, and each beneficiary would typically need to consider their own disclosure if the income wasn’t reported from the start.

Working Out How Many Years Are Involved

If you’ve been receiving rental income from an inherited property for several years without declaring it, the look-back period generally follows the same principles as any other Let Property Campaign disclosure — based on the reason for non-disclosure rather than the fact that the property was inherited. Our guide on how many years you need to declare explains this in more detail. Genuinely not realising that inheriting a share of a let property created a personal reporting obligation is a common and understandable scenario, and typically falls into the more lenient end of the behaviour spectrum, provided the disclosure is made voluntarily once identified.

Inheritance Tax Considerations Alongside Income Tax

Separately from the ongoing rental income question, inherited property is often relevant to the estate’s Inheritance Tax position, and if the property continues to generate income for the estate before it’s formally distributed, that income may need to be reported by the estate itself during the administration period. Our guides on Inheritance Tax planning for property owners and IHT and trust planning cover this wider context.

What Records You’ll Need

  • The grant of probate and the date the property was formally inherited or transferred
  • The probate value of the property, for future Capital Gains Tax purposes
  • Rental income and expense records from the date you began receiving income personally
  • Details of any co-beneficiaries and their respective shares, if the property is jointly inherited

Our record keeping guide covers the broader documentation landlords should retain.

How Felix Accountants Can Help

We help beneficiaries work through both sides of this situation — resolving a deceased relative’s historic undeclared rental income as part of estate administration, and establishing your own correct tax position going forward if you’ve continued to let an inherited property. Both situations are common, manageable, and rarely as complicated as they first feel once someone experienced walks you through the specifics.

Frequently Asked Questions

Who is responsible for a deceased person’s undeclared rental income?

This generally becomes a matter for the estate, typically handled by the executor as part of finalising the deceased’s tax affairs before the estate is distributed to beneficiaries.

Do I need to declare rental income from a property I inherited but haven’t sold?

Yes, if you’re receiving rental income from the property, you’re responsible for reporting it from the point you inherited it, in the same way as any other rental property you own.

What is the probate value and why does it matter?

It’s the property’s market value at the date of death, which becomes your new base cost for Capital Gains Tax purposes if you later sell the property.

If several siblings inherit a property together, who reports the rental income?

Each beneficiary is generally responsible for reporting their own share of the rental income, based on their share of the inheritance.

Is it common for beneficiaries to genuinely not realise they need to declare this income?

Yes, this is a common and understandable situation, particularly where a letting agent continues managing the property. Coming forward voluntarily once you realise is generally treated favourably.

Let’s work through your inherited property’s tax position. Book your free 15-minute consultation with Felix Accountants.