Categories
Articles Articles Blogs Let Property Campaign

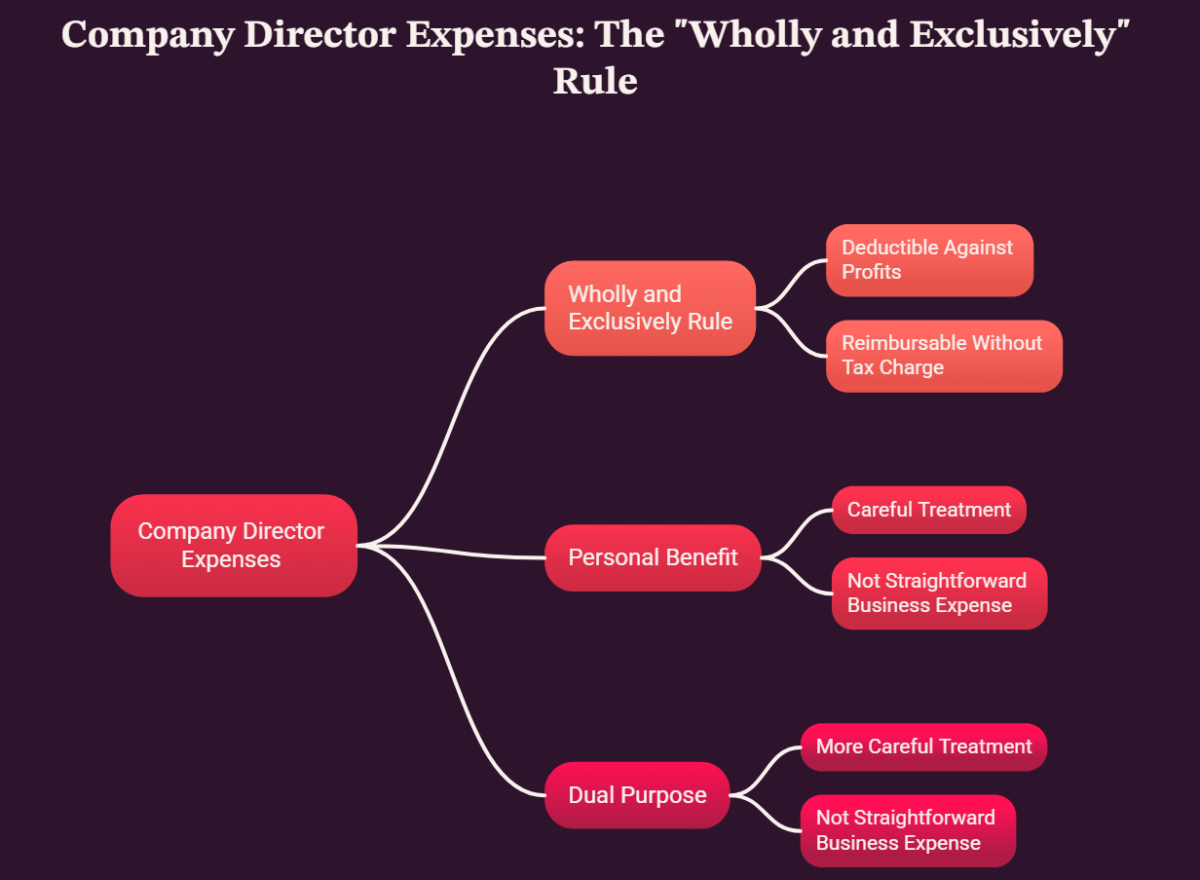
Corporation Tax and Director Expenses: Which Costs Can Your Company Reimburse?

One of the most common questions from new company directors is deceptively simple: what can I actually claim back from my own company? The underlying rule is straightforward in principle — expenses must be incurred “wholly and exclusively” for business purposes — but applying it in practice, especially where personal and business use overlap, is where most of the genuine complexity lives.

Not sure which of your costs your company can reimburse? Book a free 15-minute consultation with Felix Accountants. Book your free call here.

The “Wholly and Exclusively” Rule

For a cost to be deductible against company profits (reducing Corporation Tax) and reimbursable to a director without creating a personal tax charge, it generally needs to have been incurred wholly and exclusively for the purposes of the company’s trade. Costs with any significant personal benefit or dual purpose need much more careful treatment, and some can’t be claimed as a straightforward business expense at all, even if there’s a genuine business element involved. Our full guide on allowable limited company expenses covers the general framework this sits within.

Straightforward Reimbursable Expenses

These generally cause few complications, as long as they’re genuinely business-related:

  • Travel costs for business journeys (excluding ordinary commuting to a permanent workplace)
  • Business mileage, using HMRC’s approved mileage rates when using a personal vehicle for company business
  • Accommodation and subsistence costs while travelling for business
  • Professional subscriptions and memberships relevant to the trade
  • Office supplies, software subscriptions, and equipment used for the business
  • Business insurance premiums
  • Training costs directly relevant to the role, in most circumstances

Our guide on claiming business mileage from your own company covers the specific approved mileage rates and record-keeping needed to support this particular claim.

Working From Home

Directors working from home can generally claim a modest, flat-rate contribution toward household costs, or a more detailed calculation based on actual additional costs (such as extra heating and electricity) attributable to business use of part of the home, provided it’s calculated on a reasonable, defensible basis rather than an arbitrary figure.

Company Cars: A More Complicated Area

Company cars are one of the most commonly misunderstood areas of director expenses. If a company provides a car that’s available for the director’s personal use (not just business use), this generally creates a taxable “benefit in kind,” reported on a P11D, with the director paying Income Tax on the benefit and the company paying Class 1A National Insurance. The tax cost of this varies significantly depending on the car’s list price and CO2 emissions, which is why fully electric or low-emission vehicles are often considerably more tax-efficient as a company car than a typical petrol or diesel model. Our guide on running your car in a tax-effective way covers this comparison in more detail, including when using your own car and claiming mileage is more efficient than a company-provided vehicle.

Business Entertainment: Generally Not Deductible

This catches a lot of directors out. Client entertainment costs — taking a client to dinner, for example — are generally not deductible against Corporation Tax at all, even though they’re a genuine, arguably necessary business cost. This is a specific, long-standing exclusion in the tax rules, distinct from the general “wholly and exclusively” test that governs most other expenses. Staff entertainment, by contrast, can qualify for a specific annual exemption (subject to a per-head limit) for events such as a Christmas party, provided the conditions are met.

Home-to-Work Travel

Ordinary commuting between home and a permanent workplace generally isn’t a deductible business expense, regardless of the distance involved. This is one of the more counter-intuitive rules for new directors, particularly where a director works primarily from a home office but occasionally travels to a separate business premises — the specific facts of where the “permanent workplace” is considered to be can significantly affect what’s claimable.

Reimbursing Genuine Personal Expenditure With a Business Element

Where a cost has both a business and personal element — a broadband contract used for both work and personal browsing, for example — only the business proportion can generally be claimed, and it needs to be calculated on a reasonable, justifiable basis. Claiming the full cost of something with genuine dual use, rather than an apportioned business element, is a common area where directors inadvertently create a benefit in kind or an incorrect Corporation Tax deduction.

What Happens When Something Isn’t a Clean Business Expense?

Where a cost doesn’t meet the wholly-and-exclusively test, or has a personal benefit element, it typically falls into one of a few categories:

  • Taxable benefit in kind: reported on a P11D, with Income Tax paid by the director and Class 1A National Insurance paid by the company
  • Not deductible for Corporation Tax at all: some costs, like client entertainment, simply aren’t allowable regardless of how they’re reimbursed
  • Treated as a dividend or salary: if a payment doesn’t fit any genuine expense category, it may need to be treated as personal income instead, with the corresponding tax treatment

Keeping the Right Records

Whatever the expense, clear supporting records matter — receipts, a note of the business purpose, and (for mixed-use costs) a documented basis for the apportionment. This protects both the Corporation Tax deduction and the director’s personal tax position if HMRC ever asks questions about a specific claim.

Pension Contributions: A Particularly Tax-Efficient Option

Separately from routine expense reimbursement, company pension contributions made directly on a director’s behalf are generally a deductible business expense for the company and don’t create a personal Income Tax or National Insurance charge for the director, making this one of the more tax-efficient ways to extract value from company profits. Our guide on using pension contributions for tax relief covers this in more detail.
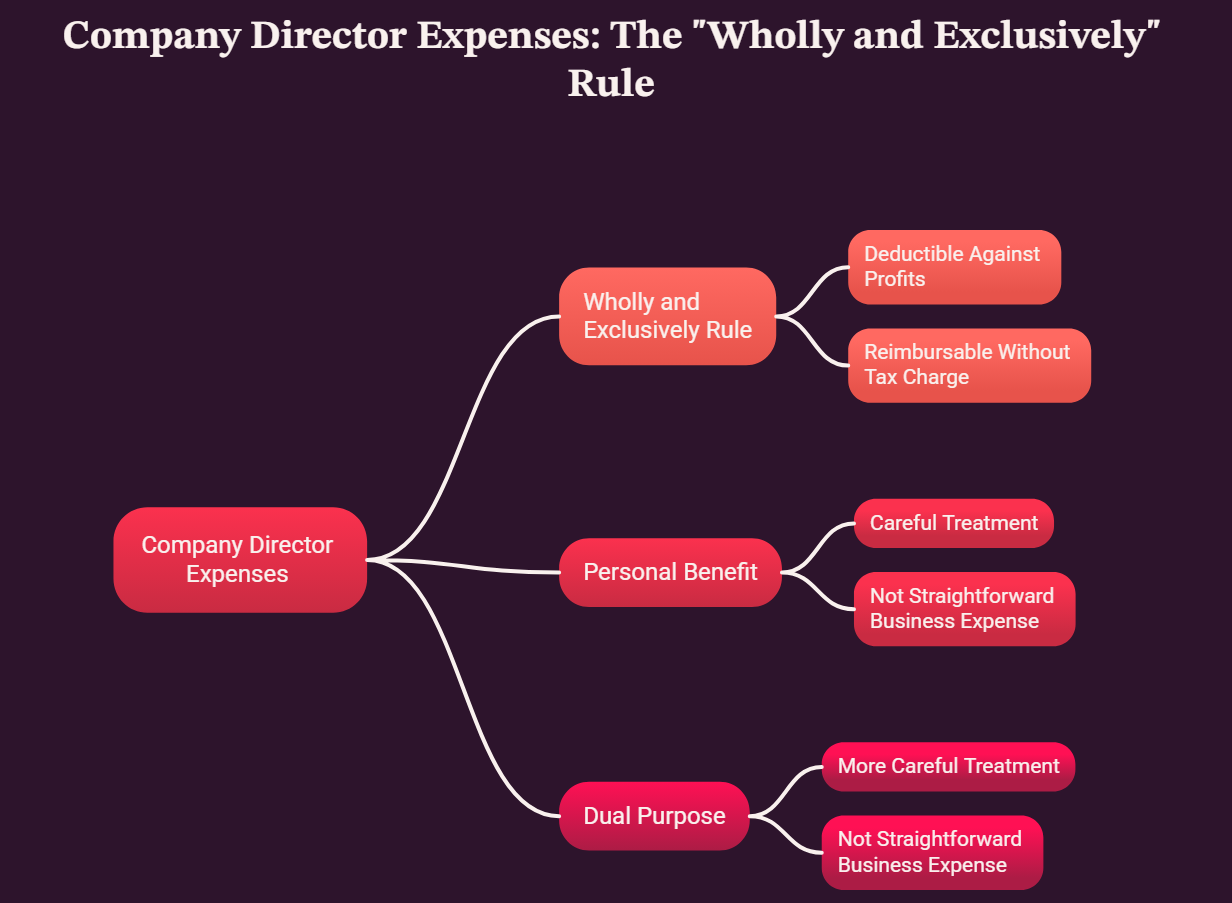
wholly and exclusively

How Felix Accountants Can Help

We help directors work out exactly what can be reimbursed cleanly, what needs to go through P11D reporting, and how to structure genuinely mixed-use costs correctly. See our wider business tax services for how this fits into your company’s broader Corporation Tax position.

Frequently Asked Questions

Can my company pay for my commute to the office?

Generally no. Ordinary commuting between home and a permanent workplace isn’t a deductible business expense, regardless of distance.

Can I claim client entertainment as a business expense?

No, client entertainment costs are generally not deductible for Corporation Tax purposes, even though they’re a genuine business activity.

What happens if my company provides me with a car I can use personally?

This generally creates a taxable benefit in kind, reported on a P11D, with Income Tax paid by you and Class 1A National Insurance paid by the company, based on the car’s list price and emissions.

Can I claim the full cost of my home broadband if I use it for work?

Only the business-use proportion is generally claimable, calculated on a reasonable, justifiable basis, rather than the full personal and business cost combined.

Is it better to have a company car or claim mileage using my own car?

It depends on the specific vehicle, its emissions, and how much personal use is involved — for many directors, using a personal car and claiming approved mileage rates is more tax-efficient than a company-provided car, particularly for higher-emission vehicles.

Let’s clarify exactly what your company can reimburse. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Blogs Let Property Campaign News

What Should You Do If You Cannot Reconstruct Your Rental Income?

If you have realised you owe tax on rental income but your records are incomplete, perhaps because bank statements have been lost, rent was paid in cash or a letting agent has since closed, it does not prevent you from using the Let Property Campaign. HMRC’s own guidance says that where records are incomplete you should make your best estimate of the undisclosed income and be ready to explain how you arrived at it. The real task is producing an estimate that is reasonable, well evidenced and complete enough for HMRC to accept.

Missing records? Talk it through before you estimate.

Every gap in the paperwork can usually be approached in more than one way. Book a free 15-minute consultation with Felix Accountants to discuss what records you still have, what can be recovered and how a defensible estimate might be built for your disclosure.

Can You Make a Let Property Campaign Disclosure Without Full Records?

Yes. The HMRC Let Property Campaign guidance specifically addresses landlords who do not have all the business records they need. In summary, HMRC says:

  • if records are incomplete, you should make your best estimate of the undisclosed income and gains;
  • HMRC may ask you to explain how you worked out any estimates, so you should keep your calculations;
  • bank statements for the disclosure period will probably help, and if you do not have them you should contact your bank as soon as possible for copies;
  • if copy statements cannot be obtained at all, you can use more recent statements as a guide to income and expenditure, although HMRC may ask why earlier statements were unavailable.

In other words, missing records change how you calculate the figures, not whether you can come forward. What HMRC will not accept is a disclosure that is materially incorrect or incomplete. If you are new to the process, our step-by-step guide to the LPC disclosure process explains the notification and disclosure stages in more detail.

Why “I Can’t Reconstruct It” Is Rarely the Full Story

Most landlords who say they cannot reconstruct their rental income actually mean they cannot reconstruct it exactly. That is a very different position from having no information at all. You almost always know some of the following:

  • when you bought or inherited the property and when you first let it;
  • roughly what rent was agreed, and when it changed;
  • whether the property was ever empty, used by family or sold;
  • whether an agent was involved and what percentage they charged.

Those facts, combined with whatever third-party evidence can still be recovered, are usually enough to produce a credible year-by-year estimate. The aim is not perfection. It is a figure that a reasonable person, looking at your working papers, would accept as a fair reflection of what happened.

Step 1: Build a Timeline of What You Do Know

Before looking for documents, write down the history of each property. A simple timeline often reveals which years are genuinely uncertain and which are not.

  1. Ownership: purchase or inheritance date, your ownership share and any joint owners.
  2. Letting periods: the date each tenancy started and ended, including renewals.
  3. Rent levels: the agreed monthly rent at each point and when it increased.
  4. Voids and non-letting periods: times the property was empty, being refurbished or occupied by you or family.
  5. Management: whether you self-managed or used an agent, and the agent’s fee basis.
  6. Finance: the mortgage lender, loan amount and whether the mortgage was repayment or interest-only.

Remember that joint owners each make their own disclosure. HMRC’s guidance confirms that a disclosure cannot include details for more than one person, so a married couple with a jointly owned property would each disclose their own share.

Step 2: Recover Third-Party Evidence

Evidence created by someone else carries more weight than figures produced from memory. The table below shows common sources and what they can help establish.

Record every request you make, including the date and the response. If a bank or agent tells you records no longer exist, keep that reply. It helps answer the question HMRC is likely to ask about why the evidence is unavailable. Good habits from here on matter too; our guide to keeping proper business records covers what to retain going forward.

Step 3: Choose a Reasonable Estimation Method

There is no single prescribed formula. The right method depends on what evidence survives. In practice, one or more of the following approaches is usually used, and combining them gives a useful cross-check.

Extrapolating from years where records exist

If you have reliable figures for recent years, those can be used as a guide to earlier years, adjusted for known changes such as rent increases, voids or a change of agent. This mirrors HMRC’s own suggestion of using more recent statements where older ones cannot be obtained.

Using the contractual rent and occupancy periods

Where tenancy agreements survive but bank records do not, rental income can be estimated by multiplying the agreed rent by the months the property was actually let. Any arrears you genuinely never received, or periods when the property was empty, should be supported by whatever evidence exists.

Cross-checking against local market rents

If no agreements exist for a period, the typical rent for a comparable property in the same area at that time can be used as a sense check. It should not be used to understate income. If the market suggests a higher figure than your recollection, you need a clear reason for using the lower one.

Estimating expenses with extra care

Expenses deserve more caution than income. An estimate that inflates income is rarely challenged; an estimate that inflates costs often is. Claim costs you can reasonably support, such as agent fees at an evidenced percentage, insurance premiums confirmed by the insurer, or mortgage interest from lender statements. Only allowable property expenses can be deducted, and you cannot claim any expense already claimed against income previously reported to HMRC.

Mortgage interest also needs care across different years. For individual landlords, relief for residential finance costs was restricted in stages from 2017-18, and from 2020-21 onwards it is given as a basic rate tax reduction rather than a deduction from rental profit. Mortgage capital repayments are never deductible.

A Worked Example

A landlord has let a flat since spring 2016 but never registered for Self Assessment. Their bank only provides statements back to 2020. However, they still hold the original tenancy agreement at £850 per month, a 2019 renewal at £900 per month and an agent’s terms of business showing a 10% management fee. A council tax bill shows the flat was empty for two months in 2018.

PeriodEvidence availableEstimation approach
2016 to 2019Original tenancy agreement, agent terms, council tax bill£850 x months let, less the evidenced two-month void; agent fee at 10%
2019 to 2020Renewal agreement£900 x months let; agent fee at 10%
2020 onwardsBank statements, agent remittancesActual figures from statements; used to sense-check earlier estimates

Because this landlord never notified HMRC, the disclosure may need to go back to when the letting began, subject to the maximum periods explained in our guide on how many years of rental income landlords must disclose. Every assumption above would be written into a short explanatory note kept with the working papers.

Document Your Estimates Properly

An estimate without an explanation looks like a guess. An estimate with an explanation looks like a considered calculation. We recommend preparing a short “basis of preparation” note for each property, covering:

  • which years are based on actual records and which are estimated;
  • the method used for each estimated period and why it was chosen;
  • the evidence relied on, with copies kept on file;
  • the steps taken to recover missing records and the responses received;
  • any assumptions made where the method could have produced a range, and why the figure used is reasonable.

Keep this note even after HMRC accepts your disclosure. If HMRC later asks how a figure was calculated, you will be able to answer quickly and consistently.

Common Mistakes When Records Are Missing

  • Estimating on the low side. An optimistic estimate can make the whole disclosure look incomplete. If there is a genuine range, the figure you use should be one you can justify.
  • Ignoring cash rent. Cash received and never banked is still taxable income and should be included.
  • Leaving out other undisclosed income. The campaign requires you to include other income and gains you have not told HMRC about, such as untaxed interest or gains on property sales.
  • Double counting. Income already declared on a tax return should not be included again, and expenses already claimed cannot be claimed twice.
  • Claiming mortgage capital. Only the interest element can attract relief, and the way relief is given depends on the tax year.
  • Waiting too long to start. Once HMRC acknowledges your notification, you have 90 days to disclose and pay. Record requests to banks can take weeks, so they should be made immediately. Our 90-day deadline preparation guide sets out a practical timetable.
  • Choosing a behaviour category that does not fit the facts. Whether the error was careless or deliberate affects both the number of years and the penalty, and it must reflect what actually happened.

How Penalties and Interest Apply to Estimated Figures

Estimated figures are treated in the same way as actual figures. Interest runs from the date the tax should have been paid, and penalties are calculated as a percentage of the additional tax. HMRC’s fact sheets on penalties for inaccuracies and penalties for failure to notify explain the ranges and reductions. The quality of your disclosure, including how openly you explain any estimates, is one of the factors that affects the reduction available. You can read more in our article on Let Property Campaign penalties.

HMRC also publishes a tax, interest and penalties calculator that can help once the tax for each year has been worked out manually.

What If HMRC Questions Your Figures?

HMRC expects most disclosures to be self-explanatory, but it may contact you or your adviser to clarify points or ask for evidence. Full co-operation is a condition of the campaign. If you have kept clear working papers, answering these questions is usually straightforward.

If, after submitting, you realise something has been missed, HMRC’s guidance says you should contact them immediately to amend the disclosure. Disclosures later found to be materially incorrect are likely to attract significantly higher penalties, which is another reason to take care with estimates at the outset.

How Felix Accountants Can Help

Reconstructing rental income is part detective work and part tax calculation. At Felix Accountants, we help landlords identify which records can still be recovered, choose an appropriate estimation method for each period, prepare year-by-year computations and write the explanatory notes that support the figures. Our Let Property Campaign disclosure service covers the process from notification through to HMRC’s acceptance letter, and our article on why specialist Let Property Campaign advice matters explains where professional input tends to make the biggest difference.

Unsure whether your records are good enough to disclose? Arrange a free 15-minute call and we will talk through your situation in confidence.

Let Property Campaign

Missing records are a common obstacle, but they are not a reason to delay. HMRC’s guidance allows a best estimate, provided it is reasonable, supported by whatever evidence can be recovered and explained clearly. Start by building a timeline, request third-party records straight away, choose a sensible method for each gap and document every assumption. That approach gives your disclosure the best chance of being accepted without further enquiry.

Frequently Asked Questions

Can I use the Let Property Campaign if I have no bank statements?

Yes. HMRC’s guidance says you should make your best estimate where records are incomplete. Request copies from your bank first. If they cannot be obtained, more recent statements can be used as a guide, but HMRC may ask why the older statements were unavailable.

Will HMRC accept estimated rental income?

HMRC’s guidance allows estimates where records are incomplete, but they must be reasonable and you should keep your calculations, because HMRC may ask how you worked them out. Disclosures that are materially incorrect or incomplete are unlikely to be accepted.

How do I estimate rent if I have lost my tenancy agreements?

Other evidence can often fill the gap, such as deposit protection records, agent correspondence, messages with tenants or bank entries. Local market rents for similar properties at the time can be used as a cross-check, but should not be used to understate income.

Can I claim expenses if I do not have receipts?

Allowable expenses can sometimes be estimated where there is reasonable supporting evidence, such as insurer confirmations, lender statements or an agent’s fee terms. Expense estimates attract more scrutiny than income estimates, so claims should be cautious and well explained.

Does having incomplete records affect my penalty?

Penalties depend mainly on your behaviour and whether the disclosure is unprompted. However, the quality of your disclosure, including how openly you explain estimates and co-operate with HMRC, affects the reductions available.

Do joint owners need separate disclosures?

Yes. HMRC’s guidance states that a disclosure cannot include details for more than one person, so each joint owner discloses their own share of the income and needs their own notification.

Categories
News

How Face to Face Accounting Support Builds Trust

Dealing with undeclared rental income or an HMRC property tax disclosure can feel overwhelming, particularly when you are uncertain about what you owe or how to put things right. At Felix Accountants, we believe that professional Property tax disclosure accountant advice should not only help clients meet their obligations but also give them the confidence and reassurance they need. As one of our clients, Karan, highlighted in his testimonial, having a real person to speak to face-to-face can make a significant difference.

Worried about undeclared rental income or an HMRC property disclosure?

Speak directly with Felix Accountants about your situation. For example Book your free 15-minute consultation to discuss your concerns and understand your next steps.

Why Property Tax Disclosure Can Be Stressful

Many landlords discover that they should have declared rental income from previous years but are unsure how to correct the position. Others receive correspondence from HMRC and worry about the potential financial consequences.

Common concerns include:

  • Not knowing which years of rental income need to be disclosed.
  • Uncertainty about allowable property expenses and tax calculations.
  • Concerns about HMRC penalties and interest.
  • Not knowing how to approach HMRC or respond to enquiries.
  • Fear of making an error that creates further problems.

These concerns are understandable. Property taxation involves detailed rules, and mistakes can have financial consequences. However, the right professional guidance can help make the process clearer and more manageable.

What Karan’s Experience Tells Us About Personal Accounting Support

In his testimonial, Karan emphasised the importance of personal interaction and the comfort that came from discussing his situation directly with his accountant.

Rather than relying entirely on telephone calls or written correspondence, he valued the opportunity for a face-to-face conversation.

His experience highlights three important qualities clients often look for in an accountant: accessibility, transparency and reassurance.

1. Face-to-Face Conversations Help Build Trust

Tax disclosures can involve sensitive personal and financial information. Clients may be concerned about past mistakes or uncertain about what to reveal.

Speaking directly to an accountant allows them to explain their circumstances, ask questions and better understand the proposed approach.

For Karan, this direct interaction helped establish comfort and confidence.

At Felix Accountants, we recognise that building trust is particularly important when clients are dealing with challenging HMRC matters.

2. Straightforward Advice Makes Complex Matters Easier

Another important theme from Karan’s feedback was simplicity. He described the service as “simple” and “up front”.

These are important qualities in tax advice. Clients should understand what information is required, what their accountant is doing and what happens next.

Our approach is to explain complicated accounting and tax matters in plain English, providing practical guidance rather than unnecessary jargon.

For a landlord facing a disclosure, this might involve explaining how rental profits are calculated, which expenses may qualify for tax relief and how the disclosure process works.

3. Professional Support Can Reduce Stress and Worry

One of the strongest messages from Karan’s testimonial was that the support he received helped reduce the stress associated with his situation.

When clients understand the process and feel comfortable speaking to their accountant, they can approach difficult financial matters with greater confidence.

Professional assistance cannot guarantee a particular HMRC outcome, but it can help clients understand their obligations, prepare accurate information and avoid unnecessary confusion.

Why Personal Service Matters When Dealing with HMRC

HMRC disclosures are not always straightforward. Each case depends on the taxpayer’s circumstances, the years involved, the available records and the reasons income was not previously declared.

A personal accounting service provides an opportunity to consider these details rather than applying the same approach to every client.

At Felix Accountants, our property disclosure support can include:

  • Reviewing the client’s rental income and tax history.
  • Identifying relevant tax years and potential reporting errors.
  • Reviewing allowable expenses and calculating rental profits.
  • Preparing disclosure calculations and supporting schedules.
  • Assisting with HMRC correspondence and disclosure submissions.
  • Explaining potential tax, interest and penalty implications.
  • Supporting clients with payment arrangements where appropriate.

Our objective is to provide accurate advice while keeping clients informed throughout the process.

How the HMRC Let Property Campaign Works

The HMRC Let Property Campaign provides a route for individual landlords to disclose unpaid tax relating to residential letting income.

It may be relevant to landlords who have failed to declare rental income from a single property, several properties or certain other residential letting arrangements.

According to HMRC’s official Let Property Campaign guidance, taxpayers generally begin by notifying HMRC of their intention to make a disclosure.

After receiving HMRC’s acknowledgement, they normally have 90 days to prepare and submit their disclosure and pay the amount due, or make acceptable payment arrangements.

The amount of historical tax that must be disclosed will depend on the circumstances, including why the original reporting error occurred.

This is where specialist support can be valuable. An accountant experienced in rental income disclosures can help review the records and explain the appropriate approach.

The Value of Working with a Smaller Accountancy Firm

For many landlords and small business owners, the relationship with their accountant is as important as the technical service being provided.

Smaller firms can offer a personal approach built around understanding individual circumstances.

At Felix Accountants, we aim to combine professional expertise with clear communication and accessible support.

This means clients can discuss their concerns, understand the work being undertaken and ask questions as their circumstances develop.

Karan’s feedback reinforces why this approach matters. He valued the personal interaction and felt comfortable recommending the service.

What Should You Look for in a Property Disclosure Accountant?

If you are considering appointing an accountant to help with undeclared rental income, look beyond the initial fee.

Consider whether the accountant:

  • Understands property taxation: They should have relevant experience with rental income, allowable expenses and HMRC disclosure procedures.
  • Communicates clearly: You should understand the process and the advice being provided.
  • Is transparent about fees: The scope of work and charging arrangements should be explained upfront.
  • Offers personal support: You should have opportunities to discuss your particular circumstances.
  • Explains potential risks: A good adviser should give a realistic explanation of possible outcomes rather than make guarantees.

Choosing an accountant who combines technical knowledge with personal attention can make a complicated process considerably easier to navigate.

How Felix Accountants Can Help

Felix Accountants provides accounting and tax support to landlords, property investors and small business owners across the UK.

We understand that clients seeking help with historical rental income may be experiencing uncertainty, embarrassment or concerns about HMRC.

Our approach is professional, straightforward and non-judgemental. We focus on understanding the facts, explaining the available options and helping clients take appropriate action.

Whether you have received an HMRC letter or have independently realised that rental income may not have been declared, seeking advice early can help you understand your position.

Need help putting your property tax affairs in order?

Felix Accountants can discuss your circumstances and explain how professional disclosure support may help. Schedule your free 15-minute consultation today.

How Face to Face Accounting Support Builds Trust
Property tax disclosure

Frequently Asked Questions

Can an accountant help me disclose undeclared rental income?

Yes. An accountant can help review your rental records, calculate relevant tax liabilities, prepare disclosure information and communicate with HMRC on your behalf where authorised.

Do I need to meet my accountant face-to-face?

No. Many tax matters can be handled remotely. However, some clients prefer face-to-face meetings because they provide a more personal opportunity to discuss sensitive issues and ask questions.

Will HMRC charge penalties if I voluntarily disclose rental income?

Penalties depend on the circumstances of the failure, including the taxpayer’s behaviour and the quality of the disclosure. Voluntary disclosure may result in more favourable penalty treatment than waiting for HMRC to discover the issue, but no particular outcome is guaranteed.

How long does an HMRC Let Property Campaign disclosure take?

Under the campaign, taxpayers generally have 90 days from HMRC’s acknowledgement of their notification to submit their disclosure and arrange payment. HMRC’s subsequent review and closure times can vary.

Can Felix Accountants help if HMRC has already contacted me?

Yes. Felix Accountants can review the correspondence, assess the circumstances and advise on the appropriate next steps. The disclosure route and possible penalty treatment will depend on what HMRC has already communicated.

Good Accounting Support Is About More Than Numbers

Karan’s testimonial highlights something important: people do not simply want an accountant who understands tax. They also want someone who listens, explains matters clearly and makes them feel comfortable discussing difficult financial concerns.

For clients facing property tax disclosure issues, this combination of professional expertise and personal support can make a meaningful difference.

At Felix Accountants, we believe that transparency, accessibility and straightforward advice should be at the heart of every client relationship.

If you are concerned about undeclared rental income or an HMRC property disclosure, book a free 15-minute consultation with Felix Accountants to discuss your circumstances.

Categories
Articles Articles Blogs Let Property Campaign

VAT Invoices: What Information Must a UK VAT Invoice Contain?

Not every invoice a VAT-registered business sends out is automatically a valid “VAT invoice” in HMRC’s eyes — and if it isn’t, your customer may not be able to reclaim the VAT they’ve paid you, which can quickly become an awkward conversation. Getting the format right isn’t complicated once you know the rules, but missing even one required field can cause real problems for your customer’s VAT recovery.

Want your invoice templates checked for VAT compliance? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
When Do You Need to Issue a VAT Invoice?

Once your business is VAT-registered, you must issue a compliant VAT invoice for every standard-rated, reduced-rated or zero-rated sale, regardless of your business structure. For B2B transactions between VAT-registered businesses, a full VAT invoice is generally expected as standard. For retail sales directly to consumers, you’re not always required to issue one automatically, but if a VAT-registered customer asks for one in order to reclaim input VAT, you’re required to provide it.

The Three Types of VAT Invoice

HMRC recognises three formats, and which applies depends on the value of the supply:

  • Full VAT invoice: required for supplies where the total, including VAT, exceeds £250
  • Simplified VAT invoice: permitted for supplies totalling £250 or less, including VAT
  • Modified VAT invoice: used for certain retail supplies over £250, showing VAT-inclusive line amounts rather than net amounts, generally with the customer’s agreement

It’s worth flagging that the £250 threshold is VAT-inclusive, not the net figure — a gross total of £250.01 pushes you into full invoice territory, with no rounding tolerance.

What a Full VAT Invoice Must Include

A full VAT invoice needs to contain all of the following:

  • A unique, sequential invoice number
  • The date of issue and the tax point (the time of supply, which determines which VAT period the sale falls into)
  • Your business name, address, and VAT registration number
  • Your customer’s name and address
  • A description of the goods or services supplied
  • For each line item: the quantity, the unit price excluding VAT, the applicable VAT rate, and the amount payable excluding VAT
  • The rate of any cash or early payment discount offered
  • The total amount payable, excluding VAT
  • The total amount of VAT charged, shown in sterling

If a single invoice covers items at more than one VAT rate — say, some standard-rated and some zero-rated goods — each rate needs to be shown separately, with its own net amount and VAT amount, rather than a single blended figure.

What a Simplified VAT Invoice Must Include

For supplies of £250 or less, a simplified invoice requires considerably fewer fields:

  • Your business name, address, and VAT registration number
  • The date (time) of supply
  • A description of the goods or services
  • The VAT rate charged per item
  • The total amount payable, including VAT

Notably, a simplified invoice doesn’t need to show the customer’s name and address, or a separate net-of-VAT figure — this is why till receipts and hospitality bills, for smaller transactions, are usually valid VAT documents without the full level of detail. Exempt supplies shouldn’t be included on a simplified invoice alongside taxable ones.

What a Modified VAT Invoice Must Include

A modified invoice is used for larger retail supplies (over £250) where the retailer’s systems are set up to show VAT-inclusive amounts rather than net figures. It includes the same information as a full VAT invoice, but line items and totals are shown inclusive of VAT, alongside a clear statement of the total amount including VAT.

Common Reasons a VAT Invoice Gets Rejected

  • Missing or incorrect VAT registration number
  • Address details for either party incomplete or missing entirely
  • VAT shown as a single blended figure where multiple rates actually applied
  • No unique invoice number, or duplicated numbering across different periods
  • The tax point date missing, or clearly inconsistent with when the supply actually took place

Any of these can give HMRC grounds to challenge input VAT recovery for the recipient, which is why it’s worth periodically checking your invoice template against the current requirements rather than assuming it’s still correct.

Invoice Numbering

Every VAT invoice needs a unique, sequential number. If you restart your numbering each calendar year without a distinguishing prefix, you risk creating duplicate invoice numbers across different years, which can cause confusion in your own records as well as HMRC’s. Using a consistent prefix (such as the year, or a customer reference) alongside a running sequence avoids this problem.

Documents That Are Not Valid VAT Invoices

It’s worth being clear that a pro-formal invoice, a statement of account, or a delivery note are not acceptable substitutes for a proper VAT invoice — HMRC doesn’t accept these as valid evidence for reclaiming input VAT, regardless of how much detail they contain. If you’re issuing a pro-formal ahead of a formal invoice, make sure it’s clearly labelled as such and followed up with a genuine VAT invoice once payment terms are agreed.

Timing: When Must You Issue the Invoice?

VAT invoices generally need to be issued within 30 days of the time of supply (the tax point), which is usually the earlier of the date goods or services were provided, or the date payment was received, subject to specific rules for certain types of supply.

VAT Invoices and Making Tax Digital

Regardless of invoice format, VAT-registered businesses need to keep digital records of their sales and purchases under Making Tax Digital, with invoice data typically flowing into MTD-compatible accounting software rather than being tracked manually alongside a separate digital record.

What If You’re Selling Property or Involved in Property Development?

VAT treatment for property transactions has its own additional complexities on top of the standard invoicing rules described here, particularly around whether a supply is standard-rated, zero-rated, or exempt. Our guides on VAT and property in the UK and VAT implications for property developers and investors cover this in more detail if your invoicing involves property transactions specifically.

How Felix Accountants Can Help

We help VAT-registered businesses review and correct their invoice templates, make sure the right format is used for the right transaction value, and set up systems that keep invoicing compliant as your business grows. See our wider taxation services for how accurate VAT invoicing fits into your broader compliance position.

Frequently Asked Questions

What’s the difference between a full and simplified VAT invoice?

A full VAT invoice is required for supplies over £250 (including VAT) and needs the customer’s details plus a full breakdown of net, VAT, and total amounts. A simplified invoice, for £250 or less, needs fewer fields and doesn’t require the customer’s name and address.

Do I need to issue a VAT invoice for every sale?

You must for B2B transactions with other VAT-registered businesses. For retail sales to consumers, it’s not always automatic, but you must provide one if a VAT-registered customer asks for it.

Can I use a pro-formal invoice to reclaim VAT?

No. HMRC doesn’t accept pro-formal invoices, statements, or delivery notes as valid VAT invoices for reclaiming input tax.

What happens if my VAT invoice is missing required information?

HMRC can refuse the recipient’s input VAT recovery if the invoice doesn’t meet the required format, so it’s worth checking your templates carefully against the current requirements.

How soon after a sale must I issue a VAT invoice?

Generally within 30 days of the time of supply (the tax point), which is usually the earlier of the goods/services being provided or payment being received.

Let’s get your invoice templates HMRC-compliant. Book your free 15-minute consultation with Felix Accountants.
Categories
News

Could HMRC Find Your Undeclared Rental Income?

Could HMRC Find Your Undeclared Rental Income

Felix & Co HMRC Free Let Property Campaign Guide

COULD HMRC FIND YOUR UNDECLARED RENTAL INCOME? What Every Landlord Should Know Before HMRC Asks the Question First

Could HMRC Find Your Undeclared Rental Income?

If you haven’t told HMRC about some, or all, of your rental income, it is worth asking a harder question: how would HMRC actually find out? This free guide from Felix & Co Chartered Accountants explains where HMRC gets its information, the mistakes that quietly turn ordinary landlords into disclosure cases, and what to do before HMRC raises the question for you.

Prefer to talk it through first? Speak directly with a Chartered Certified Accountant about your rental income.

Book Your Free 15-Minute Consultation →

How HMRC Actually Finds Undeclared Rental Income

It is a common assumption: if a landlord hasn’t told HMRC about their rental income, HMRC has no way of knowing. In reality, HMRC has access to an increasing range of data sources, and uses automated systems to cross-check them against the Self Assessment returns it already holds.

  • Land Registry records showing who owns which property
  • Letting agent data and information from property listing platforms
  • Bank and financial institution information
  • Information shared by overseas tax authorities under international agreements
  • Mortgage and other property-related data
  • Information from third parties, including tenants and other landlords

A property that appears to generate rental income, with no matching income declared, is exactly the kind of mismatch these systems are designed to flag.

“If HMRC hasn’t contacted me yet, does that mean there’s no problem?”

Not necessarily. The absence of contact from HMRC does not mean rental income has been correctly reported, or that HMRC cannot investigate in the future. A disclosure made voluntarily, before HMRC identifies the issue, generally puts a landlord in a stronger position than waiting to be approached.

Six Ways Landlords Quietly Become Non-Compliant

This guide walks through the six areas we see most often among landlords considering a Let Property Campaign disclosure:

  • Common reasons landlords become non-compliant — the accidental landlord, the inherited property, and the “my agent handles it” assumption
  • Overseas landlord issues — misunderstandings about non-resident status and the Non-Resident Landlord Scheme
  • Incorrect expense claims — mortgage payments claimed in full, and repairs confused with capital improvements
  • Missing rental income — properties never registered, income declared for some years but not others, and cash rent left out entirely
  • Property ownership changes — joint ownership, changing ownership splits, and income reported on the wrong return
  • Section 24 and mortgage interest mistakes — the 2017 rule change that continues to catch out higher and additional rate taxpayers

The Small-Amount Trap

A property generating a modest amount of monthly rent can feel too small to bother declaring. Over several years, however, even a modest sum adds up to a significant figure once HMRC’s review period is taken into account.

£800 a month

Adds up to £9,600 a year in rental income — before any expenses are even considered.

Over six years

The same figure becomes £57,600 — a very different number to explain to HMRC after the fact.

Section 24: Why Your Tax Bill May Have Risen Even Though Your Rent Hasn’t

The rules restricting mortgage interest relief for individual landlords, often referred to as “Section 24”, are one of the most misunderstood areas of residential property tax. For most individual landlords, finance costs can no longer be deducted directly from rental income. Instead, relief is given as a basic-rate tax reduction, applied after tax on rental profit has already been calculated.

For higher and additional rate taxpayers in particular, this can mean paying more tax overall than expected, even where nothing else about the property has changed — and it is a frequent source of undetected errors in landlords’ existing tax returns.

How Felix & Co Can Help

Felix & Co is a UK accountancy practice led by a Chartered Certified Accountant, working with landlords to review rental income, identify where reporting may have gone wrong, and prepare accurate, well-supported disclosures where needed. We handle the calculations, the paperwork and the correspondence with HMRC, so you can resolve the position with confidence rather than uncertainty.

Frequently Asked Questions

How does HMRC actually find out about undeclared rental income?

Through data matching across sources including the Land Registry, letting agents, banks, mortgage lenders and information shared by overseas tax authorities, cross-checked automatically against the tax returns HMRC already holds.

My letting agent already deducts tax from my rent — doesn’t that mean I’m compliant?

Not necessarily. Tax deducted under the Non-Resident Landlord Scheme is generally a payment on account, not a final settlement. A Self Assessment return is normally still required to establish the correct final position.

I’ve lost my records — can I still make a disclosure?

Yes. This is a common situation. Information can often be reconstructed from bank statements, letting agent records, mortgage statements and previous tax returns.

Why has my tax bill gone up when my rent hasn’t changed?

This is often the effect of the Section 24 mortgage interest restriction, which changes how rental profit is taxed for individual landlords, particularly higher and additional rate taxpayers.

We changed our property ownership split years ago — could that affect our tax returns?

Possibly. The correct tax treatment depends on the legal and beneficial ownership position, and on whether the required elections or notifications were made to HMRC at the time.

Is this guide free to download?

Yes, with no obligation to use Felix & Co’s services afterwards.

Not sure where you stand? Complete the short form above to get your free copy of “Could HMRC Find Your Undeclared Rental Income?” by email instantly.

Felix & Co Chartered Accountants · Belix House, 19 Raymill Road East, Maidenhead, SL6 8SW · 01895 348 097 · accounts@felixaccountants.com

Categories
News

Free HMRC Landlord Tax Risk Assessment Checklist

Free HMRC Landlord Tax Risk Assessment Checklist

Felix & Co Free HMRC Landlord Tax Risk Assessment Checklist

Free HMRC Landlord Tax Risk Assessment Checklist

Free HMRC Landlord Tax Risk Assessment Checklist

In under five minutes, find out whether your rental property tax affairs might need a closer look — before HMRC asks the question for you. This free checklist from Felix & Co Chartered Accountants covers the five areas that most often lead landlords to a Let Property Campaign disclosure.

Prefer to talk it through first? Speak directly with a Chartered Certified Accountant about your rental property tax position.

Book Your Free 15-Minute Consultation →

Why a Five-Minute Checklist Is Worth Your Time

Most landlords who end up needing to make a disclosure to HMRC did not set out to under-report rental income. The issue usually develops quietly, over several years, through a property that was inherited, a former home that became a rental, or a simple assumption that a letting agent was handling the tax side of things.

This checklist exists to surface those quiet risk areas before they turn into a bigger problem. It won’t tell you exactly what you owe, and it isn’t a substitute for professional advice — but it will give you a clear, private starting point for deciding whether a fuller review is worthwhile.

What’s Inside the Checklist

The checklist is broken into five short sections, each covering a different area HMRC commonly looks at:

  • Property & Ownership History — inherited property, former homes, jointly owned property, ownership changes
  • Rental Income Reporting — Self Assessment registration, missed years, short lets, cash rent
  • Expenses & Deductions — mortgage interest, repairs versus improvements, record-keeping
  • Overseas & Residency Factors — non-resident landlords, the Non-Resident Landlord Scheme
  • HMRC Contact & Compliance History — previous letters, gaps in filing history

Once you’ve worked through all five sections, the guide explains how to read your results using a simple, plain-English risk indicator.

Who This Checklist Is For

  • Landlords who have never had their rental tax position formally reviewed
  • Anyone who inherited, jointly owns, or previously lived in a property they now let
  • UK landlords living overseas, or non-resident landlords with UK rental property
  • Landlords who use a letting agent and have assumed their tax reporting is handled
  • Anyone who has ever missed a tax year, or is simply unsure whether they’re fully up to date
“I did not deliberately avoid paying tax. I simply did not understand the rules.”

It is one of the most common things we hear from landlords — and exactly the reason this checklist takes a plain, non-judgemental approach to a subject that can otherwise feel intimidating.

What Your Risk Score Actually Means

0 statements ticked Nothing in the checklist points to an obvious risk area, though it’s still worth keeping records up to date as your circumstances change.
1–3 statements ticked One or more areas may be worth a closer look. Many landlords in this position have a straightforward situation once reviewed properly.
4 or more statements ticked Several risk factors apply to your circumstances, and a fuller review of your rental history is generally recommended before deciding on next steps.

This scoring is indicative only, based on patterns we see across real Let Property Campaign cases — not a formal assessment of your individual position.

What to Do Once You’ve Completed the Checklist

Whatever your result, the safest next step is the same: understand the facts before deciding whether action is needed. Start gathering what you can for any property you ticked a box against — rental statements, mortgage certificates, previous tax returns and letting agent records — even if you’re not yet sure a disclosure is required.

If your results suggest a possible issue, HMRC’s Let Property Campaign offers a structured, voluntary route to bring your rental tax affairs up to date, which can lead to a more favourable outcome than waiting for HMRC to make contact first.

Frequently Asked Questions

Is this checklist a substitute for professional advice?

No. It is a self-assessment tool designed to highlight areas worth reviewing. It cannot tell you whether a disclosure is required or calculate any tax, interest or penalties that may apply.

What should I do if I tick several boxes?

It is generally worth arranging a review with a specialist who can look at your specific properties and history in detail, rather than trying to work out the position alone.

Is my information kept private when I complete the checklist?

Yes. Completing the checklist does not involve sharing any information with HMRC or with Felix & Co. It is a private tool for your own use.

How long does the checklist take to complete?

Most landlords complete all five sections in under five minutes.

What happens after I download the checklist?

You’ll receive the checklist instantly by email, along with the option to arrange a free, no-obligation consultation if you’d like help interpreting your results.

Is the checklist really free?

Yes, with no obligation to use Felix & Co’s services afterwards.

Ready to check your position? Complete the short form above to get your free HMRC Landlord Tax Risk Assessment Checklist by email instantly.

Felix & Co Chartered Accountants · Belix House, 19 Raymill Road East, Maidenhead, SL6 8SW · 01895 348 097 · accounts@felixaccountants.com

Categories
News

Felix & Co HMRC Free Let Property Campaign Guide

Felix & Co HMRC Free Let Property Campaign Guide

Felix & Co HMRC Free Let Property Campaign Guide

HMRC Let Property Campaign Guide

HMRC Let Property Campaign Guide: How Landlords Can Make a Confident, Voluntary Disclosure

If you think rental income may not have been correctly reported to HMRC, the Let Property Campaign gives landlords a structured way to put things right voluntarily. This free guide from Felix & Co Chartered Accountants explains exactly how the campaign works, what it means for your tax position, and the steps to take before you contact HMRC.

Prefer to talk it through first? Speak directly with a Chartered Certified Accountant about your rental income and disclosure options.

Book Your Free 15-Minute Consultation →

What Is the HMRC Let Property Campaign?

The Let Property Campaign is HMRC’s ongoing disclosure opportunity for residential landlords who have undeclared rental income. It allows landlords — whether based in the UK or overseas — to review their tax affairs, work out what they owe, and report it to HMRC on their own terms, rather than waiting to be identified through an enquiry.

Landlords come to this position in all sorts of ways: renting out a former home after moving abroad, inheriting a let property, misunderstanding what counts as taxable rental profit, or simply never having registered for Self Assessment in the first place. The campaign does not assume dishonesty. It exists precisely because HMRC recognises that most rental tax problems build up gradually rather than deliberately.

What’s Inside This Guide

Our full guide takes you through the entire disclosure process in plain English, including:

  • What HMRC’s Let Property Campaign is, and who it applies to
  • How HMRC identifies undeclared rental income in the first place
  • The most common reasons landlords fall behind on reporting rental income
  • How many years HMRC can investigate, and what determines the answer
  • How penalties are calculated, and why prompted and unprompted disclosures are treated differently
  • Special situations, including overseas landlords, inherited property, jointly owned property and former homes
  • A step-by-step walkthrough of the disclosure process itself
  • What happens after a disclosure has been submitted to HMRC
  • Answers to the questions we’re asked most often by landlords considering a disclosure

Who This Guide Is For

  • Landlords who have never registered rental income for Self Assessment
  • Landlords who reported income correctly in some tax years but not others
  • UK landlords now living overseas, or overseas landlords with UK rental property
  • Anyone who has inherited, jointly owns, or previously lived in a property they now let
  • Landlords who have received a letter or enquiry from HMRC referencing rental income
  • Anyone unsure whether their previous tax returns were completed correctly

Why Voluntary Disclosure Usually Works in Your Favour

One of the most persistent misconceptions we hear from landlords is that contacting HMRC first will automatically trigger an investigation. In practice, the opposite is usually true. HMRC draws a clear distinction between an unprompted disclosure — where a landlord comes forward before HMRC has taken any action — and a prompted disclosure, made only after HMRC has already made contact.

Unprompted disclosures are generally treated more favourably, with a lower penalty range reflecting the fact that the landlord identified and corrected the issue themselves. Timing matters, and it is one of the main reasons landlords choose to review their position before HMRC asks the question for them.

“I did not deliberately avoid paying tax. I simply did not understand the rules.”

This is one of the most common things landlords tell us before making a disclosure — and it reflects how HMRC actually assesses most Let Property Campaign cases: not as deliberate evasion, but as a position that needs correcting properly.

How Far Back Can HMRC Actually Investigate?

How many years of rental income you may need to disclose depends on the reason the error occurred. Broadly, HMRC can go back four years where reasonable care was taken but a genuine mistake was made, six years where the behaviour is considered careless, and up to twenty years where the failure to report is considered deliberate.

Establishing which category applies — and therefore how many years of records you actually need to review — is one of the most important early steps in preparing an accurate disclosure. Getting this wrong in either direction can mean paying more than necessary, or submitting an incomplete disclosure that HMRC later challenges.

Getting the Numbers Right Before You Contact HMRC

A disclosure is only as good as the calculation behind it. Two areas trip up landlords more than any other: mortgage interest and capital versus revenue expenses.

Mortgage interest

Since April 2017, individual landlords generally cannot deduct mortgage interest directly from rental income. Relief is instead given as a basic-rate tax reduction — a rule change that catches out many landlords preparing figures for a disclosure themselves.

Repairs vs improvements

A repair is usually an allowable expense; a capital improvement, such as an extension, generally is not. Mixing the two up is one of the most common reasons a disclosure needs correcting after submission.

Because these figures form the basis of what you tell HMRC, we strongly recommend a proper professional review before submitting anything — particularly where several tax years and properties are involved.

How Felix & Co Can Help

Felix & Co is a UK accountancy practice led by a Chartered Certified Accountant, working with landlords across the country on Let Property Campaign disclosures. We handle the process from start to finish: reviewing your rental history, identifying which years and properties are affected, calculating tax, interest and penalties accurately, preparing a complete disclosure report, and corresponding with HMRC on your behalf so you don’t have to navigate it alone.

Frequently Asked Questions

What is the HMRC Let Property Campaign?

It is HMRC’s voluntary disclosure route for residential landlords with undeclared rental income. It allows landlords to review their tax position, calculate what is owed, and report it to HMRC before HMRC identifies the issue independently.

Will I automatically be investigated if I come forward?

No. Voluntarily correcting your tax affairs is generally viewed more favourably than waiting for HMRC to identify the issue, and it typically results in a lower penalty than a prompted disclosure made after HMRC has already made contact.

How many years of rental income do I need to disclose?

It depends on whether the error is considered an innocent mistake, careless, or deliberate — typically four, six, or up to twenty years respectively. A proper review of your circumstances is needed to establish which applies.

I live overseas — do I still need to make a disclosure?

Possibly, yes. Owning UK rental property can create UK tax obligations even if you are not UK resident, regardless of whether your letting agent already deducts tax under the Non-Resident Landlord Scheme.

What if I don’t have complete records?

This is common. Missing information can often be reconstructed from bank statements, letting agent statements, mortgage certificates and previous tax returns, provided a reasonable and well-explained approach is taken.

Is the guide really free, and is there any obligation?

Yes. The guide is free to download and there is no obligation to use Felix & Co’s services afterwards. Many landlords use it simply to understand their position before deciding what to do next.

Ready to understand your position? Complete the short form above to receive your free copy of the HMRC Let Property Campaign Guide by email instantly.

Felix & Co Chartered Accountants · Belix House, 19 Raymill Road East, Maidenhead, SL6 8SW · 01895 348 097 · accounts@felixaccountants.com

Categories
Articles Articles Let Property Campaign

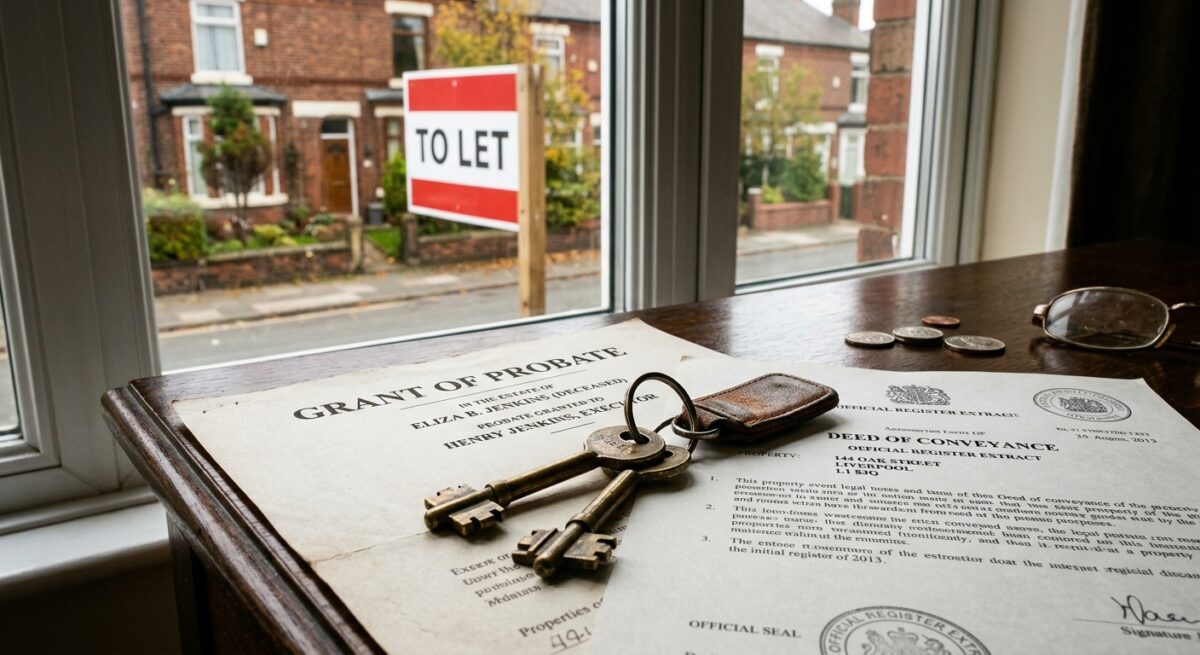
Let Property Campaign for Inherited Rental Property: What Should Beneficiaries Consider?

Inheriting a rental property brings its own particular set of tax questions, and they don’t always arrive at a convenient time — often in the middle of dealing with probate, grief, and a range of other practical matters. Two distinct situations tend to come up: discovering that the person who died had undeclared rental income of their own, and working out your own tax position once you become the new landlord. Both are manageable, but each involves a slightly different process.

Inherited a rental property and not sure where the tax position stands? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Situation One: The Deceased Had Undeclared Rental Income

If, while dealing with the estate, you discover that the person who died had rental income that was never declared to HMRC during their lifetime, this generally becomes a matter for the estate to resolve, typically handled by the executor or personal representative as part of the estate administration process. This isn’t the same as the beneficiary’s own Let Property Campaign disclosure — it relates to the deceased’s own historic tax position and is generally corrected before the estate can be finalised and distributed to beneficiaries.

Executors have a legal duty to ensure the deceased’s tax affairs are in order before completing the estate administration, and outstanding tax liabilities, including undeclared rental income, are generally paid from the estate’s assets before distribution. If this is discovered, it’s worth addressing it promptly, since delaying can hold up probate and the eventual distribution of the estate to beneficiaries.

Situation Two: Your Own Rental Income From an Inherited Property

If you’ve inherited a property and decided to keep letting it out, you become responsible for reporting the rental income from the date you inherited it — typically the date of death, or the date the property was formally transferred to you, depending on the specific circumstances of the estate administration. This is exactly the kind of situation that creates “accidental landlords,” and it’s a common pathway into needing a Let Property Campaign disclosure a few years down the line if the reporting obligation wasn’t recognised at the time. Our guide on being an accidental landlord covers this pattern more generally.

Why Beneficiaries Sometimes Miss This Obligation

It’s genuinely easy to overlook. Many beneficiaries inherit a share of a property alongside other assets and don’t think of themselves as “becoming a landlord” in any formal sense, particularly where a letting agent continues managing the property much as before. But from a tax perspective, inheriting a share of a let property and continuing to receive rental income creates the same reporting obligation as buying a rental property outright.

The Probate Value and Its Relevance

When a property is inherited, its market value at the date of death (the “probate value”) becomes the new base cost for Capital Gains Tax purposes for the beneficiary — this is a completely separate matter from Income Tax on rental profits, but it’s worth understanding both together since they often surface at the same time. If the property is later sold, Capital Gains Tax is calculated based on the increase in value from the probate value, not from whatever the original deceased owner originally paid for it.

What If the Property Is Jointly Inherited?

Where a property is inherited by multiple beneficiaries — siblings, for example — each beneficiary is generally responsible for reporting their own share of the rental income, based on their share of the inheritance. This is similar in principle to any other jointly owned property, and each beneficiary would typically need to consider their own disclosure if the income wasn’t reported from the start.

Working Out How Many Years Are Involved

If you’ve been receiving rental income from an inherited property for several years without declaring it, the look-back period generally follows the same principles as any other Let Property Campaign disclosure — based on the reason for non-disclosure rather than the fact that the property was inherited. Our guide on how many years you need to declare explains this in more detail. Genuinely not realising that inheriting a share of a let property created a personal reporting obligation is a common and understandable scenario, and typically falls into the more lenient end of the behaviour spectrum, provided the disclosure is made voluntarily once identified.

Inheritance Tax Considerations Alongside Income Tax

Separately from the ongoing rental income question, inherited property is often relevant to the estate’s Inheritance Tax position, and if the property continues to generate income for the estate before it’s formally distributed, that income may need to be reported by the estate itself during the administration period. Our guides on Inheritance Tax planning for property owners and IHT and trust planning cover this wider context.

What Records You’ll Need

  • The grant of probate and the date the property was formally inherited or transferred
  • The probate value of the property, for future Capital Gains Tax purposes
  • Rental income and expense records from the date you began receiving income personally
  • Details of any co-beneficiaries and their respective shares, if the property is jointly inherited

Our record keeping guide covers the broader documentation landlords should retain.

How Felix Accountants Can Help

We help beneficiaries work through both sides of this situation — resolving a deceased relative’s historic undeclared rental income as part of estate administration, and establishing your own correct tax position going forward if you’ve continued to let an inherited property. Both situations are common, manageable, and rarely as complicated as they first feel once someone experienced walks you through the specifics.

Frequently Asked Questions

Who is responsible for a deceased person’s undeclared rental income?

This generally becomes a matter for the estate, typically handled by the executor as part of finalising the deceased’s tax affairs before the estate is distributed to beneficiaries.

Do I need to declare rental income from a property I inherited but haven’t sold?

Yes, if you’re receiving rental income from the property, you’re responsible for reporting it from the point you inherited it, in the same way as any other rental property you own.

What is the probate value and why does it matter?

It’s the property’s market value at the date of death, which becomes your new base cost for Capital Gains Tax purposes if you later sell the property.

If several siblings inherit a property together, who reports the rental income?

Each beneficiary is generally responsible for reporting their own share of the rental income, based on their share of the inheritance.

Is it common for beneficiaries to genuinely not realise they need to declare this income?

Yes, this is a common and understandable situation, particularly where a letting agent continues managing the property. Coming forward voluntarily once you realise is generally treated favourably.

Let’s work through your inherited property’s tax position. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Articles Blogs Let Property Campaign News

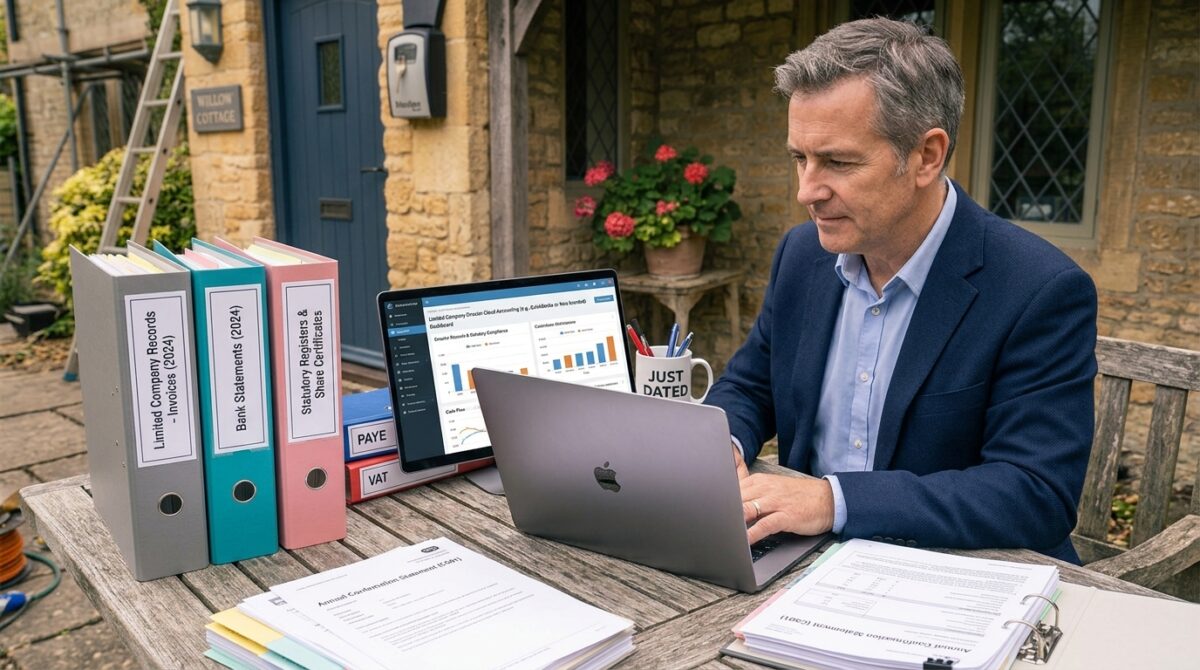
Bookkeeping for Limited Companies: What Records Should Directors Maintain?

Running a limited company comes with a specific set of legal record-keeping obligations that go beyond what’s expected of a sole trader — partly because a company is a separate legal entity from its directors and shareholders, and partly because Companies House and HMRC each have their own requirements. Getting organised early makes year-end accounts, Corporation Tax returns, and any future due diligence considerably smoother.

Want help setting up proper bookkeeping for your limited company? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Two Categories of Records: Statutory and Accounting

Limited company record-keeping falls into two related but distinct categories:

  • Statutory records: company-level records required by Companies House, covering the company’s legal structure and governance
  • Accounting records: financial records required by both Companies House (to prepare accurate statutory accounts) and HMRC (to support the Company Tax Return)

Directors are legally responsible for maintaining both, even where day-to-day bookkeeping is outsourced to an accountant or bookkeeper.

Statutory Records Every Company Must Maintain

  • Register of members (shareholders)
  • Register of directors and their service addresses
  • Register of people with significant control (PSC register)
  • Records of resolutions and minutes of general meetings and board decisions
  • Register of charges, where the company has secured debt against its assets

Many of these are also filed at Companies House and kept up to date through the annual confirmation statement, but the company itself is still required to maintain its own internal registers, whether physically or digitally. Our company secretarial services cover the ongoing maintenance of these records if you’d rather not manage them in-house.

Accounting Records Every Company Must Maintain

Separately from the statutory registers, companies must keep sufficient accounting records to show and explain the company’s transactions, and to allow accurate financial statements to be prepared. In practice, this generally includes:

  • Records of all money received and spent by the company, including the reason for each transaction
  • A record of the company’s assets and liabilities, including what the company owns and owes
  • Records of goods bought and sold, including invoices issued and received, for companies dealing in goods
  • Stock records at the end of each financial year, where the company holds stock
  • Details of stocktaking used to arrive at stock figures, where applicable
  • Records supporting all business expenses claimed, including receipts and invoices, particularly for allowable limited company expenses

Bank Records

Every limited company should operate through its own dedicated business bank account, entirely separate from any director’s personal finances — this isn’t just good practice, it’s essentially required by the legal separation between a company and its owners. Bank statements form a core part of the accounting record trail, and regular bank reconciliation against your bookkeeping software helps catch errors early rather than at year end.

Director’s Loan Account Records

Where money moves between a director personally and the company outside of salary or dividends — for example, a director lending money to the company, or drawing money that isn’t yet formally declared as salary or dividend — this needs to be tracked carefully through a director’s loan account. Poor record-keeping here is a common source of problems, since an unclear or overdrawn director’s loan account can create unexpected tax charges, both for the company and the director personally.

Payroll Records

If the company has any employees, including directors paid a salary, payroll records need to be maintained separately, covering pay, tax and National Insurance deductions, and the underlying Real Time Information submissions made to HMRC. See our guide on small business payroll explained for what’s involved in running this correctly.

VAT Records, If Registered

VAT-registered companies have an additional layer of record-keeping requirements, including VAT invoices issued and received, and — under Making Tax Digital — digital records maintained through compatible software rather than manual spreadsheets alone. Our Making Tax Digital guide covers what this means in practice.

How Long Do Records Need to Be Kept?

For most companies, accounting records generally need to be retained for at least six years from the end of the relevant accounting period, though this can be longer in specific circumstances — for example, where the company buys something that it expects to last more than six years, such as equipment or property, or if the company is subject to an ongoing HMRC enquiry. It’s a sensible default to retain everything for at least six years even where a shorter minimum might technically apply, given how straightforward digital storage has become.

Choosing a Bookkeeping System

Beyond the legal minimum, most directors find that cloud accounting software, linked directly to the company bank account, makes ongoing compliance considerably easier than manual spreadsheets — particularly for VAT-registered companies needing Making Tax Digital compatibility, and for directors who want an accurate, real-time view of the company’s financial position rather than reconstructing it at year end.

What Happens If Records Aren’t Properly Maintained?

Failing to keep adequate accounting records is a company law offence, and directors can be personally liable for penalties or, in more serious cases, disqualification. Beyond the legal risk, poor records also make it far harder to prepare accurate statutory accounts and tax returns, increase accountancy costs (since more time is spent reconstructing information), and create real problems if the company is ever sold, audited, or subject to an HMRC enquiry.

How Felix Accountants Can Help

We help directors set up bookkeeping systems and statutory record-keeping processes that meet both Companies House and HMRC requirements from day one, whether that’s a fully managed bookkeeping service or guidance to help you manage it confidently yourself. See our wider business tax services for how well-organised records feed into accurate, efficient annual compliance.

Frequently Asked Questions

What’s the difference between statutory records and accounting records?

Statutory records relate to the company’s legal structure — shareholders, directors, and governance decisions. Accounting records relate to the company’s financial transactions, assets and liabilities, used to prepare accounts and tax returns.

How long must a limited company keep its accounting records?

Generally at least six years from the end of the relevant accounting period, though this can be longer in specific circumstances, such as an ongoing HMRC enquiry.

Do I need a separate bank account for my limited company?

Yes, effectively. A company is a separate legal entity from its directors, and its finances should be kept entirely separate from any director’s personal banking.

What is a director’s loan account and why does it need careful records?

It tracks money moving between a director personally and the company outside of formal salary or dividends. Poor record-keeping here can lead to unexpected tax charges if the account becomes unclear or overdrawn.

What happens if a company doesn’t keep proper accounting records?

It’s a company law offence, and directors can be held personally liable. It also makes accurate accounts and tax returns far harder to prepare, and creates problems for any future sale, audit or HMRC enquiry.

Let’s get your company’s records properly organised. Book your free 15-minute consultation with Felix Accountants.

Categories
Articles Articles Blogs Let Property Campaign

PAYE Payroll Errors: What Should a Small Employer Do After Paying Employees Incorrectly?

Even with the best payroll software, mistakes happen — a wrong tax code, a miscalculated overtime payment, an employee accidentally paid twice, or figures reported incorrectly to HMRC through Real Time Information. The good news is that HMRC has a well-established process for correcting payroll errors, and how you fix it depends mainly on when the mistake is discovered and whether it affected the employee’s pay, the figures reported to HMRC, or both.

Spotted a payroll error and not sure how to fix it? Book a free 15-minute consultation with Felix Accountants. Book your free call here.
Step 1: Identify Exactly What Went Wrong

Before correcting anything, pin down the specific nature of the error:

  • Pay or deduction error: the employee was paid the wrong gross amount, or Income Tax/National Insurance was calculated incorrectly
  • Reporting error: the employee was paid correctly, but the Full Payment Submission (FPS) sent to HMRC contained the wrong figures
  • Payment date error: the wrong payment date was recorded, misaligned the payment with the incorrect tax period
  • Employee information error: incorrect start or leaving dates, National Insurance category, or personal details

Compare the current period’s figures against year-to-date totals in your payroll software or submission log to confirm exactly where the discrepancy lies before making any correction.

Correcting the Figures Reported to HMRC

You cannot “reverse out” an FPS once it’s been submitted — instead, corrections are made by reporting the correct year-to-date figures going forward:

  • If discovered within the same tax year: simply include the corrected year-to-date figures in your next regular FPS. There’s no need to resubmit each individual period separately; the correction flows through as an adjustment to the running total.
  • If discovered shortly after the tax year ends (broadly, up to 19 April): you can generally still submit an additional FPS with corrected year-to-date figures as at 5 April for the previous tax year.
  • If discovered later, after the final submission deadline has passed: a correction for an earlier tax year is generally still possible, but the process depends on your payroll software and how far back the correction relates — this is worth checking with your payroll provider or accountant, since the mechanism has changed in recent years and older correction methods (such as the Earlier Year Update) are being phased out for more recent tax years.

Correcting a payment date specifically follows a slightly different approach — an additional FPS with the correct payment date, marked with the appropriate late reporting reason, is generally the right route.

Will You Be Penalised for a Payroll Error?

Not automatically. HMRC has confirmed that a penalty only applies where the employer failed to take reasonable care or acted deliberately — a genuine, promptly corrected mistake generally doesn’t attract a penalty on its own. This is a similar principle to the behaviour-based penalty framework used elsewhere in the tax system, and it’s another reason to correct errors as soon as they’re identified rather than leaving them unaddressed.

If You Underpaid an Employee

Once the correct figures are established, the shortfall generally needs to be paid to the employee as soon as practicable, alongside the corrected PAYE reporting. Underpaying employees, even accidentally, can create separate employment law issues if it results in pay falling below the National Minimum or Living Wage for the hours worked, so it’s worth checking this specifically where an underpayment has occurred, not just correcting the PAYE figures.

If You Overpaid an Employee

Recovering an over-payment from an employee is more sensitive than it might first appear. While employers generally have the right to recover a genuine over-payment, doing so requires careful handling:

  • Communicate clearly and promptly with the employee about the error and the proposed recovery
  • Have a documented policy, or agree a reasonable repayment arrangement, particularly for larger amounts, rather than deducting the full sum from a single payslip without warning
  • Be cautious about reducing a single deduction to the point where it takes pay below the National Minimum Wage for that pay period
  • Keep clear records of the error, the amount, and how it was recovered, in case questions arise later

Unilaterally deducting a large over-payment without any communication can create genuine employment relations problems, even where the employer is technically entitled to recover the money.

Correcting Employer Payments to HMRC

A common misconception is that correcting an earlier period’s FPS changes what was owed to HMRC for that earlier period. In practice, corrections to previously reported figures typically adjust the payment due for the period in which the correction itself is submitted, not the original period — so if you correct a Month 3 error in Month 6, the adjustment generally shows up in your Month 6 liability to HMRC, rather than reopening the Month 3 payment.

What If HMRC’s Records Still Show the Wrong Figures?

If you’ve checked that the correct information was submitted via your RTI returns but HMRC’s own systems still show something different, this points to an error on HMRC’s end rather than in your submissions. In this situation, you can use HMRC’s dedicated service to query and correct an employer PAYE bill discrepancy, rather than resubmitting figures you’ve already confirmed are correct.

Preventing Payroll Errors Going Forward

A few habits significantly reduce the risk of recurring payroll errors:

  • Reconciling payroll reports against bank payments each pay period, not just at year end
  • Double-checking tax codes when HMRC issues updated notices, rather than assuming they’re correct
  • Using payroll software that clearly flags year-to-date discrepancies before submission
  • Reviewing new employee starter information carefully, since incorrect starter declarations are a common source of tax code errors

See our guide on small business payroll explained for a broader introduction to running payroll correctly from the outset.

How Felix Accountants Can Help

We help small employers correct payroll errors quickly and properly, handle the sensitive process of recovering over-payments from employees, and set up ongoing payroll processes that reduce the chance of errors recurring. Our payroll services can also take this off your hands entirely, running your payroll and managing HMRC reporting on your behalf.

Frequently Asked Questions

Can I fix a payroll error from an earlier pay period myself?

Yes, in most cases you correct it by including the updated year-to-date figures in your next regular FPS, rather than resubmitting the earlier period separately.

Will HMRC fine me for a genuine payroll mistake?

Not automatically. Penalties generally only apply where reasonable care wasn’t taken or the error was deliberate — a promptly corrected genuine mistake usually doesn’t attract a penalty.

Can I deduct an over-payment from an employee’s next payslip without telling them?

It’s strongly advisable not to. While employers generally have the right to recover a genuine over-payment, doing so without clear communication can create employment relations issues, and deductions shouldn’t reduce pay below the National Minimum Wage for that period.

Does correcting an old payroll error reopen what I owed HMRC for that earlier period?

Generally no. Corrections to earlier periods typically adjust the payment due for the period in which the correction is submitted, rather than reopening the original month or quarter’s liability.

What should I do if HMRC’s records don’t match what I submitted?

If you’ve confirmed the correct figures were submitted via RTI, this usually indicates an error on HMRC’s end, and you can use HMRC’s dedicated service to query and resolve the discrepancy.

Let’s get your payroll error corrected properly. Book your free 15-minute consultation with Felix Accountants.