Categories
Articles Articles Blogs Let Property Campaign News

Let Property Campaign: Can You Disclose Rental Income From a Property You No Longer Own?

If you used to let out a property but have since sold it, gifted it, or moved back in yourself, you might assume that any undeclared rental income from those years is now somehow out of reach of HMRC. It isn’t. The good news is that selling the property doesn’t close the door on putting things right — you can still use the HMRC Let Property Campaign to disclose rental income from a property you no longer own, and doing so voluntarily is almost always better than waiting to be found.

Not sure where you stand with a property you’ve already sold? Book a free 15-minute consultation with Felix Accountants and we’ll talk through your situation in plain English, with no obligation. Reserve your free call here.

Does Selling a Rental Property Remove Your Obligation to Declare Past Rent?

No. Your obligation to report rental income relates to the tax years in which you actually received that income, regardless of whether you still own the property today. If you let out a property between, say, 2019 and 2023 and then sold it, you were still legally required to report the rent you received during those years on a Self Assessment tax return. Selling the property doesn’t erase that history — it simply means the disclosure now covers a property that no longer appears on your current asset list.

This is one of the most common misunderstandings we see at Felix Accountants. Landlords often believe that once a property is sold, any loose ends relating to it are automatically tidied up. In reality, HMRC’s Let Property Campaign was specifically designed to capture exactly this kind of situation — current landlords, former landlords, and anyone in between with unreported letting income.

Who Can Use the Let Property Campaign for a Former Rental Property?

The Let Property Campaign is open to individual landlords who have received undeclared rental income from residential property in the UK or abroad. This includes people who:

  • Sold the rental property some years ago but never declared the rent received while they owned it
  • Inherited a property, let it out for a period, and later sold it
  • Moved back into a property that was previously let to tenants
  • Gifted or transferred a rental property to a family member and stopped receiving rent from it
  • Were an accidental landlord for a short period before selling

In every one of these cases, the fact that the property has moved on doesn’t change the underlying tax history. What matters to HMRC is the income you received while you owned and let the property, not whether you still hold the title today.

How Far Back Do You Need to Declare?

The look-back period depends on why the income wasn’t declared in the first place, not on when you sold the property. As a general guide:

  • Genuine, careless error: typically up to 4–6 years
  • Failure to take reasonable care: up to 6 years
  • Deliberate non-disclosure: HMRC can go back as far as 20 years

We’ve written a more detailed breakdown of this in our guide on how many years you need to declare and our companion article on how many years of rental income landlords must disclose. If the property has since been sold, you’ll still need to work out the correct number of years based on when you first started letting it and when the undeclared income actually stopped, which for a sold property is usually the completion date.

What About Capital Gains Tax on the Sale Itself?

A disclosure through the Let Property Campaign covers rental income and any related expenses, not the sale of the property. However, if you sold the property at a profit, you may separately owe Capital Gains Tax on that sale, and UK residential property sales generally need to be reported to HMRC within 60 days of completion. If both the rental income and the sale itself were never reported, it’s sensible to deal with both matters together rather than treating them as separate problems, since HMRC will often be looking at your full history once a disclosure is opened.

Why Voluntary Disclosure Still Matters After the Sale

Coming forward voluntarily, before HMRC contacts you, generally results in significantly lower penalties than a prompted disclosure that follows an HMRC letter or enquiry. Our article on prompted versus unprompted disclosures sets out the practical difference in more detail, but the short version is this: HMRC has extensive data-matching capability drawn from Land Registry records, Stamp Duty Land Tax returns, letting agent reporting and platforms such as Airbnb, so a sold property is not invisible simply because you no longer own it. Making the first move, through our voluntary disclosure guidance, gives you more control over the outcome, the tone of the process and the penalty percentage applied.

What You’ll Need to Gather

Because you no longer own the property, you may not have easy access to the same records a current landlord would. It’s still worth trying to pull together:

  • Bank statements showing rent received during the letting period
  • Tenancy agreements or letting agent statements, if available
  • Records of allowable expenses such as mortgage interest, insurance, repairs and letting agent fees
  • The completion date of the sale, and the purchase and sale prices, in case a Capital Gains Tax position also needs reviewing

If some records are missing entirely, that’s a common and manageable problem — HMRC accepts reasonable estimates provided they’re clearly labelled and based on a sensible methodology, rather than guesswork presented as fact.

How Felix Accountants Can Help

We regularly help former landlords work through reporting undisclosed rental income to HMRC, including cases where the property has already been sold, gifted, or repossessed. We’ll help you reconstruct a reasonable income and expense history, calculate what’s owed, and manage the notification and disclosure process on your behalf so you’re not dealing with HMRC directly and unrepresented.

Frequently Asked Questions

Can I still be investigated if I sold the rental property years ago?

Yes. HMRC’s ability to open an enquiry into undeclared rental income isn’t affected by a subsequent sale. The tax liability relates to the years you received the income, and HMRC can pursue this regardless of your current ownership status.

Do I need to disclose if the rental profit was very small?

Generally yes. There’s no minimum threshold that exempts small amounts of rental profit from disclosure, although your allowable expenses and personal allowance may mean little or no tax is ultimately due once everything is calculated correctly.

What if I can’t find all my old records for a property I no longer own?

This is common, particularly for properties sold some years ago. HMRC accepts reasonable, clearly explained estimates where original records aren’t available. An accountant experienced with the Let Property Campaign can help you build a defensible estimate.

Will disclosing affect the sale I’ve already completed?

No. The sale itself is a separate, completed transaction. A Let Property Campaign disclosure deals with the historic rental income tax position and won’t unwind or affect the property sale.

Is it too late to make a voluntary disclosure?

It’s rarely too late to disclose voluntarily unless HMRC has already contacted you about the specific property. Acting before any HMRC letter arrives keeps your disclosure classed as unprompted, which generally attracts lower penalties.

Ready to sort out a property you’ve already sold? Felix Accountants specialises in Let Property Campaign disclosures for current and former landlords. Book your free 15-minute consultation and let’s work out exactly where you stand.


Categories
Articles Articles Blogs Let Property Campaign

Let Property Campaign Airbnb and Short-Term Rentals Eligibility

Airbnb and other short-term letting platforms now report host income directly to HMRC, so if you’ve been treating your listing as “just a bit of extra cash” rather than taxable rental income, it’s worth checking your position carefully. A common question we hear is whether the Let Property Campaign can be used to put things right — and the answer is generally yes, but with some important nuances.

Unsure whether your Airbnb income should have been declared, or how far back you need to go? Book a free 15-minute call with Felix Accountants to talk it through confidentially.

Is Airbnb Income Taxable?

Yes. Income from letting a property, or even a spare room, on a short-term basis is taxable in the same way as any other rental income, subject to any reliefs you’re entitled to. The only exceptions are the £1,000 property allowance (if your gross rental income is below that threshold) and the Rent a Room Scheme, which lets you earn up to £7,500 tax-free from letting a room in your own home, provided you live there too.

Does the Let Property Campaign Cover Short-Term Lets?

The LPC applies to individual landlords with undeclared tax on residential property income, and this generally includes short-term and holiday-style lettings of residential property, whether booked through Airbnb, Booking.com, Vrbo or direct. What matters for eligibility is that the property is held personally, not through a limited company, and that the income is genuinely rental-style rather than a trading business involving substantial additional services such as daily cleaning, meals or reception.

If your short-term letting activity has grown into something closer to running a guest house, with significant services provided, HMRC may view it as a trade rather than a property business, which changes how it’s taxed and may take it outside the scope of the LPC. This is a grey area worth getting professional input on before you disclose.

What Changed With Furnished Holiday Lets?

Until 6 April 2025, properties meeting certain letting and availability conditions could qualify as Furnished Holiday Lets (FHLs), unlocking more generous tax treatment, including fuller mortgage interest relief and access to certain capital allowances. That regime was abolished from the 2025/26 tax year, and short-term let income is now taxed under the same rules as standard rental property income, including the mortgage interest restriction that already applied to other landlords. If you’ve been disclosing historic years, it’s important to apply the rules that were in force for each specific tax year rather than today’s rules retrospectively.

How Far Back Do You Need to Go?

As with any Let Property Campaign disclosure, the number of years you need to cover depends on your behaviour: whether the non-disclosure was a genuine, reasonable mistake, careless, or deliberate. Our guide on how many years of rental income landlords must disclose sets out the general time limits in more detail.

Accidental Hosts and First-Time Disclosures

Many people who let out a property short-term didn’t set out to become landlords in the tax sense — perhaps you started renting a spare property while working away, or began hosting guests after downsizing. If that sounds like you, our page on becoming an accidental landlord covers how HMRC treats these situations and what you need to do to get compliant.

Practical Steps If You Haven’t Declared Airbnb Income

  • Pull together booking records, payout statements and platform tax summaries for each relevant tax year
  • Work out which years the Furnished Holiday Let rules did or didn’t apply, since this affects your allowable deductions
  • Check whether the Rent a Room Scheme or property allowance already covers part of your income
  • Consider whether your behaviour is likely to be classed as careless or deliberate, since this affects the penalty rate and the years you must disclose
  • Make your disclosure before HMRC contacts you, to secure unprompted disclosure treatment and a lower penalty

Common Mistakes Hosts Make

The most frequent error we see is hosts assuming that because Airbnb “already takes its cut” or issues a summary, the income has somehow already been reported to HMRC on their behalf. It hasn’t — platform reporting to HMRC is a compliance tool for HMRC, not a substitute for your own Self Assessment return. Another common mistake is applying FHL-style deductions to years after the regime ended, which can trigger its own correction later.

How Felix Accountants Can Help

We regularly help hosts and landlords work out exactly what’s owed across multiple tax years, apply the correct rules for each year, and submit an accurate Let Property Campaign disclosure that stands up to HMRC scrutiny.

Frequently Asked Questions

Do I need to declare Airbnb income if I only host occasionally?

If your gross rental income from all sources is under £1,000 in a tax year, the property allowance may mean you don’t need to declare it. Above that, it generally needs to be reported, even if hosting is occasional.

Can I still get Furnished Holiday Let tax treatment for a current listing?

No. The Furnished Holiday Let regime was abolished from 6 April 2025, so short-term let income from the 2025/26 tax year onward is taxed under the standard property income rules.

Does the Let Property Campaign cover overseas short-term lets?

It can, in certain circumstances, though overseas income brings in additional considerations such as double taxation relief. It’s best to get specific advice if your undeclared income relates to a property outside the UK.

What if my short-term letting is really more like running a guest house?

If you provide substantial additional services, HMRC may treat the activity as a trade rather than a property business, which can affect both how it’s taxed and whether the Let Property Campaign is the right disclosure route.

Categories
Articles Blogs Let Property Campaign

Let Property Campaign vs HMRC Tax Investigation

If you’ve fallen behind on declaring rental income, you’ve probably come across two very different-sounding terms: the Let Property Campaign and an HMRC tax investigation. They can lead to the same place — you paying the tax you owe — but the route, the paperwork, and crucially the penalties can be worlds apart depending on which one applies to your situation.


Not sure which route applies to you, or whether you should come forward before HMRC contacts you? Book a free 15-minute consultation with Felix Accountants and we’ll talk through your specific circumstances, in confidence, with no obligation.

What Is the HMRC Let Property Campaign?

The Let Property Campaign (LPC) is a voluntary disclosure facility that HMRC has run since 2013. It allows individual UK landlords with undeclared or under-declared rental income to come forward, calculate what they owe, and pay it — usually on more favourable terms than if HMRC discovered the problem itself. It applies to residential property income only; landlords holding property through a limited company or trust cannot use the LPC.

Once you notify HMRC of your intention to disclose, you’re generally given 90 days to work out the tax, interest and any penalty due and submit your disclosure. It’s a structured, self-managed process, and it is entirely optional — nobody forces you into the LPC.

What Is an HMRC Tax Investigation?

A tax investigation, by contrast, is something HMRC initiates. It isn’t voluntary, and once it starts, you lose control over the pace and shape of the process. There are two versions worth understanding.

Formal Compliance Checks and Enquiries

These are opened when HMRC has reason to believe a return is wrong — often triggered by data mismatches from sources like the Land Registry, letting agents, mortgage lenders or short-term letting platforms. HMRC will typically request records, ask questions, and can go back several years depending on the behaviour involved.

Code of Practice 9 (COP9)

Code of Practice 9 is reserved for cases where HMRC suspects deliberate tax fraud. It’s a civil process, offered as an alternative to criminal prosecution, but it requires you to sign a formal contract admitting to any deliberate wrongdoing and disclose everything in full. It carries much higher stakes than either the LPC or a standard compliance check, and professional representation is essential from the outset.

Key Differences at a Glance

FactorLet Property CampaignHMRC Tax Investigation
Who starts itYou, voluntarilyHMRC
Typical penalty range (careless error)0% to 30% (often much lower when unprompted)15% to 30% or higher, since the disclosure counts as prompted
Who controls the paceYou, within the 90-day windowHMRC
Public “naming and shaming” riskVery low, if full and accuratePossible for serious, deliberate cases
Available for companies/trustsNoYes

Why Timing Matters: Prompted vs Unprompted Disclosure

This is the single biggest factor in how much you’ll ultimately pay. Under HMRC’s penalty rules, an unprompted disclosure — one made before HMRC has any reason to believe it’s about to find the error — attracts a far lower penalty than a prompted disclosure made after contact from HMRC. For a careless error, an unprompted disclosure can start at 0%, while a prompted one is very rarely below 15%. Once HMRC has sent you a nudge letter or opened an enquiry, that lower band is gone for good, no matter how cooperative you are afterwards.

Which Route Applies to You?

In practice, most landlords who haven’t yet heard from HMRC are free to use the LPC on an unprompted basis. If you’ve already received a nudge letter, you can generally still use the LPC, but your disclosure will be treated as prompted, meaning a higher minimum penalty. If HMRC has gone further and opened a formal enquiry — or suspects deliberate concealment — the LPC route is usually closed to you, and you’ll be dealing with a standard compliance check or, in serious cases, COP9.

Working out exactly how many years of rental income need to be disclosed also depends on which category your behaviour falls into — careless errors generally require fewer years back than deliberate non-disclosure.

What Happens If You Do Nothing?

Doing nothing is the one option that reliably makes things worse. HMRC’s Connect system cross-references data from letting agents, banks, mortgage applications and property platforms, so undeclared rental income is increasingly likely to surface on its own. If it does, you lose the ability to make an unprompted disclosure entirely, and any subsequent enquiry starts from a position where HMRC is already suspicious.

Common Mistakes Landlords Make

  • Waiting to see if HMRC “actually finds out” rather than disclosing proactively
  • Assuming the LPC applies to a property held in a limited company (it doesn’t)
  • Submitting a partial disclosure and leaving out a property or income stream, which HMRC can treat as deliberate concealment if later discovered
  • Trying to negotiate a COP9 case without professional representation

How Felix Accountants Can Help

Whether you’re weighing up an unprompted LPC disclosure, responding to a nudge letter, or facing a formal enquiry, getting the behaviour classification right from the outset has a direct impact on your final bill. We handle the calculations, the correspondence with HMRC, and the disclosure itself, so you’re not navigating it alone.

Frequently Asked Questions

Can HMRC open an investigation while I’m in the middle of an LPC disclosure?

Generally, if your LPC disclosure is accurate, complete and submitted in good faith, HMRC treats it as a self-contained process and won’t open a parallel enquiry into the same rental income. However, HMRC does reserve the right to investigate further if the disclosure appears incomplete or inconsistent with information it already holds.

Does the Let Property Campaign apply to companies?

No. The LPC is only available to individual landlords with undeclared income from residential property. Landlords who hold property through a limited company need to correct their position through Corporation Tax filings instead.

What if I’ve already received a nudge letter?

You can usually still use the Let Property Campaign, but your disclosure will be classed as prompted, which generally means a higher minimum penalty than if you’d come forward first. It’s still typically far better than waiting for a formal enquiry to open.

Will using the Let Property Campaign guarantee I avoid prosecution?

The LPC does not offer a formal, legally guaranteed immunity from prosecution in the way that Code of Practice 9 does. In practice, criminal prosecution of landlords who make a full, honest disclosure is rare, because HMRC’s primary objective is recovering the tax owed rather than pursuing individuals through the courts.

Categories
Articles Blogs

Let Property Campaign 2026: The Complete Guide for Landlords & Property Owners

If you’ve earned rental income from a UK residential property and it hasn’t been fully declared to HMRC, you’re not alone — and there’s a structured, HMRC-endorsed way to fix it before it becomes a bigger problem. The Let Property Campaign (LPC) is HMRC’s voluntary disclosure route specifically for landlords, and coming forward through it is almost always cheaper and less stressful than waiting to be found.

With HMRC’s data-matching capability now cross-referencing letting agents, land registries, tenancy deposit schemes, and bank records, the odds of an undisclosed letting going unnoticed are shrinking every year. This guide covers who the campaign is for, what income it covers, the disclosure process step by step, real penalty figures, and the mistakes that most often cost landlords money.


Not sure if the Let Property Campaign applies to your situation? Get a free discovery call with our team and we’ll talk through your exact position.

👉 Book your free discovery call


What the Let Property Campaign Actually Is

Launched by HMRC in September 2013, the Let Property Campaign gives individual landlords a route to voluntarily correct undeclared or under-declared UK rental income. Landlords who use it before HMRC opens an enquiry can benefit from:

  • Meaningfully reduced penalties
  • Protection from criminal prosecution in genuine, cooperative cases
  • A more efficient, less adversarial resolution than a full compliance check

Why HMRC Runs This Campaign

HMRC’s rationale is straightforward: property income is unusually easy to detect. Letting agent records, land registry filings, council tax data, tenancy deposit scheme registrations, and even bank deposit patterns can all flag an undisclosed letting without the landlord ever coming forward. Add in AI-driven data-matching campaigns targeting Airbnb hosts, agent-managed lettings, and council-tax-registered non-payers, and the picture is clear: HMRC increasingly finds these cases on its own. The campaign exists to reward the landlords who get there first.

The numbers back this up. Over 40,000 disclosures have now been made through the campaign, recovering more than £180 million in previously unpaid tax.

What Income Is Covered Under the LPC

The campaign covers a broad range of residential letting situations, not just traditional buy-to-let. You should be looking at the LPC if any of the following apply to you:

Letting out residential property — a single flat or a full portfolio, whether it came about deliberately or by accident (inheritance, relocation for work), located in the UK or abroad, as long as the income is subject to UK tax.

Short-term and holiday lets — Airbnb income, serviced accommodation, furnished holiday lettings, and any seasonal or short-term letting income.

Rent-a-room and subletting — income from letting a room in your own home once you exceed the £7,500 rent-a-room threshold, or subletting arrangements not already reflected on your return.

Inherited or temporarily let property — a property you’ve inherited and started renting, or letting your own home during a period abroad or a temporary absence.

Previously missed or under reported periods — years where the property was let but the income wasn’t declared, even briefly, or where a return was filed with errors.

Overseas and international lettings — UK residents with rental income from property abroad, and non-UK residents with rental income from UK property.

Who Should Use the LPC

The campaign is designed for landlords who:

  • Have rental income that’s never been declared to HMRC
  • Made errors on previous returns — under reported income, over-claimed expenses
  • Didn’t realise rental income needed reporting at all, regardless of whether it generated a profit

One point catches a lot of landlords out: even if allowable expenses wipe out your taxable profit entirely, you’re still legally required to report the income and expenses. Making no profit is not the same as having nothing to declare.

Common real-world scenarios

  • Inheriting a parent’s home and renting it out without telling HMRC
  • Becoming a landlord while working abroad, letting your UK home without realising it still needs reporting
  • Renting a spare room informally, assuming the amount is too small to matter
  • Moving in with a partner and letting your previous home without updating HMRC
  • Assuming a letting agent was handling the tax reporting (HMRC holds the landlord personally responsible, not the agent)
  • Misapplying mortgage interest relief rules, particularly following the 2020 change to a 20% tax credit
  • Jointly owned property where reporting responsibilities weren’t clearly split between owners

Who’s Eligible — and Who Isn’t

You’re eligible if you’re:

  • An individual (not a company, trust, or partnership)
  • Earning income from UK residential letting — including buy-to-let, Airbnb, accidental landlord situations, and non-resident landlords with UK property
  • Willing to disclose fully and voluntarily, before HMRC has opened an enquiry — meaning a complete declaration of all under-reported income, full transparency on years and documentation, and a genuine willingness to resolve what’s owed

You’re excluded if:

  • HMRC has already opened a compliance check or raised questions about your rental income — in this case you must respond directly to that enquiry instead
  • Your income comes from non-residential property (offices, shops, industrial units) — the LPC covers residential letting only
  • You’re a company, trust, or partnership, which need to use a different HMRC disclosure route

Worth noting: if you hold a mixed portfolio, only the residential portion qualifies for LPC — commercial property needs separate arrangements. Joint owners each need to make their own individual disclosure for their share of the income, and non-UK residents with UK rental income remain eligible if they meet the other criteria.

The Disclosure Process, Step by Step

1. Register your intent with HMRC Access the LPC service on GOV.UK and submit your details, including your National Insurance number, through the Digital Disclosure Service (DDS). HMRC issues a Disclosure Reference Number (DRN) and Payment Reference Number (PRN) — keep both, as they’re needed throughout.

2. Gather your information Pull together rental income figures for every relevant year, including years spent abroad or where the property stood empty part-time. Supporting documents matter here — tenancy agreements, mortgage interest records, utility bills, maintenance invoices, council tax records, and bank statements.

3. Calculate what’s owed Work out gross rental income, allowable expenses, and any capital allowances. HMRC’s online calculators can help, though complex cases usually benefit from a tax advisor. Don’t forget interest on the late tax — and be aware that penalties will be set according to your behaviour category (careless, deliberate, or concealed).

4. Submit your disclosure Complete the full disclosure through the DDS portal, explaining clearly why the errors or omissions occurred and what you’ve done to correct them. You have 90 days from receiving your DRN to submit.

5. Pay what’s due Once you’ve registered your intent, you’ll receive a payment reference to settle the total tax, interest, and penalty — either in full or through an agreed payment arrangement discussed directly with HMRC beforehand.

6. Confirmation and closure HMRC reviews the disclosure; honest, thorough submissions tend to close fastest. If further information is needed, respond promptly. Once accepted, HMRC issues a closing letter confirming the total amount payable, the period covered, any payment arrangement, and that the case is closed provided the terms are met.

Staying Compliant After Your Disclosure

Closing an LPC case isn’t the end of the story. Going forward, you’ll need to:

  • Declare all rental income and expenses on your annual Self Assessment return, regardless of profit or loss
  • Keep organised records for at least six years — receipts, agreements, correspondence — in case HMRC requests them later
  • File and pay by the 31 January deadline each year to avoid fresh penalties and interest
  • Stay current with HMRC guidance, since rules on allowable expenses and digital filing do change — HMRC’s Property Rental Toolkit is a useful reference
  • Revisit your position with a tax advisor whenever circumstances shift — new properties, overseas lettings, changes in tax residency

Our tax-saving strategies guide is a good next step once you’re back in good standing, for legitimate ways to manage the ongoing liability.

Real Disclosure Examples

The accidental landlord. Emma inherited her mother’s flat and let it out from 2018 without informing HMRC. Realising the gap in 2025, she disclosed £6,000 of undeclared rent through the LPC and, because she came forward voluntarily, paid only a 10% penalty with no further action.

The overseas landlord. Ajay relocated to Spain for work and let out his former UK home, unaware of his ongoing UK tax obligations as a non-resident. After receiving a nudge letter from HMRC, he used the LPC — working with a tax advisor to declare five years of rental profit — and secured a low penalty rate.

The inherited property. James inherited a house in 2017, let it out, and only recognised the reporting requirement in 2025. He used the LPC to settle seven years of unpaid tax plus interest, with a 15% penalty.

For a deeper look at how the maths plays out with real figures, our article on Let Property Campaign voluntary disclosure walks through two full case studies comparing voluntary versus prompted disclosure costs.

How Long Does a Disclosure Take?

Most LPC disclosures run 12–16 weeks from initial registration to final resolution, covering preparation, submission, and any follow-up queries or payment arrangements. Complex cases or gaps in documentation can extend this considerably.

Are LPC Cases Increasing?

Yes. In 2023, HMRC flagged over 18,000 property-related cases for compliance review — a figure expected to keep climbing as digital data-matching against letting agent returns, land records, and banking data becomes more sophisticated. The wider the net gets, the more voluntary, proactive disclosure makes financial sense.

How Penalties Are Actually Calculated

Penalties depend on several factors working together: the nature of the error (careless, deliberate, or deliberate and concealed), whether the disclosure was unprompted or prompted by HMRC contact, how long the omission persisted, and the quality of your cooperation.

There are two broad scenarios that trigger penalties — failure to notify HMRC of taxable income at all, and inaccurate returns where income was filed but understated. Both are calculated as a percentage of the additional tax owed (the “Potential Lost Revenue”), and a high-quality disclosure can cut that percentage by up to 90% within its range.

Voluntary, honest disclosure typically sits in the 0–20% penalty range — the lowest available — provided you’re fully cooperative, prompt, and transparent.

Prompted disclosure, where HMRC contacts you first, loses access to that leniency: rates run higher, sometimes double the voluntary range, even with full cooperation afterwards.

Deliberate or concealed behaviour carries the steepest penalties, typically 35–100% of the tax owed, and in the most serious cases can lead to criminal prosecution.

Reasonable care cases — genuine mistakes made despite taking sensible steps to get things right — can, in some circumstances, see the penalty waived entirely.

Key Takeaways

  • Voluntary disclosure before HMRC makes contact consistently produces the lowest penalty range, typically 0–20% of the tax owed
  • The quality of your disclosure — being open, prompt, and thorough — drives further reductions within that range
  • Genuine mistakes made with reasonable care can sometimes avoid a penalty altogether
  • Deliberate concealment carries the harshest consequences, both financially and legally
  • Professional guidance consistently improves outcomes — accurate figures, complete documentation, and a well-presented case all reduce the eventual penalty

Common Mistakes to Avoid

Only declaring recent years. HMRC can require disclosure going back up to 20 years for deliberate or concealed errors — review every year with missing or inaccurate figures, not just the obvious ones.

Misclassifying allowable expenses. Since April 2020, mortgage interest relief works as a 20% tax credit rather than a straight deduction — a common source of error.

Leaving out overseas property. Worldwide rental income is re-portable if you’re UK tax resident, not just UK-based lettings.

Doing the calculations yourself. Self-calculated figures frequently miss reliefs or misstate the tax owed — a second set of eyes from a qualified accountant catches this before HMRC does.

Missing the 90-day window. Once you’ve registered, the clock is running — late submission can forfeit the penalty reductions you’d otherwise qualify for.

Assuming the letting agent handles it. The legal responsibility for reporting sits with the landlord, regardless of what an agent manages day to day.

Assuming no profit means nothing to declare. All rental income needs reporting even where allowable expenses bring the taxable profit to zero.

Waiting to be contacted. A disclosure made after a nudge letter is a prompted disclosure — and loses the best penalty terms by definition.

Incomplete documentation. Missing tenancy agreements or bank statements can stall a disclosure or undermine its credibility — keep thorough records for every property and year involved.

When to Bring In Professional Help

Certain situations tend to benefit most from specialist advice:

  • More than four years of undeclared income, where the calculations and documentation requirements get more complex
  • Multiple properties or overseas lettings, which can introduce double taxation questions and varying expense rules
  • Complicated expense positions — joint ownership, furnished holiday lettings, or major repair and improvement claims

As one chartered tax advisor puts it, the Let Property Campaign is a genuine opportunity to regularise your affairs on favourable terms — provided the disclosure is accurate and the communication with HMRC stays open throughout.

Frequently Asked Questions

Do I need to use the LPC if I’ve already reported my rental income? No — the campaign is specifically for correcting income that wasn’t declared, or was declared incorrectly. If your returns are already accurate, there’s nothing to disclose.

Who can use the LPC? Individual landlords — not companies, trusts, or partnerships — with undeclared or under-declared UK residential rental income, whether they’re UK resident or overseas.

What happens if HMRC contacts me first? You move from a voluntary to a prompted disclosure, which carries higher penalty rates and less flexibility, though cooperation still helps.

What if I can’t afford to pay what’s owed right now? Contact HMRC’s LPC helpline before submitting your disclosure or any payment — they can discuss a realistic payment arrangement based on your financial position.

What expenses can I claim against my rental income? Allowable expenses generally include letting agent fees, repairs and maintenance, insurance, and a mortgage interest tax credit (since the 2020 rule change) — a tax advisor can confirm what applies to your specific setup.

How many years do I need to disclose? It depends on why the income wasn’t declared — careless errors typically mean up to six years, deliberate or concealed behaviour can extend that to twenty. Our guide on which years to declare breaks this down in detail.

Will I be prosecuted? Prosecution is reserved for the most serious, deliberate, and concealed cases. Honest, cooperative voluntary disclosures are very rarely treated this way.

Quick Reference Tips

  • Joint landlords each need to submit their own individual disclosure
  • Overseas landlords should check whether double taxation arrangements apply to their situation
  • Keep documentation for at least six years after your disclosure is closed
  • If older records genuinely don’t exist, explain this within the disclosure — HMRC will generally work from a reasonable best estimate
  • Get advice from a specialist tax advisor if your case involves overseas property, joint ownership, or inheritance complexities

Final Thoughts

The Let Property Campaign remains one of the most practical routes HMRC offers landlords to put things right. With data-matching only getting sharper, waiting to be contacted is the more expensive option in almost every case. Whether your situation started as an honest oversight, a life event like an inheritance, or something more complicated, coming forward on your own terms keeps you in control of the outcome.

Ready to work out exactly where you stand?

👉 Book a free discovery call
Categories
Articles Blogs News

Reporting Undisclosed Rental Income to HMRC: What Landlords Need to Know

If HMRC has never heard about some or all of your rental income, the Let Property Campaign is the mechanism built specifically to fix that. It gives residential landlords a formal way to bring past tax years up to date — and, more often than not, it’s simply a question of when you report it rather than whether HMRC eventually finds out on its own.

This guide covers how HMRC actually identifies undisclosed rental income, who the campaign is open to, the exact steps involved in making a disclosure, and what happens if HMRC pushes back on your figures.


Received a letter from HMRC, or just want to check your position before they get in touch? Book a free discovery call and we’ll talk it through.

👉 Book your free discovery call


How HMRC Actually Finds Undisclosed Rental Income

It’s tempting to assume small or informal lettings fly under the radar. In practice, HMRC pulls from a wide net of sources: letting agent records, land registry filings, council tax data, mortgage applications, and even reports from members of the public. Where the data points to rental income that hasn’t been matched against a tax return, HMRC will often reach out directly, inviting the landlord to use the Let Property Campaign to put things right.

The key detail here is timing. You don’t have to wait for that letter. Landlords who register for the campaign proactively — before any contact from HMRC — are treated more favourably, with faster resolution and materially lower penalties than those who only respond once HMRC has already made contact.

Who the Campaign Is Open To

The Let Property Campaign covers a broad range of residential landlords, including:

  • Landlords with one or more residential properties, whether in the UK or overseas
  • Individuals renting out a room in their own home under the Rent a Room Scheme
  • Landlords letting to students, workforce tenants, or similar groups
  • Holiday let landlords

Who Can’t Use It

A few situations fall outside the scope of the campaign:

  • Commercial property — shops, garages, and lock-ups aren’t covered on their own, though a mixed portfolio with a residential component can still use the campaign for that portion
  • Companies and trusts — these need to use a different disclosure route entirely; the campaign is for individuals
  • Directors and commercial landlords — separate disclosure methods apply here too

Joint ownership is treated individually, not jointly. Where a property is owned by more than one person, each owner needs to make their own separate disclosure covering their share of the profit — a single combined submission isn’t accepted.

The Disclosure Process

1. Notify HMRC of your intent If HMRC hasn’t already been in touch, you register your intention to disclose and receive a reference number in return.

2. Quantify the undisclosed income Within 90 days of getting that reference number, work out all previously undisclosed income and gains across every year HMRC can still assess — and this isn’t limited to rental income alone; any other undisclosed business or investment income within scope should be included too.

3. Calculate what’s owed Work through the additional tax, interest, and penalties due for each affected tax year.

4. Make a formal offer Submit a formal offer to HMRC to settle everything in full and final settlement of your historical position.

5. Pay using your reference number Once the offer is submitted, use your Payment Reference Number to settle the agreed amount.

6. Submit full supporting detail Alongside your calculations and offer, provide a comprehensive account of the facts and assumptions behind your figures.

What happens after submission: HMRC typically sends an acknowledgement within around two weeks, followed by internal checks. If they’re satisfied, you’ll receive a formal acceptance letter closing the matter. If not, expect follow-up questions aimed at verifying your figures.

Going forward, staying compliant means registering for Self Assessment if you haven’t already, and reporting all income and gains through your annual return from that point on.

There’s real value in professional input at this stage — not just to get the numbers right, but because there are legitimate technical arguments that can reduce both the number of years included and the resulting penalty. For a closer look at how everyday situations turn into undisclosed income in the first place, our article on common landlord tax errors is worth reading alongside this one.

How Many Years Get Included

The number of assessable years isn’t fixed — it depends on the nature of the underlying issue, and our guide on which years you need to declare covers this in full detail.

One point worth flagging clearly: if income or gains were deliberately left off a return, there’s a genuine risk of prosecution, and professional advice on your options is strongly recommended before proceeding. In cases involving deliberate conduct, the Contractual Disclosure Facility is a separate route that can offer immunity from prosecution — a very different mechanism from the Let Property Campaign, and one worth discussing with an advisor if it’s relevant to your circumstances.

What If Your Records Are Incomplete?

Missing historical records don’t remove the obligation to disclose. The expectation is a genuine effort to obtain what documentation still exists, and where gaps remain, reasonable, well-explained assumptions can be used to quantify the income and gains involved.

How the Tax Is Actually Calculated

Tax on previously undeclared profit is worked out using the rates and allowances that applied in each specific tax year in question — not current-year rates applied retrospectively. How much falls due depends on how far income sat above the tax-free personal allowance for that year, and it’s worth making sure every available relief is claimed rather than assumed away.

How the Penalty Is Set

Penalty rates vary by circumstance, but voluntary, high-quality disclosures consistently land at the lower end of the scale. The starting point also differs depending on whether returns were filed incorrectly versus never filed at all.

HMRC reduces penalties based on how the disclosure is handled — often summarised as telling, helping, and giving: coming forward with the issue, actively assisting HMRC in understanding it, and cooperating fully in establishing the correct figures. Landlords weighing up the practical cost difference between disclosing voluntarily and waiting to be contacted may find our voluntary disclosure guide useful, since it walks through real penalty comparisons with worked figures.

If HMRC Disagrees With Your Disclosure

HMRC retains the right to review any disclosure for accuracy and can challenge the assumptions behind it, including requesting the underlying records used to support the figures submitted.

Where a disagreement over the final amount can’t be resolved, HMRC may issue formal assessments for the tax and penalties it believes are due. From there, you retain the right to appeal. If an appeal doesn’t resolve things, further options remain available — including requesting an internal review or taking the matter to the Tax Tribunal for a final decision.

Getting It Right From the Start

A well-prepared disclosure, backed by accurate figures and a clear explanation of the facts, is far more likely to close quickly and without dispute. Given the technical judgement involved in scoping the right years and minimising penalties, most landlords benefit from working through this with an experienced advisor rather than navigating it alone. For the full picture on eligibility and process, our complete Let Property Campaign guide brings everything together in one place.

Ready to find out exactly where you stand?

👉 Book a free discovery call

Categories
Articles Blogs

Received a Letter From HMRC About Your Rental Income?

A letter from HMRC about undeclared rental income isn’t the same as a demand — but it is a deadline. Whether it’s a formal nudge letter or you’ve simply realised on your own that some rental income was never reported, the Let Property Campaign gives individual landlords a structured route to put things right, with a clear 90-day window to work out and pay what’s owed.

Ignoring the letter, or waiting to see whether HMRC follows up, is the one move that consistently makes things worse — penalties climb, and in the more serious cases, legal action becomes a real possibility. This guide walks through exactly what to do, in what order, and how far back your disclosure is likely to need to go.


Got a letter and not sure where to start? Book a free discovery call and we’ll help you respond correctly, within the deadline.

👉 Book your free discovery call


Doing It Yourself vs Using an Agent

You have a genuine choice here: handle the notification and disclosure yourself, or bring in an agent to manage it on your behalf. Given how much the numbers can shift depending on the correct behaviour classification and look-back period, most landlords find a professional advisor pays for themselves — particularly once the possibility of reducing the number of assessable years or the penalty rate comes into play. Either route follows the same basic sequence below.

Step 1: Notify HMRC of Your Intention to Disclose

As soon as you’re aware that tax is owed on rental income, the first move is registering your intention to disclose through HMRC’s Digital Disclosure Service. At this stage you don’t need to have your figures ready — you’re simply flagging that a disclosure is coming, whether that’s prompted by a nudge letter or done entirely on your own initiative.

Once submitted, HMRC issues a unique Disclosure Reference Number (DRN) — this becomes your reference for all further correspondence — along with a Payment Reference Number to settle the eventual liability.

One detail catches out a lot of joint owners: each person must notify and disclose separately. If a rental property is jointly owned by a married couple, for example, both need to submit their own individual notification and disclosure covering their own share of the income — a single combined submission on behalf of both isn’t accepted.

Step 2: Disclose Your Undeclared Income — Within 90 Days

Once your DRN arrives, the clock starts: you have 90 days from your notification acknowledgment to complete the full disclosure. This needs to cover all the undeclared rental income, the unpaid tax across the relevant years, and the applicable penalty rate — and payment of the full amount is due at the same time as the disclosure itself.

If you genuinely can’t pay everything by the deadline, the fix isn’t to delay the disclosure — it’s to contact HMRC before the deadline to arrange a payment plan. Missing the payment and notification deadline together is what turns a manageable situation into a more difficult one, so treat both dates as fixed.

How Far Back Does Your Disclosure Need to Go?

This is usually the question landlords care about most, and the honest answer is: it depends on why the income wasn’t reported in the first place. Landlords are required to notify HMRC of letting income by 5 October following the end of the relevant tax year — for 2023/24 income, that’s 5 October 2024, with the Self Assessment return itself due by 31 January 2025. Miss those, and the look-back period is set by which of the following applies to your situation.

You took reasonable care

If you were registered for Self Assessment on time and made genuine efforts to keep your affairs in order, but still ended up underpaying, HMRC will generally only ask you to settle up to four years. Staying compliant from here means:

  • Filing accurate, on-time returns for the current and future years
  • Reporting any outstanding tax from the prior year in the correct return, by deadline
  • Completing your disclosure and payment for the three tax years before that

You didn’t take reasonable care

Where you registered on time but ended up underpaying through carelessness — rather than a genuine, well-intentioned mistake — the look-back period extends to a maximum of six years. That means:

  • Accurately reporting the current and future tax years by their deadlines
  • Correctly reporting the year immediately before the current one, on the return issued for it
  • Completing the disclosure and settling what’s owed for the five years before that

You deliberately misled HMRC

Where income was deliberately understated, or HMRC was told nothing about it at all, the look-back period can extend to a maximum of twenty years. HMRC’s default expectation is a six-year disclosure for most landlords — the twenty-year extension is reserved specifically for cases involving deliberate misstatement or a complete failure to disclose. For a deeper breakdown of how this behaviour classification actually works in practice, our guide on which years you need to declare covers it in full.

Why Acting Before the Letter Arrives Is Still Worth Doing

If you haven’t received a letter yet but suspect your rental income position needs correcting, there’s no reason to wait for one. Voluntary disclosure — made before any HMRC contact — consistently attracts lower penalties than a disclosure triggered by a nudge letter. Our voluntary disclosure guide sets out exactly what that penalty difference looks like in practice, with real worked examples.

Putting It All Together

A letter from HMRC is a prompt, not a verdict — the outcome still depends heavily on how quickly and accurately you respond. Notify promptly, gather the right documentation for the years that matter, and get the behaviour classification right before you submit, since that single judgement call affects both how many years you’re disclosing and what penalty rate applies. For the complete picture on eligibility, process, and worked examples, our Let Property Campaign guide brings everything together in one place.

Received a letter and need help responding within the deadline?

👉 Book a free discovery call

Categories
Articles Blogs

Let Property Campaign: Know the Years You Need to Declare

Let Property Campaign: Know the Years You Need to Declare

If you’re a landlord who has discovered that rental income wasn’t reported correctly to HMRC, the first question is rarely “how much tax do I owe?” It’s “how far back does this go?”

That question trips up more landlords than almost any other part of the Let Property Campaign. There’s no single, universal answer — HMRC doesn’t apply a flat six-year rule to everyone. Instead, the number of tax years you’re required to disclose depends on why the income went unreported in the first place. Get that wrong, and you risk an incomplete disclosure, a challenge from HMRC, and additional penalties further down the line.

This guide walks through exactly how the look-back period is calculated, how HMRC’s three behaviour categories work, and the mistakes that most commonly catch landlords out.


Not sure where your disclosure should start? Book a free, no-obligation discovery call with our Let Property Campaign specialists and we’ll help you work out exactly which years apply to your situation.

👉 Book your free discovery call


Who the Let Property Campaign Is For

The Let Property Campaign is HMRC’s voluntary disclosure route for landlords whose rental income hasn’t been reported correctly — whether that’s income left off a return entirely, or a return filed with the wrong figures.

It’s built around individual landlords rather than corporate structures, and it covers a wide range of situations:

  • Landlords with a single rental property who never registered for Self Assessment
  • Portfolio landlords who missed one property among several
  • UK residents letting property overseas, and overseas residents letting UK property
  • Short-term lets that were sold before the income was ever declared
  • Landlords already in Self Assessment whose figures were wrong

There’s no minimum threshold. HMRC’s own guidance treats the campaign as open to anyone with undeclared or under-declared rental income, regardless of how small the sums involved. For a broader look at how UK rental income is taxed in the first place, our property tax guide covers the basics landlords are expected to know.

What the Campaign Does — and Doesn’t — Change

It’s worth being clear-eyed about what the Let Property Campaign actually offers.

It gives you a structured way to:

  • Come forward before HMRC finds the issue independently
  • Calculate and settle tax, interest, and penalties yourself, with HMRC’s oversight
  • Generally receive more favourable treatment than if HMRC uncovers the problem through a compliance check

It does not:

  • Cap or reduce HMRC’s legal power to assess tax
  • Let you pick a convenient disclosure period
  • Guarantee lower penalties automatically — that still depends on how the disclosure is made and how complete it is

In short, coming forward voluntarily is the advantage. The scope of what you need to disclose is still governed entirely by HMRC’s rules, not by your preference.

Why “Behaviour” Is the Deciding Factor

Here’s the part that catches people out: the number of years you must go back is not fixed. It’s determined by HMRC’s assessment of why the tax went unpaid — referred to as your “behaviour.”

This matters for a legal reason, not just a moral one. The standard assessment window is limited, but HMRC can extend it — to six years or even twenty — only where specific statutory conditions are met. Those conditions hinge on whether the loss of tax resulted from carelessness or from a deliberate decision not to declare.

Get the behaviour classification wrong on your disclosure, and HMRC can challenge it later — reopening a case you thought was closed.

Careless behaviour → normally up to 6 tax years

This applies where reasonable care wasn’t taken, but there was no intent to avoid tax. Typical examples include:

  • Not realising rental income needed declaring at all
  • Misapplying the rules on allowable expenses
  • Errors on a return that went unchecked

HMRC assesses “reasonable care” against what a sensible, prudent person in the landlord’s position would have done. Using an accountant is actually meaningful evidence here — it can support the argument that reasonable care was taken, even if a mistake still occurred.

Example: A landlord claims expenses that turn out not to be allowable, purely from misunderstanding the rules, and it’s picked up years later. This typically results in a six-year disclosure.

Deliberate behaviour → up to 20 tax years

This is where rental income was left out knowingly — not through misunderstanding, but by choice. Examples include:

  • Receiving rent and simply not declaring it
  • Knowing tax registration was required and not doing it
  • Repeated, ongoing omission of rental income from returns

Example: A landlord has let a property since 2010 and knowingly never registered for tax on the income. Because the letting activity — and the unpaid tax — started in 2010/11, that’s where the disclosure begins, not an arbitrary twenty years prior.

Deliberate and concealed behaviour → up to 20 tax years, with heavier penalties

The most serious category applies where income wasn’t just omitted, but active steps were taken to hide it — for example, rent paid into an account not linked to the landlord’s name, no records kept at all, or misleading information given if questioned. The look-back period mirrors deliberate behaviour, but penalties sit at the top end of the scale.

How Behaviour Affects Penalties and Interest

Behaviour doesn’t only decide how far back you go — it drives the penalty range too. Careless errors sit at the lower end; deliberate and concealed behaviour at the top. On top of any penalty, interest accrues separately on the unpaid tax from the original due date until it’s settled, regardless of category.

This is why correctly identifying — and being able to justify — your behaviour category matters as much as the arithmetic. Landlords weighing up how to minimise the overall cost of a disclosure may also find it useful to look at our guide to tax-saving strategies for legitimate ways to manage the ongoing liability once matters are up to date.

Working Out Which Years Actually Belong in Your Disclosure

Once you know your behaviour category, the next step is translating that into an actual list of tax years. This isn’t a matter of picking a convenient starting point — it follows a specific logic.

1. Start with the most recent tax year. If a return is already due for the latest year, that’s usually handled through normal Self Assessment rather than folded into the historic disclosure — the Let Property Campaign is then used to correct everything before it.

2. Count backwards using your behaviour category. Up to six years for careless behaviour, up to twenty for deliberate or concealed behaviour — but only as far as there was genuine letting activity and unpaid tax. If the property wasn’t let, or there was no under-declared income, in an earlier year, that year simply isn’t part of the disclosure.

3. Confirm each year actually generated a tax liability. More on this below — not every year within the look-back window needs to be included.

Careless example: An error identified in 2025 typically means reviewing 2019/20 through 2024/25 — the six most recent tax years — and including only the ones with genuine underpaid tax.

Deliberate example: Letting began in 2010/11 and income was knowingly withheld. Because that’s when the tax loss started, the disclosure runs from 2010/11 forward — not from an earlier, arbitrary date.

When Your Behaviour Isn’t Consistent Throughout

It’s common for a landlord’s situation to shift over time — genuine confusion in the early years, followed later by a conscious decision not to declare once the rules became clear.

Where that happens, HMRC applies the most serious behaviour identified across the whole period when deciding how far back it can assess. A change from careless to deliberate partway through can therefore extend the maximum look-back significantly — even though the earliest years were a genuine mistake.

Example: A landlord starts letting in 2014/15 and doesn’t realise the income is taxable until 2018/19, from which point they’re aware but continue not declaring. The later deliberate conduct means HMRC can, in principle, assess up to twenty years — but because letting only began in 2014/15, that’s still the actual start of the disclosure.

Do You Have to Include Years With No Tax Due?

Not automatically. If, after allowable expenses, a year produced a loss rather than a profit, HMRC’s guidance says that year doesn’t need to be included in the disclosure figures — because no tax was underpaid.

That doesn’t mean loss years are irrelevant, though. Rental losses can be carried forward against future profits, so it’s worth keeping the calculations and supporting evidence for those years even if they’re excluded from the disclosure itself.

Low rental income is a different matter from a loss. If a year generated modest income but tax was still underpaid, that year belongs in the disclosure — the test is whether tax was due, not how much income there was.

Missing or Incomplete Records

Gaps in your paperwork are common, especially for lettings going back a decade or more — and they don’t remove the obligation to disclose. HMRC expects a reasonable, honestly reconstructed estimate rather than perfect records.

In practice, that usually means piecing figures together from:

  • Bank statements showing rental receipts and related payments
  • Letting agent statements or tenancy agreements
  • Surviving invoices, or realistic estimates based on the type of property and period involved

The estimate needs to be consistent and defensible — inflating costs or understating income to fill gaps undermines the whole disclosure. Where records genuinely don’t exist, say so plainly as part of the submission; HMRC’s guidance acknowledges this happens and expects a fair attempt, not certainty.

Mistakes Landlords Commonly Make With Disclosure Years

Most problems with Let Property Campaign disclosures come down to a handful of recurring errors:

  • Assuming a flat six-year rule applies to everyone, regardless of behaviour
  • Excluding a low-income year that still owed tax, confusing “small” with “no liability”
  • Understating earlier behaviour as careless when it later became deliberate, risking a challenge and an extended look-back
  • Overlooking a whole property or letting period — a short let, an informally rented room, or overseas income that got missed
  • Delaying the disclosure because records are incomplete, when a reasonable estimate would have been accepted

Each of these can slow the process down or trigger further HMRC questions, so it’s worth getting the classification and the years right before you submit rather than after.

Frequently Asked Questions

Does HMRC always go back six years? No. Six years applies to careless behaviour. Deliberate or concealed behaviour can extend the look-back to twenty years.

Can I leave out a year because I don’t have full records? No — missing records don’t remove the obligation to disclose. A reasonable, well-explained estimate is expected instead.

Do I need to include a year where the property made a loss? Generally no, if no tax was actually due for that year. Keep the figures anyway, since losses can carry forward.

What if my reason for not declaring changed over time? HMRC applies the most serious behaviour identified across the whole period, which can extend the maximum assessable years even if the issue started as a genuine mistake.

Getting Local, Specialist Help

Because the correct disclosure period depends so heavily on the specific facts of your case, generic guidance can only take you so far. Our Let Property Campaign specialists work with landlords across the UK, including in:

Summary

The number of years you need to disclose under the Let Property Campaign comes down to why the income wasn’t declared correctly — not a fixed rule. Careless errors typically mean a six-year look-back; knowingly withheld income can extend that to twenty. Within that window, only years with genuine letting activity and underpaid tax need to be included, and incomplete records are addressed with reasonable estimates rather than used as a reason to delay.

Getting the years — and the behaviour classification behind them — right the first time is what keeps a disclosure from being challenged or extended later.

Ready to find out exactly which years apply to you?

👉 Book a free discovery call.


Categories
Articles Blogs FAQs Guides

How to Reduce Property Tax Legally: A UK Landlord’s Guide for 2026

Every UK landlord pays property tax somewhere along the way. It shows up when you buy, when you let, and again when you sell.

The good news: HMRC offers real reliefs and allowances. Used correctly, they cut your bill without breaking a single rule.

This guide covers the legitimate strategies that actually work in 2026, from allowable expenses to Capital Gains Tax planning.

Claim Every Allowable Expense

The simplest way to reduce property tax is also the most overlooked. Many landlords miss deductions they are fully entitled to claim.

An expense qualifies if it is incurred wholly and exclusively for letting the property. Common allowable costs include:

  • Letting agent and management fees
  • Landlord insurance and accountancy fees
  • Repairs and maintenance that restore, not improve, the property
  • Ground rent, service charges, and council tax paid by the landlord
  • Marketing, advertising, and property-related travel

Improvements, like a loft conversion or a new kitchen extension, do not count as a running cost. Keep those receipts anyway. They can reduce Capital Gains Tax when you eventually sell.

Use the Property Income Allowance

Landlords with modest rental income can claim a flat £1,000 property income allowance instead of itemizing expenses. This works well for a single room or a low-cost let, where actual expenses fall below that figure.

You cannot claim both the allowance and itemised expenses on the same income. Compare both routes each year and pick whichever produces the lower tax bill.

Understand the Mortgage Interest Restriction

Since April 2020, individual landlords cannot deduct mortgage interest directly from rental income. Instead, they receive a 20% basic-rate tax credit on finance costs.

This rule, often called Section 24, pushes many landlords into a higher tax band than their true cash profit suggests. It applies to individuals, not to limited companies, which explains why incorporation has become popular for larger portfolios.

Pension contributions offer one legal workaround. Contributing to a pension reduces your adjusted net income, which can pull your rental profit back under the higher-rate threshold.

Rental Profit Tax Treatment: Individual vs Limited Company

StructureMortgage Interest TreatmentTax on Profit
Individual landlord20% tax credit onlyIncome Tax up to 45%
Limited companyFully deductibleCorporation Tax 19%–25%

Portfolio size and personal tax rate decide which structure saves more overall.

Split Ownership With a Spouse or Civil Partner

Married couples and civil partners can transfer property ownership, or a share of it, between themselves without triggering Capital Gains Tax or Stamp Duty on the transfer itself.

Using a Deed of Trust alongside HMRC’s Form 17, couples can allocate rental income toward whichever partner pays the lower tax rate. This uses two personal allowances and two basic-rate bands instead of one.

![Suggested image: An illustration of a house split between two overlapping circles representing joint ownership, minimal flat design]

Plan Capital Gains Tax Before You Sell

Selling a rental property can trigger Capital Gains Tax on the increase in value since purchase. A few legal strategies reduce that bill.

  • Use your annual exempt amount. Individuals get a £3,000 tax-free allowance each year, and it cannot be carried forward.
  • Transfer assets to a spouse first. Transfers between spouses are tax-free, effectively doubling the exempt amount to £6,000 before a joint sale.
  • Time the disposal. Splitting a sale across two tax years can use two separate annual exemptions.
  • Offset losses. Capital losses from other assets can reduce a taxable property gain in the same year.
  • Claim Private Residence Relief. If the property was ever your main home, part of the gain may be exempt.

Current CGT rates on residential property sit at 18% for basic-rate taxpayers and 24% for higher and additional-rate taxpayers.

Consider the Rent a Room Scheme

If you let a furnished room in your own home, the Rent a Room Scheme lets you earn up to £7,500 a year completely tax-free. No expense claims are needed, since the allowance already covers your costs.

Compare this against claiming actual expenses if your costs regularly exceed the scheme’s threshold.

Claim Replacement of Domestic Items Relief

Landlords who replace furniture, appliances, or furnishings in a let property can deduct the cost of a like-for-like replacement from rental income. This relief applies even though buying the original item would not have qualified.

Keep receipts for both the old and new item to support your claim if HMRC ever asks questions.

Stay Compliant With Making Tax Digital

From April 2026, landlords with combined property and self-employment income over £50,000 must follow Making Tax Digital for Income Tax rules. This means quarterly digital updates instead of one annual tax return.

Staying compliant matters here for a simple reason: legitimate property tax reduction depends on accurate, well-documented records. Digital software makes it far easier to track allowable expenses as they happen, rather than reconstructing them months later.

Frequently Asked Questions

Can I deduct mortgage interest from rental income?

Not directly. Since April 2020, individual landlords receive a 20% basic-rate tax credit on mortgage interest instead of a direct deduction. This can push rental profit into a higher tax band than actual cash profit suggests. Limited companies still deduct finance costs in full, which is why many larger portfolios incorporate.

What expenses can landlords claim against tax?

Landlords can claim letting agent fees, insurance, accountancy costs, repairs, ground rent, service charges, and property-related travel. Expenses must be incurred wholly and exclusively for letting the property. Capital improvements, like an extension, don’t qualify as running costs but can reduce Capital Gains Tax on a future sale.

How does the property income allowance work?

The £1,000 property income allowance lets landlords deduct a flat amount instead of itemizing expenses. It suits landlords with low running costs, such as a single let room. You cannot claim both the allowance and actual expenses on the same rental income in one tax year.

Can I transfer property to my spouse to reduce tax?

Yes. Transfers between spouses and civil partners are exempt from Capital Gains Tax and Stamp Duty. Combined with a Deed of Trust and Form 17, couples can allocate rental income to the lower-earning partner, reducing the household’s overall property tax bill legally and effectively.

How much is Capital Gains Tax on selling a rental property?

Individuals pay 18% Capital Gains Tax on gains within the basic-rate band, and 24% above it, after the £3,000 annual exempt amount. Transferring part ownership to a spouse before sale, or splitting a disposal across tax years, can legally reduce the final property tax bill.

Is buying property through a limited company more tax efficient?

Often, yes, for higher-rate taxpayers and larger portfolios. Limited companies pay Corporation Tax at 19%–25% and deduct mortgage interest in full, unlike individual landlords. Smaller portfolios and basic-rate taxpayers may find personal ownership simpler once mortgage and admin costs are considered.

What is the Rent a Room Scheme?

The Rent a Room Scheme lets homeowners earn up to £7,500 a year tax-free from letting a furnished room in their own home. No expense claims are required, since the allowance already accounts for running costs. It only applies to your main residence, not a separate rental property.

Do I need to register for Making Tax Digital as a landlord?

From April 2026, landlords with combined property and self-employment income above £50,000 must follow Making Tax Digital for Income Tax, filing quarterly digital updates. The threshold drops to £30,000 in April 2027. Limited company landlords are not affected by this rule at this stage.

How to Reduce Property Tax Legally: A UK Landlord’s Guide for 2026
Book Your Comprehensive Property Tax Review


Categories
Articles Blogs FAQs Guides

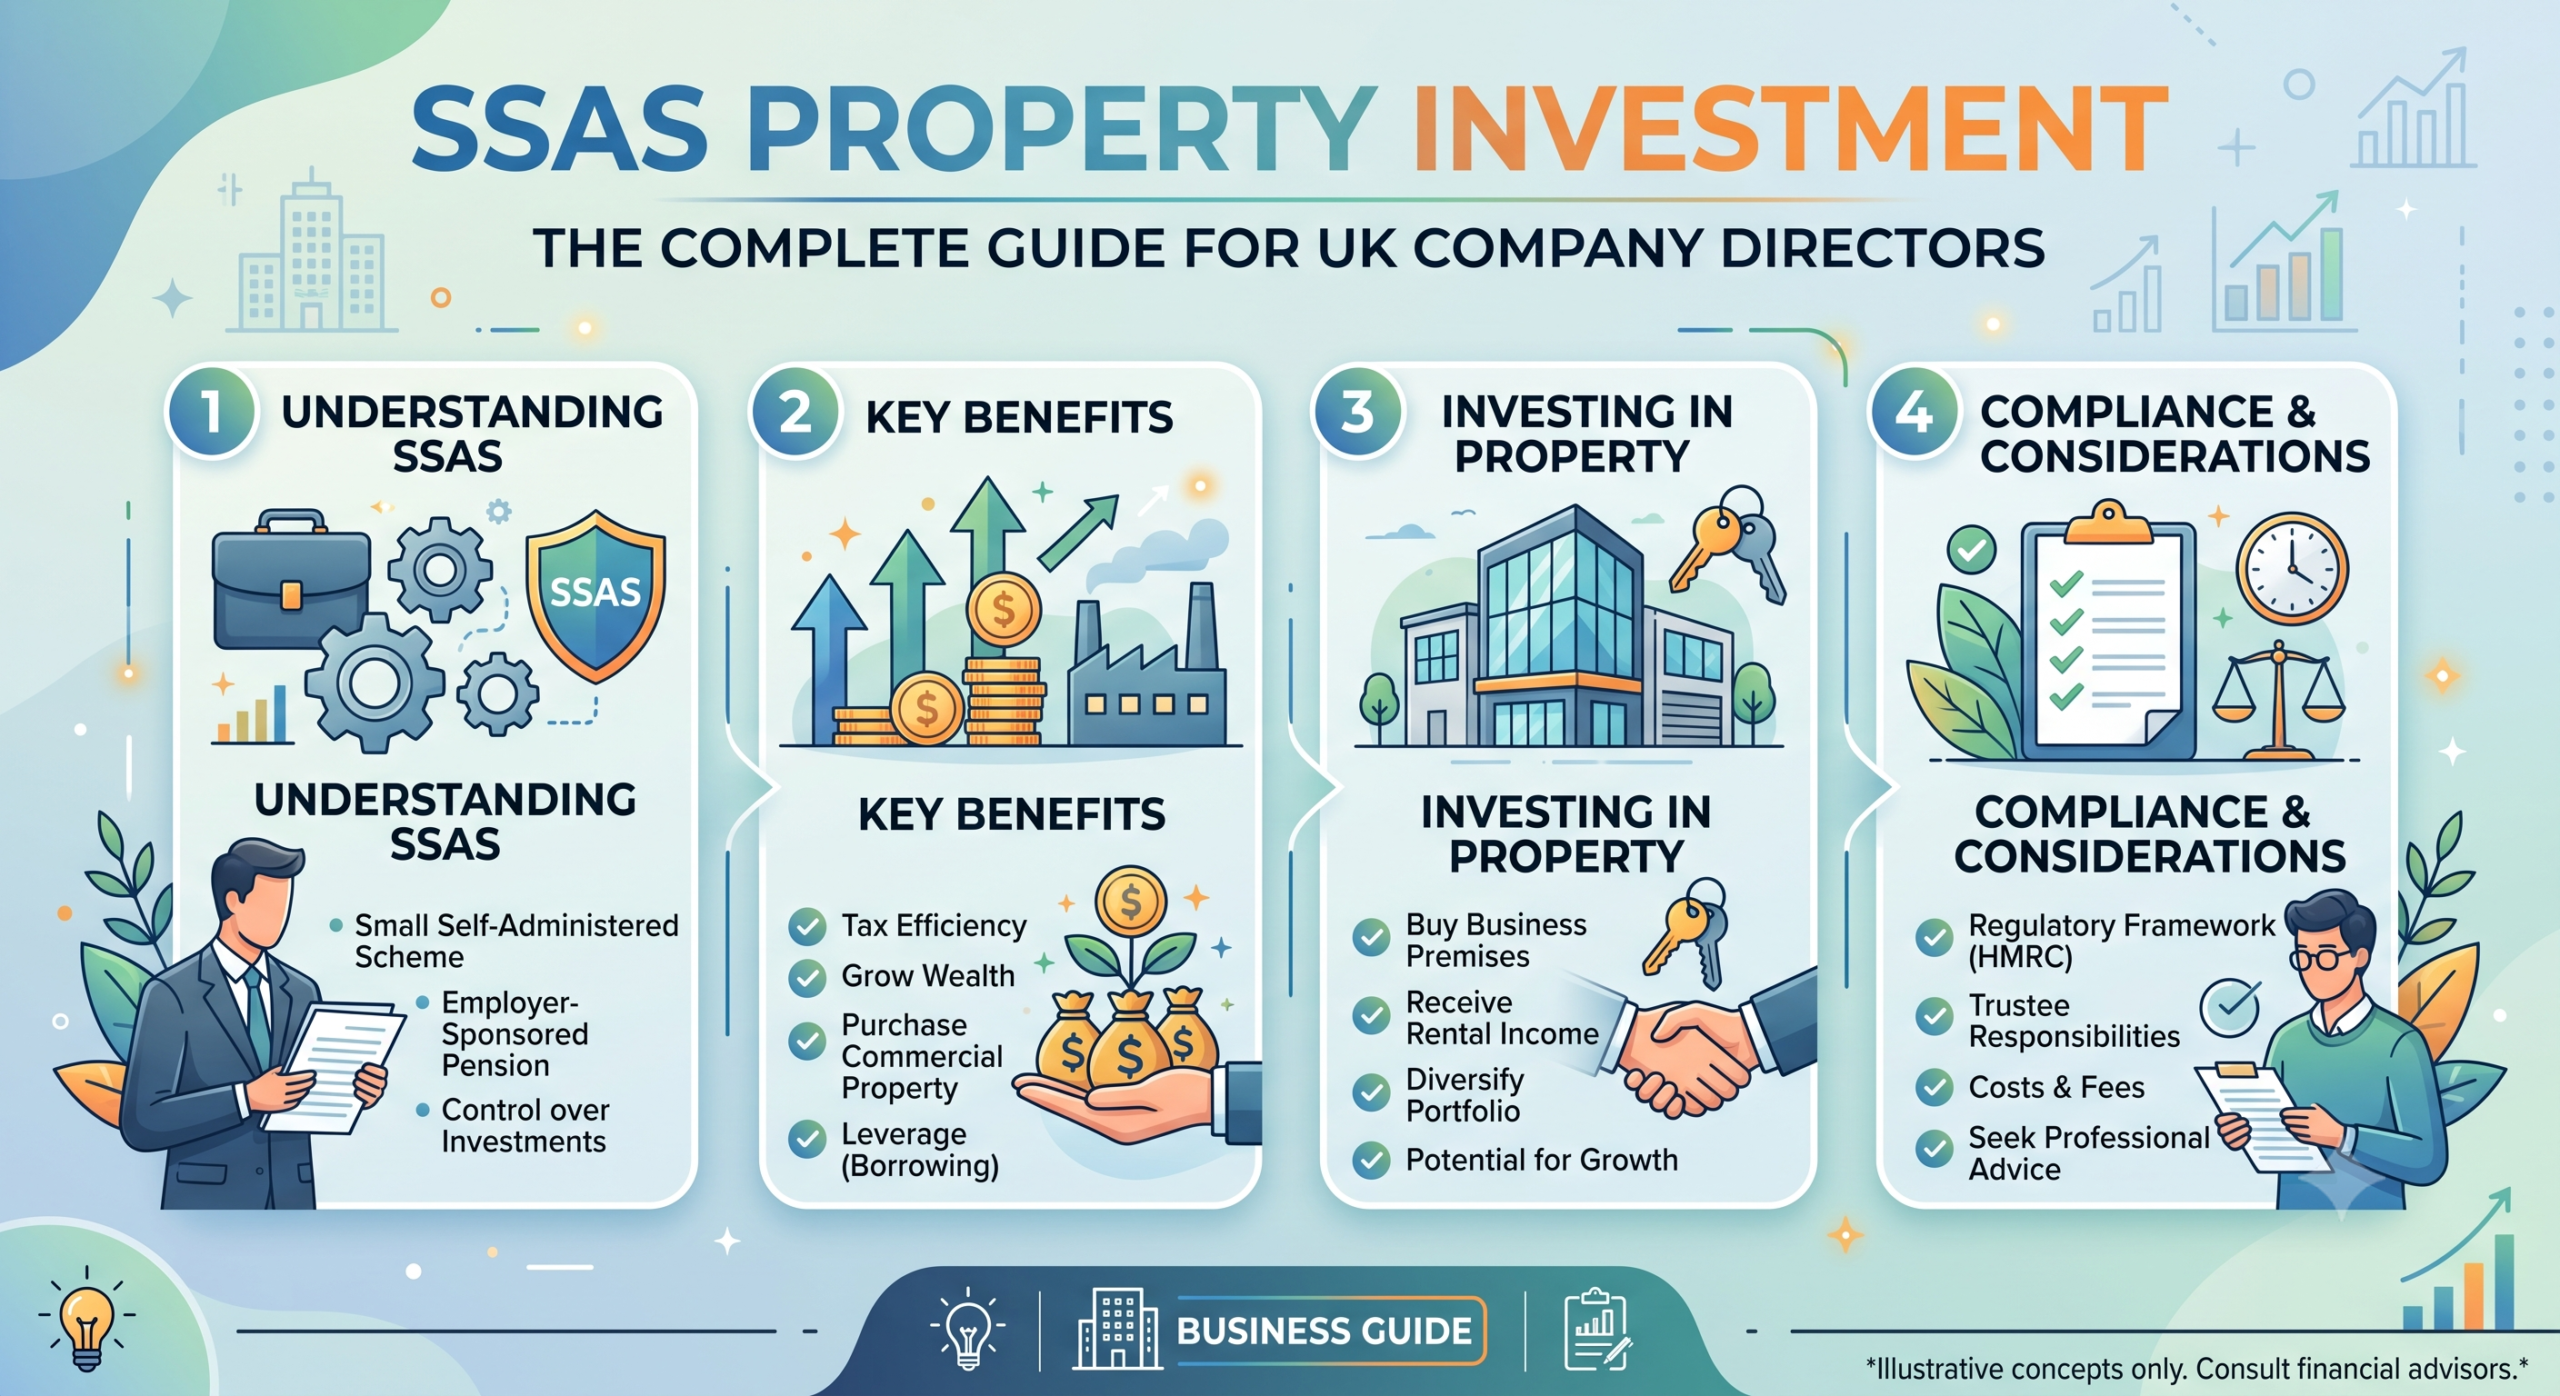
SSAS Property Investment: The Complete Guide for UK Company Directors

If you run a limited company, SSAS property investment lets you buy commercial premises through your own pension scheme. Rent flows into your pension, not a landlord’s pocket. Growth builds up tax-free. You keep control over every decision.

This guide breaks down how it works, what HMRC allows, and where directors get it wrong.

What Is a SSAS Pension?

A Small Self-Administered Scheme (SSAS) is an occupational pension trust. A limited company sets it up for its directors, senior staff, and sometimes family members.

Unlike a workplace pension, a SSAS gives members direct control. Members usually act as trustees too. That means you decide where the money goes.

This control is the whole point of SSAS property investment. A standard pension hands you a fund menu. A SSAS lets you buy an actual building.

How SSAS Property Investment Works

Trustees can use scheme funds, plus borrowing, to purchase premises. The company can then lease that property back from the pension.

Three features make this strategy work:

  • Rental income lands in the pension tax-free
  • Growth on the property is free of Capital Gains Tax
  • Contributions attract Corporation Tax relief for the company

The result is a building your business uses, sitting inside a tax-efficient wrapper.

The Commercial-Only Rule

HMRC only allows commercial property inside a SSAS. This includes offices, warehouses, retail units, factories, and land with planning permission for commercial use.

Residential property is banned. Direct ownership of a house, flat, or buy-to-let triggers an unauthorised payment charge. That penalty runs as high as 55%.

There is one narrow exception. A residential unit tied to a commercial use, like a flat above a shop occupied by staff, may qualify. The rules here are strict, and the flat’s occupant cannot be connected to any SSAS member.

How Much Can a SSAS Borrow?

Trustees can borrow up to 50% of the scheme’s net asset value. Lenders typically secure this as a commercial mortgage against the property itself.

SSAS Net AssetsMaximum Borrowing (50%)Total Buying Power
£400,000£200,000£600,000
£600,000£300,000£900,000
£1,000,000£500,000£1,500,000

This borrowing limit gets tested once, at the point the loan is taken out. It does not get retested if property values later fall.

SSAS vs SIPP for Property Investment

Both a SSAS and a SIPP (Self-Invested Personal Pension) can hold commercial property. The two structures differ in important ways.

FeatureSSASSIPP
Who can joinCompany directors and familyAny individual
Trustee controlMembers are usually trusteesProvider acts as trustee
Pooling fundsMultiple members can pool pensionsCannot pool with others
Loan to sponsoring companyYes, up to 50% of net assetsNot permitted

The loan back facility is the biggest difference. It lets a SSAS lend money directly to the business that set it up, something a SIPP cannot do.

Tax Benefits of SSAS Property Investment

Directors choose SSAS property investment because the tax treatment beats owning property personally or through the trading company.

  • No Income Tax on rent. Rental payments from the tenant company go straight into the pension.
  • No Capital Gains Tax. Selling the property inside the scheme creates no CGT liability.
  • Corporation Tax relief. Employer contributions into the SSAS reduce the company’s taxable profit.
  • Asset protection. The property sits outside the trading company, away from business creditors.

These benefits only apply while the scheme follows HMRC’s rules exactly.

Risks and Compliance Traps

A SSAS rewards careful trustees. It punishes careless ones.

Unauthorized payments. Buying residential property, letting a member use scheme assets personally, or breaching connected-party rules all trigger tax charges.

Trading vs investment. Holding one commercial unit for rental income counts as investment. Buying, developing, and flipping properties on rotation can look like trading. HMRC treats trading activity differently, and it can lose its tax-free status.

Concentration risk. Tying most of your pension into one building leaves your retirement fund exposed if the tenant company struggles.

Valuation and lease terms. Rent must be set at an independent, arm’s-length market rate. An artificially low rent can also count as an unauthorized payment.

How to Set Up a SSAS for Property Investment

  1. Appoint a professional trustee. Most schemes need a qualified SSAS practitioner alongside the member trustees.
  2. Register the scheme with HMRC. The SSAS becomes a registered pension scheme once approved.
  3. Transfer or contribute funds. Members can transfer old pensions in, and the company can make contributions.
  4. Instruct a solicitor and surveyor. Property purchases need an independent valuation and full legal searches.
  5. Agree a formal lease. The company signs a commercial lease with the SSAS at market rent.

A Simple Example

Sarah transfers £400,000 from old pensions into a SSAS. Her company adds £100,000 as an employer contribution, gaining Corporation Tax relief.

The scheme now holds £500,000 in cash. Trustees buy a freehold office building outright, with no borrowing needed.

The company signs a lease at £36,000 a year in rent. That rent flows into Sarah’s pension tax-free, growing her retirement fund while her business gets a permanent home.

Is SSAS Property Investment Right for You?

This route suits company directors who:

  • Own or lease commercial premises already
  • Want long-term control over pension investments
  • Have enough pension value to make property purchase practical
  • Are comfortable taking professional trustee advice

It suits fewer people who need short-term access to their pension fund, since property is an illiquid asset.

Frequently Asked Questions

Can a SSAS buy residential property?

No, not directly. HMRC bans SSAS schemes from holding residential property, and doing so triggers an unauthorised payment charge. There are narrow exceptions, such as staff accommodation tied to a commercial building. SSAS property investment stays restricted to commercial premises, land, and specific mixed-use arrangements approved under HMRC rules.

How much can a SSAS pension borrow?

A SSAS can borrow up to 50% of its net asset value at the date the loan is made. A scheme worth £600,000 can therefore borrow £300,000, giving £900,000 of buying power. This limit gets tested once, not retested if property values fall later.

Is a SSAS a good idea for property investment?

For company directors with sufficient pension value, SSAS property investment can be tax-efficient and flexible. Rent and growth build up tax-free, and trustees control every decision. It suits long-term investors comfortable with an illiquid asset, but it needs proper professional advice before setup.

How does a SSAS pension work?

A limited company establishes the SSAS as a trust for its directors and senior staff. Members typically act as trustees, giving them direct control over investment decisions, including SSAS property purchases, employer loanbacks, and other permitted assets, all within strict HMRC pension rules.

What is the difference between a SSAS and a SIPP?

A SSAS is set up by a company for multiple members, who usually act as trustees and can pool funds together. A SIPP is an individual pension. Only a SSAS can lend money back to its sponsoring company, making it the preferred structure for SSAS property strategies among business owners.

Can a SSAS lend money to a company?

Yes. A SSAS can lend up to 50% of its net asset value back to the sponsoring employer. The loan needs a first legal charge over an asset of equal value, a maximum five-year term, and interest at at least 1% above average bank base rates.

What type of commercial property can a SSAS hold?

A SSAS can hold offices, factories, warehouses, retail units, hotels, pubs, and commercial land, including development sites with the right planning permission. Direct residential property remains prohibited under HMRC’s investment-regulated pension scheme rules, keeping SSAS property investment firmly commercial in scope.

What happens if a SSAS breaks the residential property rules?

Breaching the rules creates an unauthorized payment. HMRC can charge tax of up to 55% on the value involved, alongside a possible scheme sanction charge. This makes professional trustee oversight essential for any SSAS property purchase, especially where a property has mixed commercial and residential use.

SSAS Property Investment: The Complete Guide for UK Company DirectorsBook Your Comprehensive Property Tax Review


Categories
Articles Blogs FAQs Guides

Property Investment Through a Limited Company: The Complete UK Guide

More UK landlords now buy through a limited company than at any point before. Mortgage interest rules changed. Personal tax rates climbed. A company structure started to look far more attractive.

This guide walks through the tax benefits, the real costs, and how to decide if incorporation suits your portfolio.

Why Landlords Choose a Limited Company

A limited company is a separate legal entity. It owns the property, not you personally. Profits get taxed under Corporation Tax rules instead of Income Tax.

For higher-rate taxpayers, this shift matters. Companies pay Corporation Tax at 19% on profits up to £50,000, and 25% on profits over £250,000, with a tapered rate in between. Personal Income Tax on rental profit can reach 45%.

Company ownership also protects your personal assets. Because a limited company is a separate legal entity, any liabilities linked to the property fall on the company, not on you as director or shareholder.

Tax Benefits of Buying Property Through a Limited Company

Three tax advantages drive most incorporation decisions.

  • Lower tax on profits. Corporation Tax rates sit below higher and additional Income Tax bands.
  • Full mortgage interest relief. Companies can still deduct finance costs, including mortgage interest, from rental profits in full, unlike individual landlords.
  • Flexible profit extraction. Profit can stay inside the company until you need it, rather than being taxed the year you earn it personally.

These benefits compound as your portfolio grows, which is why incorporation appeals most to landlords planning to scale.

The Real Costs and Disadvantages

Nothing here comes free. A limited company structure carries extra costs that shrink or eliminate the tax gain for some landlords.

Higher Mortgage Costs

Lenders view limited companies as riskier borrowers than individual homeowners because of their reduced personal liability. Expect fewer lender choices and slightly higher rates.

Administrative Burden

Running a limited company means filing accurate accounting records, annual accounts, tax returns, and sometimes holding formal meetings. Most landlords pay an accountant to manage this.

Stamp Duty on Transfers

Incorporating an existing portfolio triggers Stamp Duty Land Tax, calculated on market value regardless of whether cash actually changes hands.

Transferring an Existing Buy-to-Let Into a Limited Company

Moving property you already own into a company counts as a sale in HMRC’s eyes, even between you and your own business.

TaxWhat Happens on Transfer
Stamp Duty Land TaxCharged on the property’s market value, not the price actually paid, even where no money changes hands
Capital Gains TaxTreated as a disposal at market value, so any gain since purchase can trigger a CGT bill
Incorporation ReliefCan defer both SDLT and CGT, but HMRC generally expects around 20 hours a week of active property management to qualify

Because both taxes hit at once, transferring an existing portfolio needs careful modelling before you commit.

Getting a Mortgage as a Limited Company

Company mortgages, often called SPV (Special Purpose Vehicle) mortgages, work differently to personal buy-to-let loans.

Lenders assess the company’s rental income, your personal guarantee, and your track record as a director. Rates run slightly higher than personal buy-to-let deals, and the lender pool is smaller.

Most brokers recommend setting up a company limited by shares, with a SIC code that clearly states property investment as the business activity.

How to Set Up a Limited Company for Property Investment

  1. Register with Companies House. Choose a name, a registered address, and a property-related SIC code.
  2. Appoint directors and shareholders. One person can hold both roles.
  3. Open a business bank account. Keep company and personal finances fully separate.
  4. Arrange a company mortgage. Speak to a specialist broker who deals with SPV lenders.
  5. Instruct an accountant. Corporation Tax, VAT thresholds, and annual filings need ongoing management.

Is a Limited Company Right for Your Portfolio?

A limited company structure tends to suit:

  • Higher and additional-rate taxpayers
  • Landlords planning to grow beyond one or two properties
  • Investors who plan to reinvest profit rather than draw it out immediately
  • Anyone prioritising limited liability protection

Basic-rate taxpayers with a single investment property often find direct personal ownership simpler and cheaper overall. Portfolio size and your personal tax rate decide which route wins.

Frequently Asked Questions

Is it worth buying property through a limited company?

It depends on your tax rate and portfolio size. Higher-rate taxpayers and landlords planning multiple properties usually benefit most from limited company property investment, thanks to lower Corporation Tax rates and full mortgage interest relief. Basic-rate taxpayers with one property often find personal ownership simpler and cheaper.

What are the tax benefits of buying property through a limited company?

A limited company pays Corporation Tax on rental profit instead of Income Tax, and rates sit lower than higher personal tax bands. Companies also deduct full mortgage interest from profits, and can retain earnings inside the business rather than paying personal tax immediately on every pound earned.

Can I transfer my buy-to-let property into a limited company?

Yes, but HMRC treats the move as a sale at market value. This can trigger Stamp Duty Land Tax and Capital Gains Tax at the same time, even though the same person effectively still owns the asset. Model both costs carefully before transferring an existing limited company portfolio.

Do I pay stamp duty when transferring property to a limited company?

Usually, yes. Stamp Duty Land Tax applies to the property’s market value on transfer, regardless of the price paid or whether cash changes hands at all. Larger portfolios can face substantial SDLT bills, making professional advice essential before any limited company transfer.

How much corporation tax do I pay on rental income?

Companies pay 19% Corporation Tax on profits up to £50,000, rising to 25% on profits above £250,000, with a tapered rate between the two thresholds. This structure often beats personal Income Tax rates for higher earners running limited company property investment.

What are the disadvantages of buying property through a limited company?

Limited companies face higher mortgage rates, a smaller pool of lenders, and ongoing administrative costs like annual accounts and Corporation Tax filings. Stamp duty on transfers and less favourable lending terms can offset tax savings for smaller, lower-rate landlords.

Can I get a mortgage as a limited company?

Yes, through specialist SPV (Special Purpose Vehicle) mortgage products designed for limited company property investment. Lenders assess the company’s projected rental income alongside a personal guarantee from directors. Expect slightly higher rates and fewer lender options than standard personal buy-to-let mortgages.

Do I pay Capital Gains Tax when transferring property into a company?

Generally, yes. HMRC treats the transfer as a disposal at market value, so any increase in the property’s value since purchase can create a Capital Gains Tax bill. Incorporation Relief may defer this for active property businesses meeting strict HMRC conditions.

Property Investment Through a Limited Company: The Complete UK Guide Book Your Comprehensive Property Tax Review