Categories
Articles Blogs FAQs Guides

Stop Letting Messy Bookkeeping Bleed Your Property Profits

Accurate and complete record keeping is the foundation of financial health for any real estate business. When managing rentals, tracking numbers carelessly leads to regulatory non-compliance, missed tax deductions, and stressful tax seasons.

Property investors must manage multiple financial and operational timelines simultaneously. Missing gas safety certificate renewals, insurance end dates, or mortgage fixed-term expirations creates major operational liabilities. Establishing a dedicated property system keeps these moving parts under strict control.

Without a centralized, organized way to track your incoming rent and outbound expenses, calculating true net profitability becomes guesswork.

Three Costly Results of Messy Bookkeeping record keeping

1. Compliance Penalties and Audits

Inadequate record keeping causes errors or omissions on your self-assessment tax returns. If HMRC initiates an inquiry into your property affairs, missing supporting documents can result in substantial fines.

2. Overlooked Expenses and High Tax Bills

Without meticulous documentation, you will overlook allowable deductions like minor maintenance work, insurance, or letting agent fees. Missing an allowable expense artificially inflates your reported net profit, which increases your overall tax bill and reduces your net cash flow.

3. Frozen Decision Making

Vague financial data prevents you from analyzing your real-world portfolio performance. You cannot easily spot properties with high maintenance costs, evaluate current rental yields, or confidently secure financing for your next acquisition.

Risk CategoryImpact of Poor BookkeepingResolution via Automated System
HMRC ComplianceFinancial fines, penalties, and stressful multi-year auditsAutomated digital trails with uploaded receipts
Tax OptimizationMissing allowable expenses, which increases tax liabilityReal-time expense logging categorized by property
Portfolio MetricsBlind decision-making and inaccurate cash flow trackingInstant yield, profit, and loss reporting dashboards

Strategies to Modernize Your Property System

Utilize Dedicated Software

Generic spreadsheets quickly fail as you scale. Cloud accounting tools like Xero or QuickBooks let you link bank feeds directly, log outbound expenses instantly, and export clean reports directly to your accountant. For specialized portfolio management, dedicated property platforms like Lendlord help consolidate tenant records and key certificate dates in one hub.

Consistent Bank Reconciliation

Reconcile your corporate bank accounts, incoming rental slips, and property expenses weekly. Frequent reviews help catch transaction anomalies, banking errors, or late tenant payments before they affect your liquidity.

Keep Every Piece of Documentation

Maintain a secure digital archive of all vendor receipts, contractor invoices, letting agreements, and finance documents. Cloud storage options make it simple to snap photos of receipts immediately, ensuring you always have clear audit trails.

1.Separate Bank Accounts:

Day 1.

Open a dedicated business bank account solely for property transactions to eliminate mixed personal spending.

2.Migrate to Cloud Software:

Day 2 – 5.

Set up a profile on Xero, QuickBooks, or Lendlord and link your dedicated property bank feed.

3.Digitalize Physical Receipts:

Day 6.

Scan your paper receipts using a mobile scanning app and attach them directly to historical transactions.

4.Schedule Reconciliation Reviews:

Monthly.

Block out the first Monday of every month to reconcile every transaction and verify your portfolio yield data.

Stop Bad Record Keeping
Record Keeping

Frequently Asked Questions

What happens if a small business tax has poor record keeping

Submitting inaccurate details on property tax returns triggers formal adjustment notifications from HMRC. You will be required to pay the missing tax alongside calculated interest. Depending on whether your record keeping was careless or intentionally misleading, HMRC levies percentage-based penalties on the underpaid amount. An organized property system avoids these reporting mistakes.

How many years can HMRC investigate?

The formal look-back timeline depends directly on the quality of your record-keeping habits. For basic reporting errors where reasonable care was taken, the limit is four years. If HMRC discovers careless errors or omitted income, the window expands to six years. Deliberate evasion extends the audit window to twenty years.

Can HMRC find me after 20 years?

Yes, modern data matching makes historical tax evasion highly discoverable. The tax authority uses automated software to cross-reference land registry deeds, local council housing records, and mortgage applications against individual tax profiles. Maintaining a transparent property system prevents old omissions from resurfacing as modern legal issues.

What if my rental business made a loss 5 years ago?

Historical losses remain valid for tax optimization but must be officially filed within the statutory four-year window to be carried forward. These documented losses can then be offset against current or future rental profits to lower your taxable income. A robust property system keeps these older calculations organized.

My partner and I aren’t married. How does that affect the tax?

Unmarried joint owners are taxed based on their actual beneficial interest in the property, which matches the legal ownership split on the deed. Unlike married couples, unmarried partners cannot freely shift income splits using an HMRC Form 17. A proper property system tracks individual tax bands to ensure accurate distributions.

Does HMRC really know if I’m renting out my old flat?

Yes, the tax authority accesses deep third-party data pools. They consistently scan tenant deposit scheme registries, local authority licensing logs, and online rental listings. If a property address shifts status without a corresponding section on your self-assessment, automated flags identify the missing rental income.

I only plan to rent it for a year. Do I still need to tell HMRC?

Yes, short rental windows do not exempt you from UK tax regulations. Any gross property earnings above the basic one thousand pound annual property allowance must be declared through self-assessment. Tracking short-term letting details within an explicit property system ensures you stay fully compliant with temporary tenancies.

Can I deduct mortgage interest from my rental income?

No, residential landlords cannot deduct finance costs or mortgage interest directly from rental revenues. Tax relief for finance costs is restricted to a basic twenty percent tax credit applied directly against your final liability. A professional property system tracks this rule to prevent major cash flow surprises for higher-rate taxpayers.

To streamline your portfolio and avoid common compliance mistakes, contact Felix Accountants to design a clean, automated tracking framework.

Record keeping System Guide: Stop Bad Record Keeping Book Your Comprehensive Property Tax Review

Categories
Articles Blogs FAQs Guides News

Trying to do everything yourself

When you start a new property venture, it is tempting to handle every single task yourself. You might be bootstrapping, trying to minimize expenses while navigating initial growth. You handle company registration, website design, tenant screenings, and bookkeeping. However, as your portfolio expands, the operational demands on your time multiply rapidly. Moving from working in your business to working on your business requires a reliable property system to sustain expansion.

Successful property investors view their operations as an entity distinct from their individual identity. They design systematic frameworks that allow their businesses to run smoothly without requiring their constant, hands-on intervention.

Value-Based Time Allocation

Every daily task carries a different notional value. Some operational duties are worth ten pounds an hour, while high-level strategic acquisitions are worth one thousand pounds an hour.

To achieve sustainable scale, you must dedicate your focus to those high-value, thousand-pound activities. This shift means intentionally shifting lower-value administrative tasks to external specialists or trusted software tools.

Task LevelValue Per HourTypical ExamplesOperational Treatment
Low£10 – £20Initial lead entry, social media posting, filing receiptsAutomate or delegate to freelancers
Medium£50 – £100Documenting standard procedures, detailed deal analysisDelegate to specialized team members
High£1000+Strategic joint ventures, capital raising, final acquisition decisionsRetain for principal investor

Core Elements of a Scalable Property System

Delegating tasks before establishing clear processes often leads to costly organizational errors. Before hiring assistants on platforms like Fiverr, Upwork, or People Per Hour, you need to document exactly how you want each operation performed. Clear documentation ensures external support delivers work that matches your personal standards.

1. Documenting Lead Sourcing Procedures

Create an exact checklist detailing how your business sources potential real estate leads. Specify the target geographic areas, maximum purchase thresholds, and acceptable rental yield percentages. When a freelancer understands these parameters, they can filter out irrelevant opportunities, leaving you with highly qualified options.

2. Standardizing Bookkeeping and Compliance

Accurate financial record-keeping keeps your business compliant with regulatory changes. For example, HMRC requires landlords with gross property income exceeding fifty thousand pounds to register for Making Tax Digital (MTD) by April 2026. Having a standardized process for scanning receipts and recording rental income prevents severe penalties.

Important Operational Rule: Always separate your personal and business expenditures completely to avoid accounting complications and potential regulatory scrutiny.

1.Audit Current Time Use:

Week 1.

Track every task you perform for seven days to identify low-value administrative friction points.

2.Draft Standard Operating Procedures:

Week 2.

Write step-by-step instructions for tasks like tenant communications and basic expense tracking.

3.Select Your Outsourcing Platform:

Week 3.

Create accounts on Upwork or specialized virtual assistant platforms to find matching talent.

4.Implement Quality Control Metrics:

Ongoing.

Review the completed work against your documented standards weekly to refine the operational loop.Property System Guide scale Your Portfolio

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture files an inaccurate tax return, HMRC sends a formal notification outlining the financial discrepancy. You will face standard interest charges on the unpaid balance, along with potential penalties calculated based on whether the error was accidental or deliberate. Implementing a secure property system minimizes these financial risks.

How many years can HMRC investigate?

The look-back period depends directly on landlord behavior. If you took reasonable care, HMRC looks back four years. For careless bookkeeping, the window expands to six years. Deliberate tax evasion or failure to notify allows an investigation going back twenty years.

Can HMRC find me after 20 years?

Yes, modern digital tracking makes discovery highly likely. The HMRC Connect system automatically cross-references Land Registry records, bank accounts, and council tax databases to expose undeclared rental streams. Relying on professional property system accounting ensures you do not trigger automated audits.

What if my rental business made a loss 5 years ago?

Legitimate historical property losses fall within the standard investigation window but do not create immediate tax liabilities. You can actively carry forward these documented losses to offset your future rental profits. Keeping your documentation updated via an organized property system protects these valuable deductions.

My partner and I aren’t married. How does that affect the tax?

If the property title belongs strictly to one individual, that person is liable for one hundred percent of the rental income tax. Jointly owned properties typically split the incoming tax obligations fifty-fifty. A structured property system maps these ownership structures to maintain precise tax compliance.

Does HMRC really know if I’m renting out my old flat?

Yes, automated data matching leaves clear digital trails. HMRC regularly tracks changing voter registries, tenancy deposit protection data, and mortgage classifications. An unannounced change in your address often triggers an automated warning letter if no rental income appears on your self-assessment.

I only plan to rent it for a year. Do I still need to tell HMRC?

Yes, all short-term rental income above the one thousand pound annual property allowance must be formally declared. Failing to notify the tax authority because of a short rental timeline still results in automated penalties. Consistent execution through a solid property system avoids these simple compliance oversights.

Can I deduct mortgage interest from my rental income?

Individual residential landlords cannot deduct mortgage interest payments directly from their rental earnings. The old deduction system has been replaced with a fixed twenty percent tax credit. Integrating your portfolio with a professional property system helps track how this restriction impacts higher-rate taxpayers.

If you want to free up your schedule and reduce administrative friction, visit Felix Accountants to establish a compliant framework for your growing business.

Trying to do everything yourselfBook Your Comprehensive Property Tax Review
Categories
Articles Blogs Guides

Landlord Tax Expenses: The Complete UK Property Deduction Guide

Not claiming all the expenses, you can.

Landlords often pay more tax than necessary because they fail to claim legitimate business expenses. UK tax legislation changes frequently, but the core principle remains consistent: you can deduct costs that are incurred wholly and exclusively for your property business. Reducing your taxable profit directly lowers your final tax bill.

Thorough record-keeping ensures you do not leave money on the table. When you track every transaction, you protect your profit margins and maintain tax compliance.

What Counts as a Allowable Property Expense?

HM Revenue and Customs (HMRC) allows you to deduct revenue expenses from your rental income. A revenue expense is money spent on the day-to-day running of the property. This differs from capital expenditures, which involve improving the property or purchasing assets.

Maintenance and Repairs

You can deduct the cost of updates that restore the property to its original condition. Payments to contractors for fixing leaks, treating damp, or repairing broken windows qualify fully. However, replacing a standard laminate countertop with premium granite counts as an improvement, which is a capital expense rather than a revenue deduction.

Professional and Administrative Fees

Running a rental business involves administrative overheads. You can deduct letting agent management fees, legal fees for renewing tenancies, and professional fees paid to accountants. Subscriptions to property management software, professional insurance policies, and specialized industry magazines are also fully allowable.

Travel and Communication

Travel undertaken solely for property business purposes is deductible. This includes visiting the property for inspections or meeting contractors. You can claim flat-rate mileage allowances rather than tracking actual fuel costs, which is often more efficient.

Phone calls made specifically to resolve tenant emergencies or manage bookings are also valid deductions. If you use a single phone line for personal and business use, you must look at your itemized bills to separate and claim only the business portion.

Smart Landlord Tax Deductions You Might Miss

Many property owners overlook specific home-office and travel deductions because standard guidance rarely highlights them.

Business Mileage Rates

You can claim 45p per mile for the first 10,000 miles driven in a tax year for business trips using your personal car. This rate drops to 25p per mile after that threshold. This reimbursement can be paid from a business bank account to yourself tax-free, lowering your overall property profits.

Use of Home as an Office

If you manage your portfolio from a dedicated workspace at home, you can claim a proportion of your household bills. You can calculate actual costs based on the number of rooms used and time spent, or use HMRC simplified flat-rate expenses for business use of home. This reduces your taxable income by recognizing that administrative work happens outside the rental property itself.

Non-Allowable Expenses and Dual Purpose Pitfalls

HMRC strictly rejects expenses that serve a dual purpose. For an expense to be deductible, it cannot have a hidden personal benefit.

  • Clothing: You cannot claim for ordinary clothes or business suits worn to meet tenants, as these items serve a everyday personal function. Only specialized safety gear or branded uniforms qualify.
  • Food and Drink: Meals consumed during normal working days are private expenses. You cannot deduct the cost of your lunch while visiting a local property.
  • Private Travel: Trips that combine a property inspection with a family holiday cannot be claimed. If you cannot separate the business travel from the personal journey, the entire expense becomes non-allowable.

    Property Expenses
    Expense

Frequently Asked Questions

What expenses can I claim as a landlord UK?

Landlords can claim revenue expenses incurred wholly and exclusively for managing properties. These include letting agent fees, accountant costs, property repairs, insurance, and specific travel expenses. Capital improvements do not qualify for immediate revenue deduction.

Can I claim travel expenses as a landlord?

You can claim travel expenses if the journey is solely for property management purposes. Landlords usually use the standard HMRC mileage rate of 45p per mile to calculate these costs. Personal trips or mixed-purpose journeys are strictly excluded.

Are legal fees tax deductible for rental property?

Legal fees for subletting, renewing a tenancy agreement for less than fifty years, or evicting tenants are deductible. However, legal costs associated with buying or altering properties are capital expenses and cannot reduce your ongoing rental income tax.

Can I claim internet as a rental expense?

You can claim a proportion of your internet costs if you use your home connection to manage your property portfolio. You must calculate the business use percentage accurately, as HMRC does not allow deductions for the personal portion of dual-purpose utilities.

How do property expenses reduce my tax bill?

Deducting legitimate property expenses reduces the net profit figure that you report to HMRC. Since your income tax is calculated solely on net profit rather than gross revenue, maximizing your allowable claims directly lowers your total tax liability.

Landlord Tax Expenses: The Complete UK Property Deduction Guide Book Your Comprehensive Property Tax Review


Categories
Blogs FAQs Guides

Let Property Campaign Disclosure Process: A Practical Guide

The Let Property Campaign (LPC) provides residential landlords with a route to bring their UK tax affairs up to date by disclosing previously undeclared rental income to HM Revenue & Customs (HMRC).

HMRC introduced the campaign in 2013 to encourage landlords to correct their tax affairs voluntarily. It may be relevant if you have received an HMRC nudge letter or discovered that you have not reported rental income correctly.

Making a complete disclosure can help you establish the correct tax liability and may reduce penalties, depending on the circumstances. The amount payable will depend on the tax years involved, your rental profits, the nature of the error and whether your disclosure is prompted or unprompted.

Understanding the Let Property Campaign disclosure process before you begin can help you prepare the necessary records, meet HMRC’s deadline and avoid common mistakes.

Let Property Campaign Disclosure Process: Overview

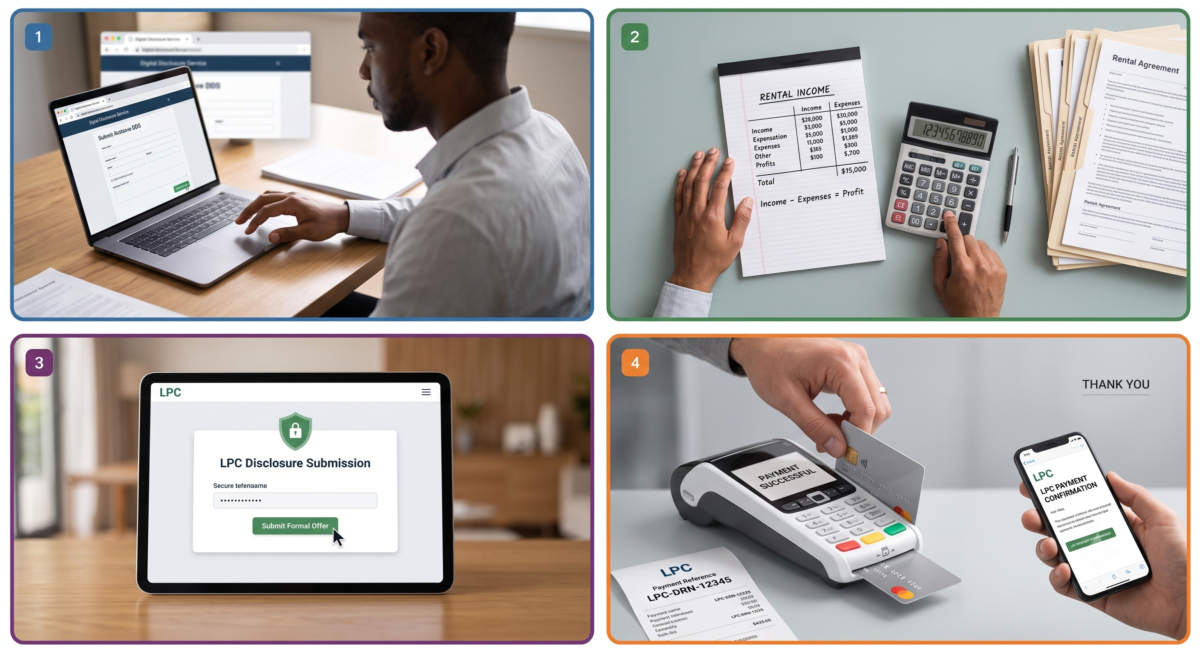
StepActionKey tasks and outputs
1. Notify HMRCSubmit the Digital Disclosure Service (DDS) notificationHMRC issues a disclosure reference number and payment reference number after notification.
2. Calculate tax and penaltiesCalculate rental profits and outstanding liabilitiesEstablish the tax, interest and any applicable penalties for the relevant years within the 90-day window.
3. Submit formal disclosureSend the completed disclosure and formal offer to HMRCHMRC reviews the submission and may ask for more details.
4. Settle the liabilityPay the amount due or discuss payment difficulties with HMRC beforehandPay by HMRC’s deadline or discuss payment difficulties with HMRC beforehand.

What Is the Difference Between Notifying HMRC and Making the Disclosure?

Notification is the first stage. You tell HMRC that you intend to put right unpaid tax from residential letting, but you do not have to provide all the rental figures at that point.

HMRC then issues reference numbers and a notification acknowledgement. The disclosure is the later stage, when you calculate the relevant income, expenses, tax, interest and any penalties and present the full explanation.

You must check the deadline on the acknowledgement. HMRC’s Let Property Campaign guidance says the disclosure must be made within 90 days of the date you receive that acknowledgement, and it explains what to do if the amount cannot be paid in full.

Keep the acknowledgement with your records and note its date. If you have several properties or years to correct, prepare one clear schedule for each year. The aim is a complete, consistent explanation that HMRC can review.

Eligibility for Let Property Campaign Disclosure

The Let Property Campaign covers individuals with undeclared income from residential property. You may be eligible if you have received rental income that was not correctly reported to HMRC.

Examples include:

  • Renting out a room in your main home where the Rent a Room relief conditions or limits have not been correctly applied.
  • Renting out one or multiple residential properties.
  • Living abroad while renting out UK residential property.
  • Living in the UK while renting out residential property overseas, where the relevant UK tax rules apply.
  • Receiving income from a holiday home that you rent out, even if you also use the property personally.

Eligibility depends on your circumstances and the type of property and income involved.

Can My Spouse and I Make One Joint Rental Income Disclosure?

HMRC says that a single Let Property Campaign disclosure cannot include more than one person. If spouses or other co-owners each have undeclared rental income, they need separate notifications and disclosures for their respective shares.

Before completing either form, compare the tenancy agreements and ownership records with the amounts shown in any previous tax returns. Agree a consistent schedule of gross rent, relevant costs and the tax years involved, then check how the income should be attributed to each person.

Do not simply assume that all jointly held properties must be reported in the same way without reviewing the facts. If one owner has already reported their share, that does not remove the need to review the other owner’s position.

Felix & Co. can help both owners prepare a clear record of what each person needs to disclose.

Exceptions

The Let Property Campaign is intended for residential landlords and does not cover every type of property or taxpayer.

It is generally not the appropriate route for:

  • Commercial property income, such as income from shops, commercial garages or storage units.
  • Rental income belonging to companies or other entities rather than an individual landlord.

Trusts and other ownership arrangements can require specific consideration. Check the current HMRC guidance to establish the correct disclosure route for your circumstances.

HMRC Nudge Letters

HMRC uses information from a range of sources to identify potential discrepancies between property ownership, rental activity and reported income. These sources may include property records and information supplied by third parties.

If HMRC identifies a possible discrepancy, it may send a letter asking you to review your tax position.

If you receive a nudge letter, read it carefully and note any response deadline. Check which tax years and properties it refers to, gather the relevant records and establish whether your previous tax returns were complete.

Do not assume that every letter has the same legal status or that receiving one automatically prevents you from making a disclosure through the campaign. Your options depend on the nature of HMRC’s contact and whether a formal enquiry or compliance check has begun.

For more information, read our guide to prompted versus unprompted disclosure.

How to Start a Let Property Campaign Disclosure

Following the correct steps helps you prepare an accurate disclosure and respond to HMRC’s requirements.

Step 1: Notify HMRC

Start by informing HMRC of your intention to disclose previously undeclared rental income. Submit your notification through the official Digital Disclosure Service (DDS) on GOV.UK.

If you are reporting income on behalf of someone who has died, make it clear that you are acting for the estate and follow HMRC’s instructions for that situation.

At this stage, you are notifying HMRC of your intention to disclose. You do not need to complete the full rental income calculation as part of the initial notification.

HMRC will issue a disclosure reference number and payment reference number. Keep these details safe and use the relevant reference when communicating with HMRC or making payments.

Information to Prepare

Personal details: When notifying HMRC, provide the information requested by the current HMRC notification service. At this stage you are notifying your intention to disclose; detailed rental figures are prepared for the later disclosure.

Property details: Prepare the addresses, years let, ownership shares, rent received and relevant records for the calculation stage. HMRC may ask for further details during the disclosure process.

You should also begin collecting tenancy agreements, rental statements, expense receipts, previous tax returns and correspondence with HMRC.

Step 2: Calculate the Tax Owed

After receiving your notification acknowledgement, you generally have 90 days to prepare and submit your formal disclosure. Check the exact deadline stated in HMRC’s acknowledgement and guidance.

For each relevant tax year, calculate your total rental income and deduct the allowable expenses for that year.

Depending on your circumstances, allowable expenses may include:

  • Letting agent fees.
  • Repairs and maintenance.
  • Property insurance.
  • Relevant safety certificates and compliance costs.
  • Other qualifying costs incurred wholly and exclusively for the rental business.

The rules for expenses, finance costs, property allowances and reliefs can vary according to the tax year and the nature of your letting activity. Do not automatically deduct every payment connected with a property.

Calculate the taxable rental profit using the rules applicable to each year. Then establish the tax due, taking account of your other income, relevant allowances, reliefs and the tax rates applicable to that period.

Do not include income that has already been correctly declared, except where a correction to the original figures is required.

You should also calculate any interest and applicable penalties. These depend on the facts of your case, including the tax years involved, the type of error and your behaviour.

Preparing clear supporting calculations for each year makes it easier to explain the figures if HMRC requests further information.

For help preparing the documents for your rental disclosure, ensure that your records are complete and consistent before submitting your figures.

Step 3: Submit the Formal Disclosure

Once you have completed your calculations, prepare the formal disclosure using HMRC’s prescribed process.

Your disclosure should explain the rental income that was omitted, the relevant tax years, the calculations supporting your figures and the circumstances that led to the original error.

Include the tax, interest and applicable penalties in accordance with HMRC’s requirements, and make the appropriate formal offer.

A formal disclosure does not mean HMRC has automatically accepted your calculations. HMRC will review the information and may ask you or your adviser to provide clarification or additional evidence.

Ensure that the figures agree with your supporting records and that any estimates are clearly explained.

Step 4: Arrange Payment

You must deal with the outstanding liability in line with HMRC’s deadline and payment instructions.

Use the payment reference number provided by HMRC when making the payment. Check the amount and reference carefully to help ensure that your payment is allocated correctly.

If you cannot pay the full amount immediately, contact HMRC as early as possible to discuss whether a Time to Pay arrangement is available. Explain your financial circumstances and provide any information HMRC requests.

Do not assume that requesting an instalment arrangement automatically changes your disclosure deadline or payment obligations. Confirm the arrangements and any relevant deadlines directly with HMRC.

What Happens After HMRC Receives My Disclosure?

HMRC reviews the disclosure and may ask you or your adviser to explain amounts, estimates or the reason for the original omission.

Its published guidance says that, where HMRC is satisfied that a full disclosure has been made, it will write to accept the offer. This is not a promise of immediate acceptance or an agreed processing time for every case.

Keep the submitted calculation, proof of payment and correspondence in a secure folder. If HMRC asks questions, answer accurately and provide the relevant working papers rather than changing figures without explanation.

Once the earlier years have been dealt with, check what needs reporting through the normal tax return process in future. If HMRC has contacted you already, the correspondence should also be reviewed when deciding how the disclosure should be described.

Ask Felix & Co. to review the documents if you need help responding.

Penalties Under the Let Property Campaign

HMRC may charge penalties when rental income has not been correctly reported or a taxpayer has failed to notify HMRC of a tax liability.

The penalty depends on the applicable legislation, the tax year, the type of failure and the circumstances. HMRC considers factors such as whether the error was careless or deliberate, whether information was concealed and whether the disclosure was prompted by HMRC.

A voluntary disclosure may help reduce the penalty where the relevant conditions are met, but it does not guarantee a particular reduction or eliminate the underlying tax and interest.

How Cooperation Can Affect Penalties

When determining the reduction available for certain penalties, HMRC may consider the quality of your disclosure and your cooperation.

  • Telling: Explain clearly what was wrong and provide a complete account of the missing income.
  • Helping: Answer questions and cooperate with HMRC in checking the relevant figures.
  • Giving access to records: Respond to HMRC’s requests for relevant information and supporting evidence.

The applicable penalty rules and reduction calculations should be checked against the legislation and HMRC guidance relevant to your case.

Penalties for Failure to Notify

A failure-to-notify penalty may apply if you did not tell HMRC about a tax liability when required to do so.

The potential penalty depends on the relevant tax regime, when notification was required, the nature of the behaviour and whether the disclosure was prompted or unprompted.

Non-deliberate failure to notify, timing and penalty position should be checked against the relevant legislation and year.

Other categories, including deliberate and deliberate-and-concealed behaviour, also require a case-specific assessment. Do not rely on a single percentage range without confirming that it applies to the particular tax year and circumstances.

Penalties for Inaccurate Tax Returns

Different rules may apply if you submitted Self Assessment tax returns but omitted rental income or entered incorrect figures.

The outcome depends on whether you took reasonable care, made a careless error or deliberately submitted an inaccurate return. The distinction matters because the applicable penalty rules and potential reductions can differ.

If you discover an error in a previously submitted return, establish which years are affected and whether HMRC has already contacted you. Then determine the appropriate correction and disclosure route.

For a more detailed explanation, read our guide to Let Property Campaign penalties.

What If HMRC Has Already Written to Me About Undeclared Rent?

You may still need to correct the tax position after HMRC contacts you, but you should not assume the disclosure is unprompted.

HMRC looks at the circumstances, including what you had reason to believe it had already discovered. Read the letter carefully and keep its date, any attached certificate and the stated response deadline.

Check what information HMRC is asking for, and do not send a guess simply to meet the date. Compare the years mentioned with your rental records and decide whether you need advice before responding.

Penalty treatment depends on the type of error, the facts and the quality of the disclosure, so a fixed percentage should not be promised.

A complete explanation is still worthwhile even where HMRC has made contact. Felix & Co. can help you work through the letter and supporting records.

Frequently Asked Questions

How does HMRC find out about undeclared rental income?

HMRC can compare information from different sources to identify potential discrepancies between property ownership, rental activity and declared income. Information from property records and third parties may contribute to compliance checks.

A discrepancy does not automatically establish that tax is owed, but it may lead HMRC to request further information or investigate the circumstances.

How far back can HMRC look into undeclared rental income?

The period HMRC can assess depends on the relevant tax legislation, the type of error and the circumstances.

Different time limits may apply where reasonable care was taken, where a loss of tax arose through careless behaviour, or where the loss was deliberate. Longer periods can apply in certain cases involving deliberate behaviour.

Do not assume a single look-back period applies to every Let Property Campaign disclosure. Review the relevant years with reference to the rules applicable to your case.

What happens if I ignore an HMRC nudge letter?

Ignoring HMRC correspondence can make it harder to resolve a potential tax discrepancy and may increase the risk of further compliance action.

Read the letter, establish what HMRC is asking for and respond by the stated deadline where required. If you are unsure how to proceed, seek professional advice before sending an incomplete or inaccurate response.

Does an LPC disclosure need to include other income sources?

The disclosure should follow HMRC’s requirements and cover the liabilities that need to be corrected. If you have other previously undeclared income or gains, you should establish whether these need to be reported through the same or a different disclosure route.

Do not assume that every type of income can automatically be included in a Let Property Campaign disclosure. Check the relevant HMRC guidance for the particular income and circumstances.

Can I pay my tax liability in instalments?

You may be able to arrange a Time to Pay agreement with HMRC if you cannot afford to pay the full liability immediately.

Contact HMRC as early as possible, explain your circumstances and confirm what arrangements are available. Do not assume that an instalment request automatically extends your disclosure deadline or changes your obligations.

Can I use the Let Property Campaign if HMRC has already started investigating me?

You should not assume that the campaign remains available if HMRC has already opened a formal enquiry or compliance check.

The correct route depends on the nature and stage of HMRC’s contact. Review the correspondence and obtain advice if necessary before deciding how to disclose the outstanding liability.

Even where the campaign is not available, correcting the position and cooperating with HMRC may remain important when the applicable penalty rules are considered.

What should I do if I am unsure how to calculate my rental profits?

Start by gathering rental statements, tenancy agreements, expense records, ownership documents and previous tax returns. Organise the information by property and tax year.

Check which costs are allowable, how any property finance costs should be treated and how the rental income should be attributed between co-owners. Professional advice can help identify errors before the disclosure is submitted.

Get Help With Your Let Property Campaign Disclosure

Correcting undeclared rental income can involve several tax years, detailed calculations and decisions about interest, penalties and payment arrangements.

The right approach depends on your rental history, ownership structure, previous tax returns and any correspondence you have received from HMRC.

Felix & Co. can help you review your rental tax position, organise the supporting records and understand the steps involved in making an accurate disclosure.

Ask Felix & Co. to review your rental tax position before submitting your disclosure.
LPC Disclosure Guide: Step-by-Step HMRC Process  Book Your Comprehensive Property Tax Review
Categories
Articles Blogs FAQs Guides News

The Best Expert Guide to UK Landlord Tax Deductions in 2026

Understanding UK landlord tax deductions 2026

You must understand UK landlord tax deductions to make the most profit from your rental property. It also helps you avoid paying more tax than necessary in 2026. Therefore, knowing what costs you can legally claim keeps you compliant with HMRC while improving your property tax efficiency.

What are allowable UK landlord tax deductions?

UK property tax efficiency

A cost must be wholly and exclusively for your rental property business to qualify as an allowable expense. These deductions reduce your taxable rental profit and can help landlords manage their tax responsibilities more effectively.

Common UK landlord tax deductions include property safety checks such as gas certificates, EICRs, and fire alarm inspections. Landlords can also claim property management costs, including letting agent fees, tenant referencing, inventory checks, and advertising costs.

Additionally, professional costs such as accounting services and certain legal fees may be deductible. Insurance costs, including landlord insurance, buildings insurance, and liability cover, can also qualify. Travel expenses related to managing the rental property, repairs, or inspections may be allowed if they meet HMRC rules.

Repairs vs Improvements: UK landlord tax deductions

Understanding the difference between repairs and improvements is important because they receive different tax treatment.

Repairs restore a property to its original condition and are normally deductible. Examples include repairing a leaking roof, fixing broken windows, replacing damaged flooring, or repairing an existing boiler.

However, improvements add value or upgrade the property beyond its original state. Examples include building an extension, adding a loft conversion, or installing a luxury kitchen. These costs are usually not deducted from rental income, but keeping records is important because they may help reduce your Capital Gains Tax when selling the property.

How to document expenses for HMRC

HMRC compliance

Keeping accurate records is essential for every landlord. Digital record keeping makes it easier to track expenses and prepare your tax return.

Landlords should keep invoices, receipts, bank statements, and digital copies of expenses. Using accounting software or a receipt management app can prevent missing important deductions. Separating rental income and expenses through a dedicated bank account can also make tax reporting easier.

Good record keeping also helps landlords prepare for changes such as Making Tax Digital (MTD) requirements and ensures evidence is available if HMRC requests supporting documents.

Common grey area deductions

Some landlord expenses are not always straightforward. Many landlords ask whether they can claim administrative costs, home office expenses, or professional membership fees.

Some costs may qualify if they are directly connected to running the rental property business. For example, certain legal costs, property management expenses, and professional advice fees may be allowable. Always check that expenses meet HMRC requirements before claiming them.

Frequently Asked Questions About UK Landlord Tax Deductions 2026

1. What tax deductions can UK landlords claim in 2026?

UK landlords can claim allowable expenses that are directly related to renting out their property. These may include repairs, insurance, letting agent fees, property management costs, accountant fees, safety certificates, and other necessary rental business expenses.

2. Can landlords claim mortgage payments as a tax deduction?

No. Individual landlords cannot normally deduct the full mortgage payment from rental income. However, mortgage interest may qualify for tax relief through the finance cost restriction rules.

3. Are property repairs tax deductible for landlords?

Yes. Repairs that maintain the property and return it to its original condition are usually allowable deductions. Examples include fixing leaks, repairing damage, replacing broken parts, and maintaining existing facilities.

4. What is the difference between repairs and improvements?

Repairs maintain the existing property, while improvements add value or create something new. Repairs are usually deducted from rental income, but improvements are generally treated as capital expenses and may only provide relief when calculating Capital Gains Tax.

5. Can landlords claim letting agent fees?

Yes. Fees paid to letting agents for finding tenants, managing properties, collecting rent, or carrying out tenant checks are normally allowable UK landlord tax deductions.

6. Can landlords claim insurance costs?

Yes. Landlord insurance, buildings insurance, and certain liability insurance costs connected with renting out a property can usually be claimed as allowable expenses.

7. Do landlords need receipts for tax deductions?

Yes. Landlords should keep receipts, invoices, bank statements, and digital records for all claimed expenses. Proper documentation helps support your claims if HMRC requests evidence.

8. Can landlords claim expenses when a property is empty?

Some expenses during an empty period may still qualify if they are necessary for preparing or maintaining the property for rental. The expense must still meet HMRC’s rules for allowable deductions.

9. Can landlords claim accountant fees?

Yes. Professional fees for preparing tax returns, managing rental accounts, and receiving property tax advice can usually be claimed as allowable expenses.

10. How can landlords reduce tax legally in the UK?

Landlords can reduce tax legally by claiming all eligible expenses, keeping accurate records, understanding available tax reliefs, and getting professional advice to structure their property investments efficiently.

Need Help With Your UK Landlord Tax?

Managing rental property taxes can be complicated. Missing allowable deductions could mean paying more tax than necessary. Contact Felix & Co. Accountants for professional property tax advice and support with your 2026 tax return.

Understanding UK landlord tax deductions 2026 helps property owners maximise their rental profits while staying compliant with HMRC rules. From repairs and insurance to professional fees and property management costs, claiming the correct expenses can significantly reduce your taxable rental income.

Landlords should keep detailed records, understand the difference between repairs and improvements, and seek professional advice when unsure. With proper tax planning, landlords can make better financial decisions and manage their property investments more effectively.

Understanding UK landlord tax deductions 2026  Book Your Comprehensive Property Tax Review

Categories
Articles FAQs Guides

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Small businesses can write off the entire purchase price of qualifying equipment, software, and vehicles in the exact tax year they put those assets to work. This Section 179 tax code provision represents a significant opportunity to save cash and lower business overhead. Instead of writing off a fraction of a computer or truck purchase over a five-year recovery schedule, you can deduct the full amount immediately.

The rules shifted favorably recently. Thanks to the One Big Beautiful Bill Act (OBBBA), the deduction ceiling grew substantially. For the 2026 tax year, you can claim up to $2,560,000 in immediate write-offs.

Section 179 tax Deduction Basics

Most business assets lose value over time. Usually, you must spread your deduction for that loss over several years. Section 179 changes this standard system. It lets you accelerate the write-off process by claiming the entire depreciation expense in year one.

To use this tax break, you must meet key timing requirements. You must buy or lease the asset and place it into service by midnight on December 31 of the tax year. “Placed in service” means the equipment is fully functional and ready for its intended business use. Merely purchasing the item or leaving it in its box does not count.

The deduction is subject to a dollar-for-dollar phase-out. For 2026, the spending threshold begins at $4,090,000.If your company spends more than that on qualifying business property, your maximum allowed deduction decreases by the excess amount. Once your capital equipment spending hits $6,650,000, your deduction drops to zero.

How to Calculate Your Section 179 tax Write-Off

Calculating your savings requires three numbers. You need your total equipment purchase cost, your business use percentage, and your tax rate.

If you use an asset for both personal and business purposes, you must prorate the deduction. The asset must serve your business more than 50% of the time to qualify at all. For example, suppose you purchase a $10,000 heavy-duty printer. You use it 80% for client work and 20% for personal printing. Your qualifying cost basis becomes $8,000.

Here is a straightforward calculation for a business using 100% business-use equipment:

Calculation StepExample Values
Total Equipment Cost$150,000
Section 179 Deduction$150,000
Estimated Tax Rate35%
Direct Tax Cash Savings$52,500
Net Cost of Equipment$97,500

If your total purchases exceed the $4,090,000 threshold, apply this formula:

Deduction Limit=$2,560,000−(Total Purchases−$4,090,000)

For example, if you buy $4,500,000 in equipment, your excess spending is $410,000. Your modified deduction ceiling drops to $2,150,000.

Section Section 179 tax

Qualifying Property Under Section 179 tax Rules

The IRS limits this deduction to specific asset types. Most tangible personal property used in your business qualifies.

The primary categories include:

  • Office furniture like desks, chairs, and conference tables.
  • Computers, servers, laptops, and networking hardware.
  • Off-the-shelf software available to the general public with a non-exclusive license.
  • Manufacturing machinery, printing presses, and specialized tools.
  • Qualified Improvement Property (QIP) including interior renovations to commercial buildings.
  • Building security systems, fire alarms, HVAC units, and commercial roofing.

Both new and used equipment qualify for the write-off. The used equipment must be new to your business. You cannot purchase used gear from a related family member or business entity to claim the write-off.

Vehicle Rules and Weight Limits

Vehicles face stricter standards due to historical abuse of the tax code. The IRS categorizes vehicles by Gross Vehicle Weight Rating (GVWR). You can find this rating on the manufacturer label inside the driver side door jamb.

Passenger cars and light trucks under 6,000 lbs GVWR have a low caps limit. For 2026, these light vehicles are subject to a maximum first-year depreciation limit of $20,300.

Heavy SUVs, pickup trucks, and cargo vans with a GVWR between 6,001 and 14,000 lbs qualify for a higher threshold. In 2026, the maximum Section 179 deduction for these heavy SUVs is capped at $32,000.Large commercial vehicles exceeding 14,000 lbs GVWR escape passenger limits entirely. Delivery trucks, box trucks, buses, and heavy construction equipment qualify for the full Section 179 write-off up to the $2,560,000 cap.

Section 179 tax vs Bonus Depreciation

Bonus depreciation is another accelerated tax incentive, but it operates under different rules. Under the current 2026 rules, 100% bonus depreciation is available for qualified property.

Unlike Section 179, bonus depreciation does not cap your total deduction amount. It does not decrease based on your total capital purchases during the year.

Another major difference involves business income. You cannot use Section 179 to create a net business loss. Your Section 179 deduction is limited to your net taxable business income. Bonus depreciation has no such limit. You can use it to create or increase a Net Operating Loss (NOL), which you can carry forward to offset future profits.

The standard approach is to apply Section 179 first to maximize deductions on specific assets. You then apply 100% bonus depreciation to any remaining asset basis.

How to Claim the Deduction on Your Taxes

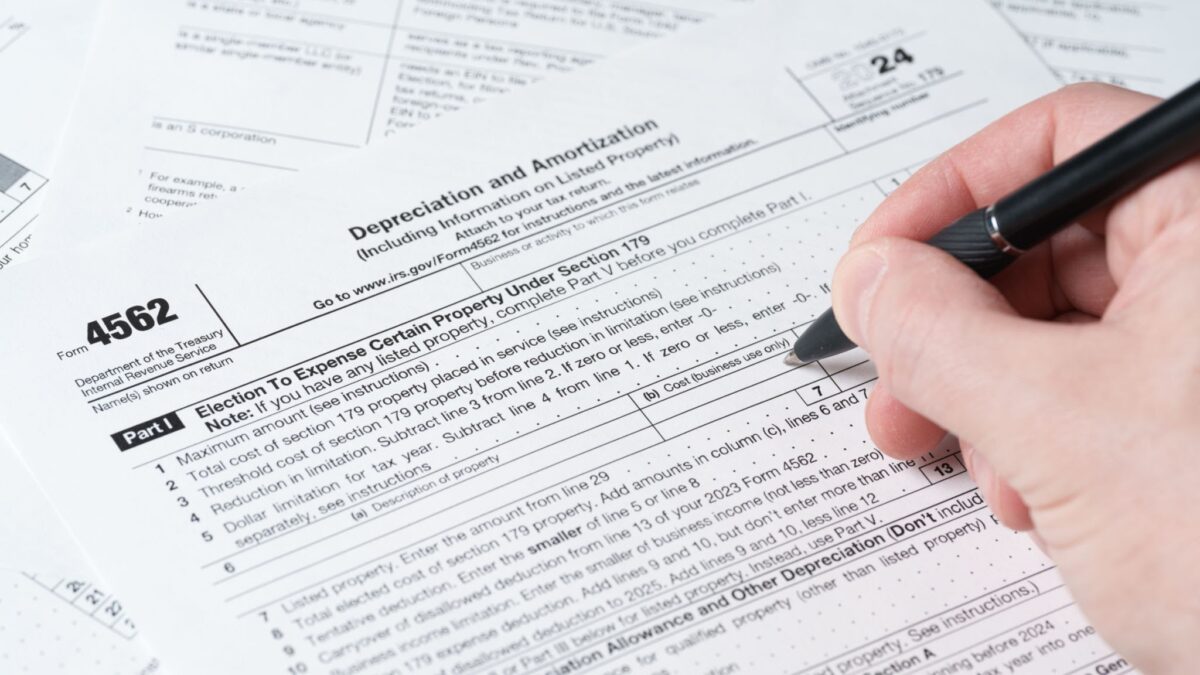
To claim this tax break, you must file IRS Form 4562 with your annual tax return. You will list the qualifying assets, their total cost, and the specific deduction amount you elect to expense.

Keep meticulous records for each purchase. Save the original invoices, receipts, and purchase contracts. Document the exact date you placed the equipment in service. If the asset has split business and personal use, maintain a log to prove your business use percentage exceeds the 50% threshold.

Section Section 179 tax

Frequently Asked Questions

Who qualifies for Section 179 tax?

All active businesses that purchase, finance, or lease qualifying new or used equipment during the tax year qualify for this write-off. You must use the acquired property for business operations more than 50% of the time to lock in your eligibility. Meeting these criteria lets you claim the Section 179 tax deduction to lower your tax liability.

What are the Section 179 limits for 2026?

For the 2026 tax year, the maximum Section 179 tax deduction limit is $2,560,000. This limit begins to phase out dollar-for-dollar when your total qualifying equipment purchases exceed $4,090,000. Once your annual equipment spending reaches $6,650,000, the deduction is completely unavailable.

Can used equipment qualify for Section 179?

Yes, used equipment qualifies for the write-off as long as it is new to your business. You cannot buy the used assets from a related business or family member. The Section 179 tax provisions treat qualifying used machinery, furniture, and tools exactly like brand-new hardware.

What is the difference between Section 179 and bonus depreciation?

The Section 179 tax deduction cannot exceed your active business taxable income, meaning it cannot create a net loss. It is capped at $2,560,000. Conversely, 100% bonus depreciation is uncapped and can create a net operating loss to offset taxes in other years.

Does a vehicle qualify for Section 179?

Yes, vehicles qualify for this write-off, but the IRS applies strict weight limits. Light passenger cars under 6,000 lbs have low caps. Heavy work trucks, cargo vans, and specialized passenger vehicles over 6,000 lbs GVWR are eligible to receive the full Section 179 tax write-off.

How do you calculate a Section 179 deduction?

Multiply the total cost of your qualified equipment by your business-use percentage to find your depreciable basis. If your total annual spending is under $4,090,000, you can write off the entire basis up to $2,560,000 using the Section 179 tax code.

What is the maximum Section 179 deduction for an SUV?

For heavy passenger SUVs with a GVWR between 6,001 and 14,000 lbs, the maximum first-year Section 179 tax write-off is limited to $32,000 in 2026. You can depreciate any remaining value using bonus or standard MACRS schedules.

Can Section Section 179 tax create a net operating loss?

No, the Section 179 tax deduction cannot exceed your net business taxable income. If your business operates at a loss before the deduction, you cannot claim it to create a net operating loss. Any disallowed portion carries forward to the next tax year.

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Book Your Comprehensive Property Tax Review

Categories
Articles Blogs Guides

Mistakes Landlords Make That Can Land Them on HMRC’s Watchlist

Finding your business placed on an HMRC watchlist is a serious financial emergency. When His Majesty’s Revenue and Customs targets you, your routine operations face severe disruption. The tax authority monitors your transactions, visits your premises, and audits your filings with intense scrutiny.

If you suspect you are under investigation, you must act quickly. Ignoring the warning signs only increases your exposure to back taxes, interest, and criminal prosecution.

Understanding the HMRC Watchlist Programs

The tax authority uses two primary monitoring systems to track high-risk taxpayers. While many people refer to these collectively as a watchlist, they operate under different legal frameworks.

The Managing Serious Defaulters Programme

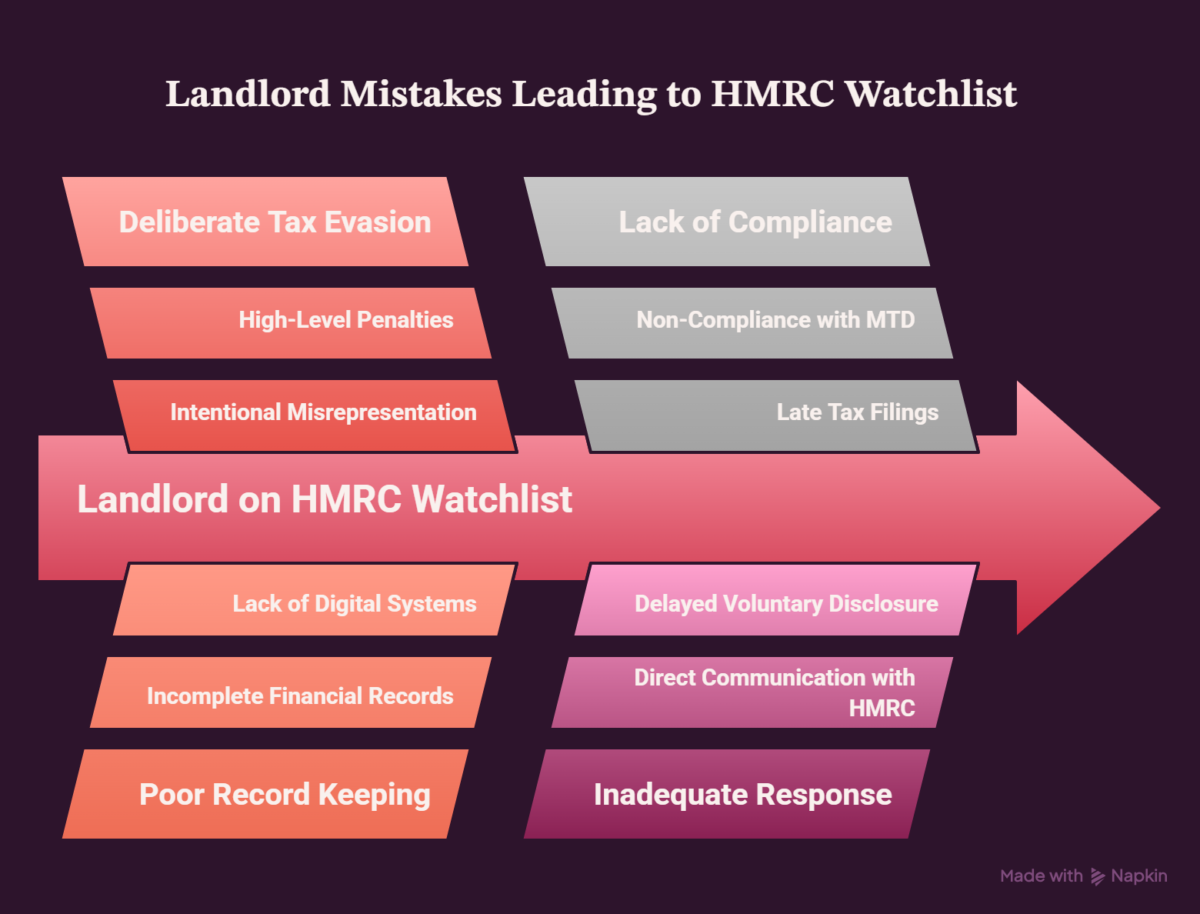
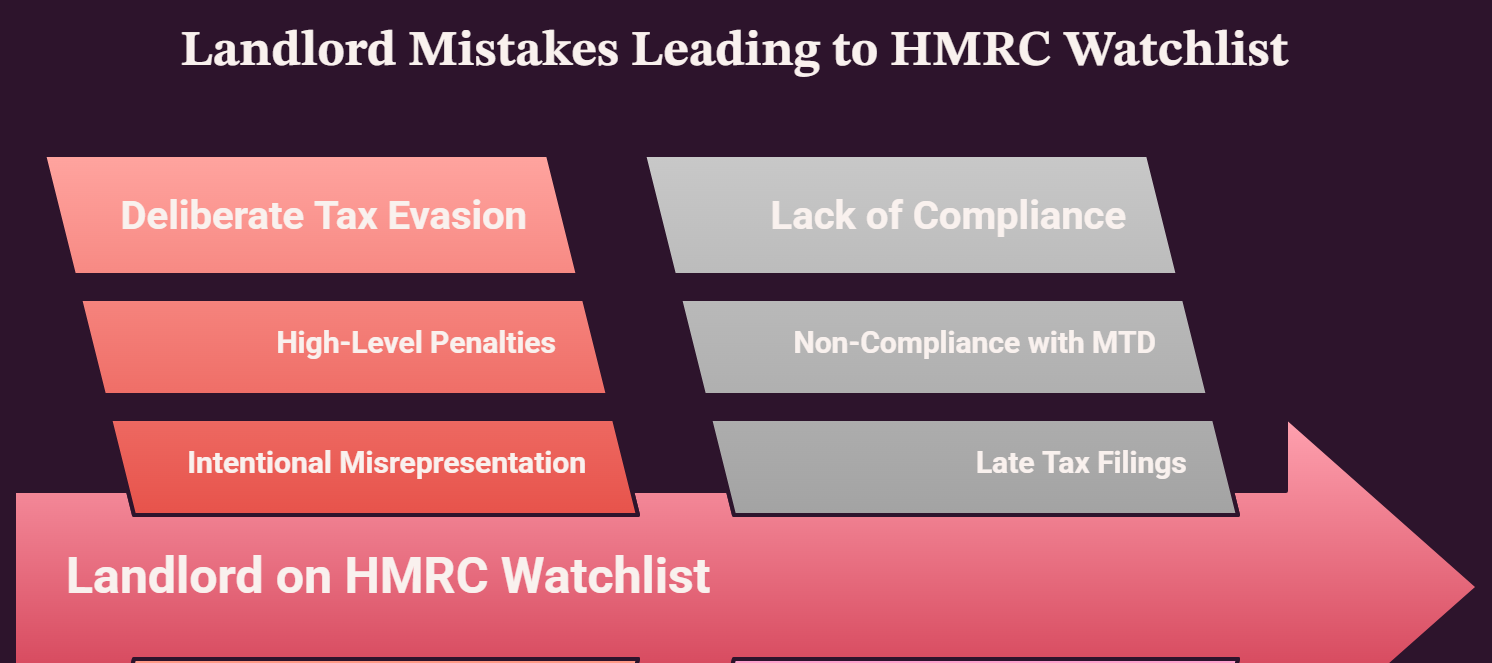
The Managing Serious Defaulters (MSD) program is an intensive, non-public monitoring regime. HMRC places you in this category if you have committed deliberate tax evasion or received high-level penalties.

Under MSD monitoring, you lose your right to file simplified tax returns. Instead, you must submit exhaustive financial records for up to five years. Officers frequently conduct unannounced physical inspections of your business premises.

The Publishing Details of Deliberate Defaulters List

If your deliberate defaults exceed £25,000, HMRC can publish your details on their official website. This public list remains online for exactly 12 months. The published information includes your name, business address, industry, and the exact penalty amount. This public exposure can destroy your professional reputation and invalidate your commercial credit terms.

How to Handle an HMRC Watchlist Investigation

If you are placed on a monitoring list, you must take immediate steps to protect your assets. The following workflow shows how to systematically address an active enquiry.

1.   Appoint a Specialist Tax Representative: Immediate.

Do not communicate with investigators directly. Retain a qualified tax dispute lawyer or a chartered accountant who specializes in HMRC investigations to handle all correspondence.

2.   Conduct a Voluntary Internal Audit: Within 14 Days.

Review your financial records for the last six years. Identify any discrepancies in your VAT, PAYE, or Corporate Tax returns before investigators point them out.

3.  Submit an Unprompted Disclosure: Before Findings Finalise.

If you discover errors, disclose them to HMRC voluntarily. Making an unprompted disclosure significantly lowers your overall penalty rate and can keep you off the public defaulters list.

4.   Implement Strict Compliance Systems: Ongoing.

Install digital accounting software that complies with Making Tax Digital (MTD) rules. Keep perfect transaction records and submit all future returns ahead of schedule.

Key Differences in HMRC watchlist Monitoring Regimes

The table below outlines the operational differences between standard tax compliance checks and active watchlist monitoring.

FeatureStandard Compliance CheckActive Watchlist Monitoring
Public DisclosureNonePublic name-and-shame for deliberate defaults over £25k
Duration of TrackingEnds when the check closesTypically 2 to 5 years under the MSD program
Inspection FrequencyPre-arranged visitsUnannounced spot checks of premises
Record RequirementsStandard statutory booksFull, non-simplified returns with detailed ledgers
Average Penalty Range0% to 30% of tax owed35% to 100% (or up to 200% for offshore issues)

Avoiding Common Triggers for Special Monitoring

HMRC selects targets using a sophisticated data-matching system called Connect. This software cross-references your bank accounts, property registries, credit card transactions, and online sales data.

To keep your business off their radar, avoid these common red flags:

  • Consistently filing returns late or making frequent retroactive amendments.
  • Showing lifestyle assets or property purchases that do not align with your declared personal income.
  • Declaring zero profits or claiming continuous tax losses for multiple consecutive years.
  • Failing to reconcile your digital payment processor receipts with your bank deposits.

    Mistakes Landlords Make That Can Land Them on HMRC's Watchlist
    HMRC’s Watchlist

Frequently Asked Questions

How do you know if HMRC watchlist are investigating you?

HMRC will formally notify you by sending an opening enquiry letter in the post. This letter specifies the tax years and returns under review. It also requests detailed financial documentation to support your filings. You will not receive prior warning before this official notification arrives.

How far back can HMRC go in an audit?

If you made an honest mistake, HMRC can review your records up to four years back. For careless errors, the limit extends to six years. However, if they suspect deliberate tax fraud or evasion, they can audit your accounts up to 20 years back.

What triggers an HMRC tax investigation?

An investigation is usually triggered by anomalies flagged by HMRC’s Connect data-matching software. Common triggers include declaring sudden drops in income, reporting continuous business losses, and omitting offshore assets. Discrepancies between your VAT submissions and bank accounts also draw attention.

Can you stop an HMRC compliance check?

You cannot legally block an active HMRC compliance check once it starts. However, you can apply for Alternative Dispute Resolution (ADR) if you disagree with their methodology. You can also appeal formal information notices if the requested data is irrelevant to the tax period.

What is the penalty for deliberate tax evasion in the UK?

Penalties for deliberate tax evasion range from 35% to 100% of the unpaid tax liability. If the evasion involves offshore assets, the fine can reach 200%. Furthermore, the tax authority can initiate criminal prosecutions leading to prison sentences.

How long does a serious tax investigation take?

A standard aspect check often concludes within three to six months. In contrast, a serious fraud or deliberate evasion investigation can last between one and three years. The duration depends on the complexity of your accounts and how cooperatively you provide the requested records.

Who gets put on the HMRC watchlist deliberate defaulters list?

HMRC places individuals and businesses on this public list if they deliberately understate their tax obligations. The defaults must involve more than £25,000 in unpaid tax. You can avoid publication by making a full, cooperative disclosure before HMRC closes the investigation.

What happens during an HMRC watchlist fraud investigation?

Investigators will examine your financial statements, bank records, and physical assets with extreme scrutiny. They may conduct unannounced site visits, interview you under caution, or secure search warrants. The process ends with either a formal tax settlement or criminal prosecution.

Mistakes Landlords Make That Can Land Them on HMRC’s WatchlistBook Your Comprehensive Property Tax Review


Categories
Blogs FAQs Guides

Common Tax Mistakes That Cost Small Businesses Money

When you run a company, managing your business tax obligations is often the most stressful part of the job, a single missed deduction or late filing can result in steep IRS penalties. Fortunately, most of these issues are entirely preventable. Let us look at where founders slip up and how you can keep more money in your pocket.

1. Mixing Personal and Business Accounts

Co-mingling your funds is the fastest way to trigger an IRS audit. If you buy groceries with your company credit card, you cloud your financial tracking.

Keep your accounts completely separate. Open a dedicated business checking account on day one. Pay for your software, inventory, and office supplies exclusively from this account. Doing so makes it incredibly simple to track write-offs and proves your business legitimacy to the IRS.

2. Missing Out on Valid Deductions

Many founders fail to claim legitimate write-offs. They leave money on the table out of fear of audits. If you use part of your home strictly for work, you can claim the home office deduction.

Keep a detailed log of your vehicle mileage. Save every receipt for meals with clients. Use accounting software to scan and categorize bills automatically. Over a year, these small deductions add up to thousands of dollars in business tax savings.

3. Misclassifying Your Workers

The IRS heavily polices the line between independent contractors and employees. If you control when, where, and how a worker performs their tasks, they are likely an employee.

Misclassifying a worker on a Form 1099 instead of a Form W-2 can cost you. You could face back taxes for FICA, federal unemployment taxes, and steep penalties. Review the IRS common law rules to ensure you classify your team members correctly.

How Business Tax Oversight Compares

The table below breaks down the financial impact of three frequent mistakes.

MistakeTypical Direct CostSimple Fix
Co-mingling FundsHigh audit risk, lost deduction trackingOpen a dedicated business account
Worker MisclassificationThousands in unpaid payroll taxes & finesUse IRS Form SS-8 for determination
Missing Mileage Tracking$0.67 per mile lost (IRS standard rate)Use an automatic mileage tracking app

4. Forgetting Estimated Quarterly Taxes

The US tax system operates on a pay-as-you-go model. If you expect to owe more than $1,000 when you file your annual return, you must make quarterly payments.

Missing these deadlines leads to underpayment penalties. Set aside 25% to 30% of your net income each month in a separate savings account. Pay your estimated installments by April 15, June 15, September 15, and January 15.

5. Filing Your Taxes Late

Procrastinating on your tax return is expensive. The failure-to-file penalty is 5% of your unpaid taxes per month. This fee is ten times higher than the failure-to-pay penalty of 0.5%.

Even if you do not have the money to pay your bill, you must file your return on time. Alternatively, file Form 7004 or Form 4868 to request an automatic six-month extension. This simple step eliminates the harsh late-filing fees.

businesses tax
businesses tax

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture makes an error, the IRS sends a notice detailing the discrepancy. You may face penalties and interest on unpaid balances. Correcting the issue quickly minimizes financial damage. Working with a CPA helps resolve these issues.

Can you write off small business expenses without revenue?

Yes. You can write off startup costs up to $5,000 in your first active year. If your business has not launched yet, these costs are capitalized. They are then amortized over 15 years instead of being deducted immediately.

What is the most common businesses tax write-off for small businesses?

The most common deduction is ordinary and necessary operating expenses. This category includes rent, utilities, software subscriptions, advertising, and professional fees. Tracking these items continuously ensures you lower your overall business tax burden during filing season.

Do small businesses get audited often?

Small businesses face relatively low audit rates, usually under 1%. However, high-risk behaviors increase your chances of a review. These triggers include reporting consistent net losses, mixing personal expenses, and failing to report 1099 payments.

Is it better to file small business taxes as an LLC or S-Corp?

It depends on your net income. An LLC is simple and avoids double taxation. However, an S-Corp can reduce self-employment taxes once your business generates significant revenue. Consult a professional to see which structure fits your growth.

How much can a business write off without receipts?

The IRS generally requires receipts for any business expense over $75. However, you still need to document the time, place, and business purpose. Keeping digital copies of all receipts is the safest way to defend your deductions.

What happens if you do not pay estimated quarterly taxes?

If you skip quarterly payments, the IRS charges an underpayment penalty. The fee is calculated based on how much you owed and how late you paid. You can easily avoid this by making timely, estimated payments.

Can you deduct personal cell phone use for business?

Yes, you can deduct the business portion of your personal phone bill. You must calculate the exact percentage of time you use the device for work. Keep itemized phone bills to prove this split during an audit.

Learn More


Categories
Articles Blogs FAQs Guides

UK Stamp Duty Guide 2026

Understanding Stamp Duty UK 2026 is essential before buying a home or investment property. Whether you’re a first-time buyer, homeowner, landlord, or investor, knowing how Stamp Duty Land Tax (SDLT) works can help you avoid unnecessary costs and stay compliant with UK property purchase tax rules.

Everything you need to know about Stamp Duty UK 2026:

What Is Stamp Duty Land Tax (SDLT)?

Stamp Duty Land Tax (SDLT) is a tax paid when purchasing residential or commercial property in England and Northern Ireland above the applicable threshold. The amount you pay depends on the property’s value, your buyer status, and whether you’re purchasing an additional property.

For a complete explanation of UK property taxes, read our Property Tax Guide.

How Much Stamp Duty Will I Pay in 2026?

Your Stamp Duty bill depends on the property’s purchase price, whether you’re a first-time buyer, and if you’re buying an additional property. Current SDLT rates and reliefs should always be checked before completing your purchase.

You can also learn how to legally reduce your SDLT bill by reading our How to Reduce Stamp Duty Legally guide.

Who Is Exempt From Paying Stamp Duty?

Some buyers may qualify for exemptions or reliefs, including eligible first-time buyers and certain property transfers. Always confirm your eligibility before claiming any relief.

Do First-Time Buyers Pay Stamp Duty?

Many first-time buyers qualify for Stamp Duty relief, helping reduce the amount of tax payable on qualifying property purchases.

How Is Stamp Duty Calculated?

Stamp Duty is calculated based on the property’s purchase price, current SDLT tax bands, buyer status, and whether additional property surcharges apply.

If you’re buying property as an investment, our Property Investor Tax Strategy Guide can help you plan ahead.

When Do I Have to Pay Stamp Duty?

Stamp Duty is normally due shortly after completing your property purchase. Missing the deadline may result in penalties and interest.

Can I Reduce My Stamp Duty Bill Legally?

Yes. There are legitimate Stamp Duty reliefs and exemptions available depending on your circumstances. Professional tax advice can help ensure you only pay what you legally owe.

What Happens If I Pay Stamp Duty Late?

Late payment can lead to HMRC penalties, interest charges, and unnecessary delays. Paying on time helps you avoid additional costs.suspects-fraud-cop9

Official HMRC Guidance

For the latest Stamp Duty Land Tax rates and official government guidance, visit the HMRC Stamp Duty Land Tax page.

HMRC compliance
HMRC compliance

You can also check the latest residential Stamp Duty rates on the UK Government SDLT Rates page.


Need expert advice on Stamp Duty UK 2026?
Contact Felix & Co Chartered Tax for professional guidance on Stamp Duty Land Tax, property purchase tax, and all UK property tax matters.

Book a Free Consultation

Categories
Articles Articles Blogs Guides

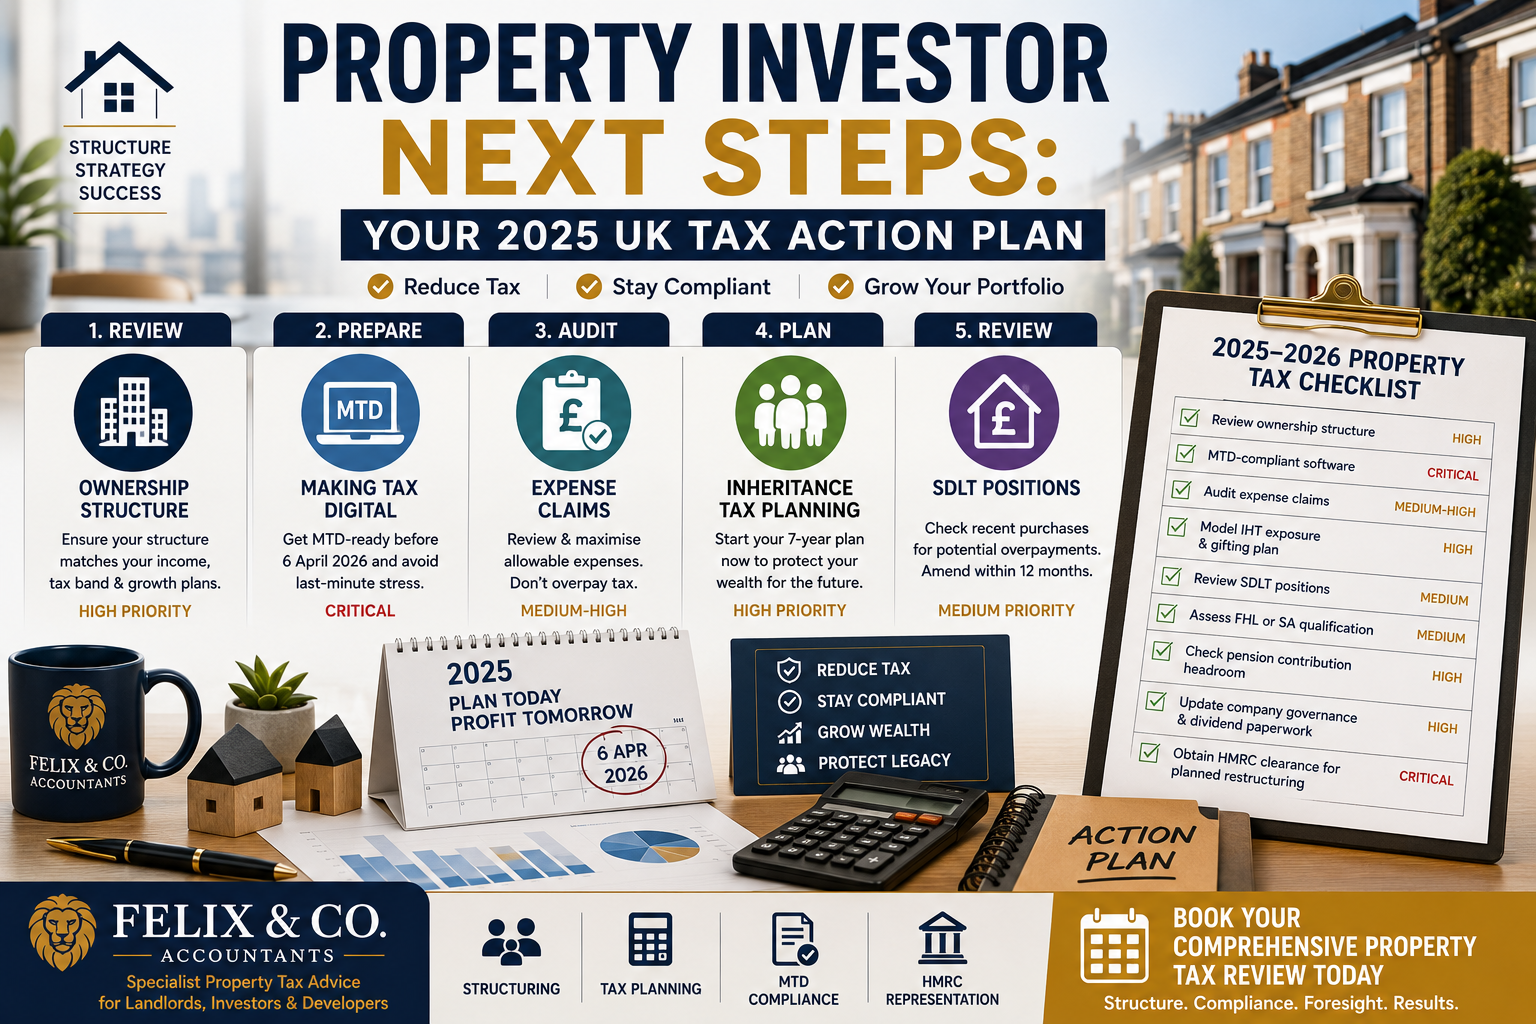
Property Investor Next Steps: Your 2025 UK Tax Action Plan

As a property investor, understanding tax rules is only the first step. The real value comes from turning that knowledge into practical action. Throughout this series, we’ve explored ownership structures, allowable expenses, SDLT planning, inheritance tax, company structures, and compliance obligations. This final guide provides a clear and prioritised property investor tax strategy for 2025, helping you protect profits, reduce tax liabilities, and prepare for future growth.

property investor

The Core Principle Every Property Investor Should Follow
Tax efficiency in property is not a one-time decision — it is a continuous process. Tax legislation changes. Your portfolio grows. Your income changes. Your family circumstances evolve. An annual review of your tax position is not optional; it is a professional obligation to your own financial future.


Property Investor Action 1: Review Your Ownership Structure

Ask yourself whether your current structure — personal, corporate, or LLP — still aligns with your investment strategy and income needs. Key triggers for a structure review:

  • You own four or more properties personally and are a higher-rate taxpayer
  • Your mortgage interest is significantly restricted under Section 24
  • You are reinvesting profits rather than living off them
  • You have family members who could benefit from share gifting
  • You are planning to grow the portfolio significantly in the next 5 years

Personal vs company ownership — 2025 guide


Property Investor Action 2: Prepare for Making Tax Digital

If your property income exceeds £50,000, you must be fully MTD-compliant from 6 April 2026 — less than 12 months away. Steps to take immediately:

  1. Select an HMRC-approved accounting platform (QuickBooks, Xero, FreeAgent, or a property-specific system)
  2. Migrate from spreadsheets to the new platform and reconcile current-year figures
  3. Set up bank feeds for automatic transaction capture
  4. Confirm your bookkeeper or accountant is familiar with MTD quarterly submission requirements

Property records and Making Tax Digital


Property Investor Action 3: Audit Your Expense Claims

Most landlords underclaim expenses. A professional review of your last two years of tax returns commonly identifies missed claims for replacement domestic items, apportioned phone and broadband costs, travel to inspect properties, and professional fees. Each missed £1,000 of expense costs between £200 and £450 in unnecessary tax.

Allowable expenses for property investors


Property Investor Action 4: Start Inheritance Tax Planning Now

IHT planning has a minimum seven-year horizon. The best time to start was seven years ago; the second best time is today. Key steps:

  1. Prepare an up-to-date inventory of all property assets with current market values
  2. Calculate your total IHT exposure above available NRB and RNRB allowances
  3. Identify which properties could be gifted (as shares if in a company) to begin the seven-year clock
  4. Review whether a Family Investment Company or trust would benefit your specific circumstances
  5. Ensure a current will is in place that correctly reflects all property ownership structures

Pass on property wealth without paying too much tax


Property Investor Action 5: Review SDLT Positions on Recent Purchases

If you have purchased property in the last 12 months, a professional SDLT review may identify overpayments — particularly where a mixed-use classification or Multiple Dwellings Relief could have applied but wasn’t claimed. HMRC allows amendments within 12 months of the filing date.

How to legally reduce stamp duty


Property Investor Tax Checklist for 2025–2026

ActionPriorityTimeline
Review ownership structure with a specialist accountantHighWithin 3 months
Select and migrate to MTD-compliant softwareCritical (if income >£50k)Before 6 April 2026
Audit last 2 years of expense claimsMedium-HighBefore next tax return
Model IHT exposure and begin gifting planHighWithin 6 months
Review SDLT positions on recent purchasesMediumWithin 12 months of each purchase
Assess FHL or SA qualification for short-term letsMediumAt portfolio review
Check pension contribution headroom for corp tax efficiencyHighBefore year-end
Ensure company board minutes and dividend documentation are currentHighAnnually
Obtain advance HMRC clearance for any planned restructuringCriticalBefore any transaction
Felix Accountants: Your Property Tax Partner
From first-time landlords to multi-entity developers, Felix Accountants provides specialist property tax advice, structuring, MTD compliance, and HMRC representation. Whether you need a tax review, incorporation planning, or a complete group restructure — we are your trusted property tax partner.


Complete Article Series — Internal Links

1 — Ownership structure | 2 — Allowable expenses | 3 — Paying yourself | 4 — Incorporation relief | 5 — VAT and property

6 — SPV structures | 7 — Records and MTD | 8 — Reducing SDLT | 9 — Pension property investment | 10 — Advanced structures

11 — Inheritance tax | 12 — Portfolio demergers | 13 — SA and HMO tax | 14 — Furnished Holiday Lets

Frequently Asked Questions

How often should I review my property tax position?

At minimum annually — ideally before the end of each tax year (5 April) and immediately after any significant transaction such as a purchase, sale, refinance, or structural change to your portfolio. Tax legislation changes frequently; your accountant should flag relevant changes proactively.


What is the single most impactful tax action a UK landlord can take in 2025?

For higher-rate taxpayers owning properties personally with significant mortgage debt, reviewing whether to incorporate (transferring to a limited company) typically delivers the largest single improvement in after-tax income. The combination of lower corporation tax and full interest deduction can add thousands annually per property.


How do I know if I need specialist property tax advice vs a general accountant?

If you own more than two properties, operate any form of company structure, have significant mortgage debt, are planning to pass assets to family, or are considering serviced accommodation or development, you need a specialist. General accountants may miss reliefs that a property tax specialist would apply as standard.


What should I do first if I am worried about unpaid property tax?

Consider the Let Property Campaign — HMRC’s voluntary disclosure process that allows landlords to bring their tax affairs up to date with significantly reduced penalties. An unprompted disclosure through the LPC consistently results in lower penalties than an HMRC-initiated investigation. See felixaccountants.com/let-property-campaign/ for detailed guidance.


How can Felix Accountants help me with my property tax?

Felix Accountants provides a full spectrum of UK property tax services: ownership structure reviews, incorporation planning, SDLT mitigation, MTD compliance setup, IHT structuring, FHL qualification reviews, corporate group design, and Let Property Campaign disclosures. Book a free 30-minute consultation at calendly.com/fndeloh/30min to discuss your specific position.


Property success in 2025 and beyond depends on structure, compliance, and foresight. Book your comprehensive property tax review with Felix Accountants today.

Book Your Comprehensive Property Tax Review


JSON-LD Schema Markup