If you have previously unreported rental income, an adviser can help you establish what needs correcting, which years are affected and what evidence supports the figures. You can then decide on the appropriate HMRC route with a clearer understanding of the work involved.
Don’t wait for the letter to arrive. If you have undisclosed rental income in London, Slough, Windsor, Reading, or Oxford, taking the first step today is the only way to stay in control of your finances.
SCHEDULE A CALL WITH AN EXPERT
You’re about to learn exactly how the disclosure process works, why local market nuances in places like Windsor and Oxford matter to your tax bill, and how an expert ensures you pay the absolute legal minimum in penalties and interest.
What is a Let Property Campaign Expert?
An adviser can review the rental records, calculate an evidence-based tax and interest position, identify allowable costs where appropriate, and help prepare a disclosure and correspondence. Any penalty remains subject to the applicable law and HMRC’s assessment.
Why complete rental records matter
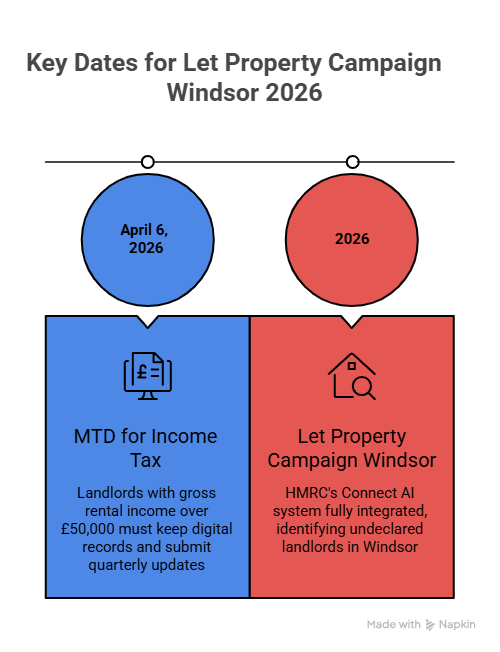
HMRC’s “Connect” system is an AI-driven database that cross-references billions of data points. For a landlord in Reading or London, this means HMRC knows when a property title changes, when a deposit is protected, and when a tenant claims housing benefits at your address.
The Let Property Campaign (LPC) is a specific opportunity for landlords who have failed to disclose their rental income to come forward. It’s not a “get out of jail free” card, but it is a “stay out of court” card. If you come to them before they send you a “nudge letter,” the penalties are significantly lower. If you wait until they find you, those penalties can reach 100% of the tax owed—or lead to criminal prosecution.
Why Location Matters: From Oxford Students to Slough Corporates
The evidence needed for a rental disclosure depends on the property and the landlord’s records, not simply the town or city. Tenancy agreements, agent statements, bank records and property-specific costs are useful wherever the property is located.
Oxford and Windsor: High-value areas with complex HMO (House in Multiple Occupation) setups or short-term holiday lets. These often involve higher management costs and maintenance fees that many landlords forget to deduct.
London and Slough: High churn rates and corporate lets. If you’ve had periods of vacancy or spent heavily on “repair vs. improvement” (a massive distinction in tax law), an expert ensures these are categorized to your advantage.
Reading: An area with high professional rental demand where landlords often move from a primary residence to a “buy-to-let” without realizing the CGT (Capital Gains Tax) implications of their future plans.
An expert understands that a £2,000 monthly rent in Slough looks different on a balance sheet than £5,000 in Kensington. They use local market data to justify your figures if HMRC questions the “commerciality” of your arrangements.
The Danger of the “DIY” in Let Property campaign Disclosure
Many landlords think the Let Property Campaign is as simple as filling out a form and cutting a check. It’s not. The biggest risk isn’t the tax itself; it’s the interest and the penalty classification.
HMRC classifies your “failure to notify” into three buckets:
Reasonable Excuse: You had a genuine reason (illness, bereavement) for not filing.
Careless: You didn’t take enough care to get it right.
Deliberate: You knew you owed tax and chose not to pay.
The explanation of why income was missed should be truthful, complete and supported by the evidence. An adviser can help organise that explanation without changing the facts or promising a particular penalty outcome.
Step-by-Step: How an Expert Navigates Your Let Property campaign
Disclosure
1. The Portfolio Audit
Before speaking to HMRC, your advisor will reconstruct your financial history. This involves gathering bank statements, letting agent statements, and receipts for every tap fixed or wall painted over the last several years. They don’t just look for income; they hunt for “missing” expenses like mortgage interest (subject to Section 24 restrictions), insurance, and service charges.
2. The Notification Phase
The deadline for making the disclosure is measured from the notification acknowledgement. Notifying HMRC does not create a general protection from investigation or enforcement.
3. Technical Calculations
Calculating the tax is the easy part. The hard part is calculating the Section 24 interest relief and the tapered penalties. Since 2017, mortgage interest isn’t a direct deduction from rental income for individual landlords; it’s a 20% tax credit. Many DIY landlords still try to deduct the full interest, which is an immediate red flag for HMRC.
4. The Disclosure Submission
The final report is sent via the Official Government Gateway. This isn’t just a number; it’s a narrative. An expert includes a “disclosure letter” explaining why the omission happened, which is vital for minimizing penalties.
5. Payment and Settlement
Your expert helps arrange payment. If you can’t pay the full amount (which often happens when multiple years of back-tax are due), they negotiate a “Time to Pay” arrangement, allowing you to spread the cost without HMRC freezing your assets.
Comparison: Expert Disclosure vs. HMRC Discovery
“Professional support may make record gathering and calculations easier, but it does not change HMRC’s legal powers or guarantee reduced penalties. The main difference is the route being used, whether HMRC has already begun an enquiry, and the quality and completeness of the disclosure. For a detailed comparison of disclosure routes, see the article on LPC versus HMRC investigation.”
The “Repair vs. Improvement” Trap
This is where most London and Windsor landlords lose money. If you replace a broken wooden window with a double-glazed uPVC window, HMRC usually views that as a “repair” (deductible from income tax). If you build an extension or install a high-end designer kitchen where a basic one existed, that’s an “improvement” (deductible from Capital Gains Tax when you sell).
Without an HMRC Let Property Campaign expert in Slough or London, you might try to claim an extension against your rental income. HMRC will reject it, charge you a penalty for a “careless” error, and you’ll still owe the tax. An expert knows how to categorize these costs to maximize your current cash flow while protecting your future tax position.
Is it too late if I already received a Let Property campaign letter?
Responding promptly and accurately is sensible. However, professional representation does not prevent HMRC from asking questions about other tax matters when it has a lawful reason to do so.
Strategy Framework: The Felix Approach to Let Property campaign
We don’t just crunch numbers. We look at the “Three Pillars of Protection”:
Documentation: Creating a “bulletproof” trail of expenses to offset income.
Mitigation: Arguing for the lowest possible penalty tier based on your life circumstances.
Future-Proofing: Setting up your digital records to comply with Making Tax Digital (MTD) for landlords, so you never end up in this position again.
Whether you’re a landlord with one flat in Reading or a portfolio in Oxford, the goal is the same: total compliance with minimum financial damage.
FAQ: People Also Ask
How many years does the Let Property Campaign go back?
HMRC can go back up to 20 years if they believe the failure to pay was deliberate. If it was a “careless” mistake, they usually look back 6 years. If you took “reasonable care” but still got it wrong, the limit is typically 4 years. An expert helps determine which limit applies to you.
What are the penalties for the Let Property Campaign?
Penalties range from 0% to 100% of the tax owed. For voluntary disclosures where the landlord was “careless” but helpful, penalties are often between 0% and 15%. If HMRC finds you first, those rates jump significantly.
Can I include mortgage interest in my Let Property campaign disclosure?
For individual landlords, the rules for residential property finance costs may restrict deductions and provide a basic-rate tax reduction, subject to the facts and the tax year. Historic disclosures must consider the rules applicable to each year.
Do I have to pay the Let Property campaign full amount immediately?
Not necessarily. While HMRC prefers immediate payment, a Let Property Campaign expert can often negotiate a payment plan (Time to Pay arrangement) if you can demonstrate that a lump sum payment would cause “undue hardship.”
Does the Let Property campaign apply to holiday lets or Airbnb?
Yes. The Let Property Campaign covers all residential property, including specialized lets like Airbnb, student housing, and holiday rentals in areas like Oxford or Windsor. It does not cover commercial property (shops or offices).
What expenses can I claim to reduce my tax bill?
You can claim letting agent fees, property insurance, maintenance and repairs (not improvements), utility bills you paid, council tax during void periods, and professional fees like accountancy or legal costs related to the tenancies.
When is professional help most useful?
Some landlords can prepare a straightforward correction using complete records. Others may benefit from advice, especially where a property was inherited, jointly owned, let while living abroad, or used partly as a holiday let. A disclosure covering several years can also involve changes in tax treatment, historic mortgage costs, missing evidence or old returns that need separate attention.
An adviser should explain what they will check, what records they need and which aspects of the work they will handle. You should still understand the figures and approve the explanation before anything is sent to HMRC. The goal is a complete, well-supported disclosure rather than a particular penalty promise. If your position involves more than one property or tax year, Felix & Co. can review the scope of work with you
What should I bring to the first consultation?
Prepare a short note explaining when each property started producing rent, who owns it and whether you have received any HMRC letters. Gather the information you already have rather than delaying because a complete bundle is not yet available. Useful documents include tenancy agreements, letting agent statements, rent receipts, bank statements, mortgage interest summaries, insurance invoices and receipts for repairs.
If you previously filed Self Assessment returns, keep copies of the property pages and tax computations. It is also helpful to list any gaps in the records and say which years they affect. This gives an adviser a practical starting point for understanding the disclosure and discussing what work is needed. Ask Felix & Co. what documents to send securely before your consultation.
How do I compare quotes from accountants?
A useful quote should make clear what the fee covers. Ask whether it includes a review of each tax year, rental profit calculations, interest and penalty workings, HMRC notification, the formal disclosure, and follow-up questions. Check whether additional work, such as amending recent Self Assessment returns, is charged separately. You may also need to clarify who will speak to HMRC, who will approve the final figures and whether support continues after submission.
Be cautious about any adviser who promises a fixed penalty rate or guaranteed acceptance before reviewing your records. Fees and turnaround times depend on the work required and should be explained in writing. Felix & Co. can discuss the likely scope of a disclosure after reviewing your circumstances
| Do You Need a Let Property Campaign Expert to Put Things Right? Book Your Comprehensive Property Tax Review |