Categories
News

The 90-Day Clock: How to Prepare Your Documentation for an LPC Submission

Preparing the documents for a Let Property Campaign disclosure can feel daunting when several tax years are involved. Gather the rent, expense and tax records first, then check the deadline shown in HMRC’s notification acknowledgement. The disclosure is normally due within 90 days of receiving that acknowledgement, not automatically 90 days after you decide to notify HMRC.

At Felix Accountants, we call this the “Execution Phase.” The 90-day window sounds generous, but when you are dealing with years of missing bank statements and complex tax rules, time disappears quickly. Here is your roadmap to a successful submission.

1. The Timeline: Notification to Settlement

HMRC sets a deadline for the disclosure and payment. If records are missing or you expect difficulty paying, raise the issue early and check HMRC’s instructions rather than assuming a late disclosure will be accepted.

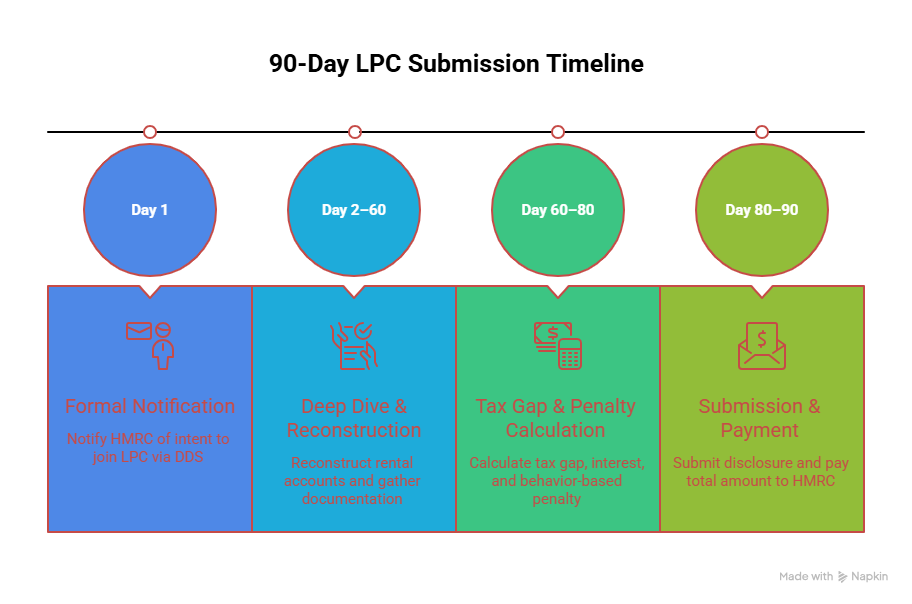
  • Day 1: Notify HMRC that you intend to make a disclosure. Keep the acknowledgement and note the deadline when it arrives.

  • Day 2–60: The “Deep Dive.” This is when we reconstruct your rental accounts.

  • Day 60–80: We calculate the “Tax Gap,” statutory interest, and the behavior-based penalty.

  • Day 80–90: Formal submission of the disclosure and payment of the total amount.

2. Essential Documentation Checklist

To make an accurate disclosure, we need to move beyond “estimates” wherever possible. You should begin gathering:

  • Income Records: Tenancy agreements, letting agent annual statements, or bank statements showing rent deposits.

  • Expense Evidence: Invoices for repairs, insurance certificates, management fee statements, and utility bills for void periods.

  • Mortgage Data: Annual mortgage interest certificates (usually provided by your lender every January).

  • Other Income Info: Your P60 or P11D (if employed) or self-employed accounts. Your rental tax is determined by your total income, so we need the full picture to apply the correct tax bands.

Which rental documents matter most to HMRC?

Start with a separate folder for each tax year you may need to review. Put tenancy agreements and letting-agent statements in the income folder, then reconcile them to bank statements and any direct payments made by tenants. For costs, retain invoices and receipts for repairs, insurance, management and other property expenses, along with mortgage statements where relevant. Keep copies of tax returns or other information previously given to HMRC so that amounts already reported are not included again.

If a property was jointly owned, add a note of the owners and the period of ownership. A short schedule showing the property address, rental dates, total rent and expenditure is helpful. The aim is to make the calculation understandable and traceable, not merely to produce a pile of documents. If you are unsure which records apply, request a review before preparing the final disclosure.

3. Dealing with Missing Records

What if you don’t have bank statements from six years ago?

  • Bank Requests: Most banks can provide historic statements for a small fee, though this can take 2–3 weeks (hence the urgency).

  • Reasonable Estimates: Reasonable estimates: If older bank statements cannot be obtained, HMRC says you may need to use more recent records as a guide. Explain the method used, keep the calculations and identify which amounts are estimates. Do not assume unrelated market averages will be accepted as evidence.

  • The Narrative: We must include a note in your disclosure explaining why records are missing and how we reached our estimates.

What if I cannot get older bank statements or receipts?

Missing paperwork does not mean you should omit the income or invent an expense figure. HMRC advises asking the bank for copies of past statements. If they cannot be obtained, more recent statements may sometimes provide a basis for a carefully explained estimate.

Make a note of the bank request, the months missing and any alternative evidence, such as tenancy agreements, agent summaries or invoice copies. Work through the same approach for each affected tax year and record how any estimated amount was calculated. It is especially important to distinguish evidence from an assumption. HMRC may ask why the original statements were unavailable and how you reached the numbers. If the gaps are substantial, seek advice before sending the disclosure. Felix & Co. can help identify what further documents are needed and explain a defensible calculatios.

4. Calculating the “Add-Ons”: Interest and Penalties

Your disclosure isn’t just about the tax. HMRC expects you to “Self-Assess” two other figures:

Statutory Interest

This is not a penalty; it is compensation to the government for not having the money on time. Interest rates for late tax have risen significantly in 2025 and 2026. We use specialized software to calculate interest from the date the tax should have been paid to the current date.

The Penalty Offer

You must make a “Formal Offer” of a penalty. As discussed in previous articles, this is based on your behavior:

  • Reasonable Care: 0%

  • Careless (Unprompted): 0% – 30%

  • Deliberate (Unprompted): 20% – 70%

5. Making the “Formal Offer”

The disclosure includes a formal offer based on the income, tax, interest and any penalties calculated. HMRC may review the figures and request further information before deciding whether to accept the offer. Acceptance should not be described as immunity from further questions if the information is materially incomplete or incorrect.
documents for let property campaign

6. What If You Can’t Pay Everything on Day 90?

If the final bill is larger than expected, do not wait until Day 90 to tell HMRC. * We can negotiate a “Time to Pay” (TTP) arrangement.

  • Payment plans are considered on the circumstances. If you cannot pay the full amount, contact HMRC before submitting the disclosure and discuss the information they need to assess a proposed arrangement.

What if I cannot afford to pay the disclosure in full?

Do not ignore the payment issue while you finish the calculations. HMRC expects payment with the disclosure, but its Let Property Campaign guidance explains what to do if you cannot pay the full amount. Contact the campaign helpline as soon as possible and before submitting. HMRC may ask about your income, household outgoings, assets and debts, as well as the amount and timing of any payments you propose.

Keep the disclosure reference number to hand when calling. The purpose is to discuss an arrangement based on your actual finances, not to assume a standard instalment period will be available. HMRC says you should speak to it before submitting the disclosure or payment if you cannot pay in full. If the calculation is uncertain, get the figures reviewed promptly so that the payment conversation is based on a realistic amount.

Frequently Asked Questions (FAQs)

Q1: Can I submit the disclosure before the 90 days are up?

Yes. You can submit as soon as your figures are ready. In fact, submitting early reduces the amount of statutory interest you have to pay.

Q2: What happens if I miss the 90-day deadline?

HMRC may remove you from the campaign. This means you lose the “favourable terms” and lower penalties. They may then open a formal enquiry into your affairs.

Q3: Does HMRC check every single disclosure?

HMRC reviews disclosures and may contact you or your adviser for explanations or supporting records. Its guidance does not promise an acceptance decision within a fixed number of days.

Q4: Do I need to send my receipts to HMRC with the disclosure?

HMRC may ask for the records supporting your figures or for an explanation of estimates. Keep the relevant evidence and calculations in line with the record-keeping requirements that apply to your circumstances and tax years.

Q5: Can Felix Accountants handle the payment for me?

You usually pay HMRC directly using your PRN (Payment Reference Number). However, we ensure you have the exact bank details and references to ensure your payment is allocated correctly to your disclosure.

Beat the Crock with Felix Accountants

The 90-day window is the final hurdle to tax peace of mind. Let Felix Accountants take the lead on the calculations and the paperwork, so you can focus on the future of your property investment.

Start My 90-Day Disclosure Process

Categories
News

HMRC ‘Connect’: How Big Data is Finding Undeclared Landlords in 2026

For decades, many landlords believed that if they didn’t use a letting agent or if their tenants paid in cash, they were “invisible” to the tax man. In 2026, that era is officially over.  HMR Revenue & Customs (HMRC) now utilizes one of the most sophisticated data-mining systems in the world: HMRC Connect. This software is the engine behind the thousands of “nudge letters” being sent to UK property owners. At Felix Accountants, we want our clients to understand how this technology works so they can appreciate the urgency of the Let Property Campaign (LPC).

1. What is the Connect System?

Connect is an AI-powered data warehouse that holds over 55 billion items of data. It doesn’t just store information; it “crawls” through dozens of different databases to find “inconsistencies” in your lifestyle versus your declared income.

In 2024-25 alone, this system helped HMRC recover an extra £4.6 billion in underpaid tax. By 2026, its reach has expanded to include real-time feeds from digital platforms and international banks.

2. Where Does the Data Come From?

Connect creates a “web” of your financial life by pulling from over 30 different sources:

  • The Land Registry: Every property purchase, sale, and mortgage charge is logged here.

  • Stamp Duty Records: HMRC knows exactly how much you paid for your second home.

  • Letting Agent Returns: Letting agents are legally required to provide annual lists of their landlord clients.

  • Digital Platforms (Airbnb/Booking.com): Since 2024, these platforms have shared host income, booking numbers, and property locations directly with HMRC.

  • Tenancy Deposit Schemes: If you protect a deposit (as required by law), you have just created a digital record of your tenancy.

  • Council Tax & Electoral Roll: If you are registered to vote at Address A but own Address B, and Address B has a different person paying council tax, Connect flags a potential rental.

  • Social Media Scrapping: In 2026, HMRC uses AI to monitor public social media for “lifestyle indicators.” A landlord posting about luxury holidays while declaring a £5,000 annual profit may trigger an audit.

3. The “Inconsistency” Flag: How You Get Targeted

HMRC doesn’t need “proof” to send you a nudge letter; they only need an anomaly.

Example Scenario:

  1. Source A (Land Registry): Shows you bought a second flat in Bristol in 2022.

  2. Source B (Bank): Shows regular monthly deposits of £1,200 labeled “Flat 2.”

  3. Source C (Tax Return): Shows zero rental income declared.

Connect automatically cross-references these three points. The system then generates a “nudge letter” or, in more serious cases, assigns an investigator to open a Compliance Check.

HMRC Connect AI
HMRC Connect AI

4. Making Tax Digital (MTD) 2026: The Next Level

As of April 2026, the reporting rules have tightened even further. Landlords with a gross rental income over £50,000 must now use Making Tax Digital for Income Tax (MTD IT).

  • You must keep digital records of every penny of rent and every expense.

  • You must send quarterly updates to HMRC using compatible software.

  • The Impact: This moves property tax from an “annual event” to a “real-time” surveillance system. If you aren’t already compliant for past years, the start of MTD makes your history much more likely to be scrutinized.

5. Can You “Opt-Out” of the Big Data Search?

Short of selling your properties and closing your bank accounts, you cannot opt-out of HMRC’s data gathering. The UK has also signed up to the Common Reporting Standard (CRS), meaning even if your rental income is in an overseas bank account, that bank is likely sending your data back to the UK.

The only way to “stop” an investigation before it starts is to make a Voluntary Disclosure.

6. How Felix Accountants Uses This Information to Help

Because we understand the “Connect” logic, we can help you:

  • Pre-emptive Audits: We can look at your bank statements and Land Registry records exactly how HMRC does to find “red flags” before they do.

  • Accurate Disclosures: When we submit your Let Property Campaign disclosure, we ensure it matches the digital footprint HMRC already has. Disclosing less than what Connect shows is the fastest way to trigger a full-scale fraud investigation.

  • Future Compliance: We set you up with MTD-compliant software so your digital records are “audit-proof” moving forward.

Frequently Asked Questions (FAQs)

Q1: Does HMRC really look at my Instagram or Facebook?

HMRC has confirmed they use AI to monitor social media as part of investigations into suspected tax fraud. While they don’t look at every landlord’s holiday photos, they use it to verify “lifestyle” claims during a formal enquiry.

Q2: My tenant pays me in cash. Am I safe from Connect?

Not necessarily. Even if there’s no bank trail, Connect sees the Land Registry ownership and the fact that a different person is paying Council Tax at that address. The “absence” of income where a property is clearly being lived in is itself a red flag.

Q3: How far back does the “Connect” data go?

HMRC has been building this database since 2010. They have over a decade of historical records that can be searched at any time.

Q4: I use an Airbnb but I’m under the £7,500 Rent-a-Room limit. Will I be flagged?

You might still receive a nudge letter because Airbnb reports the “gross” income. If you receive a letter, don’t ignore it; we can help you respond to HMRC explaining that your income is covered by the Rent-a-Room relief.

Q5: Is it better to wait for HMRC to contact me?

Absolutely not. Once Connect triggers a letter, you move from “Unprompted” to “Prompted” status, which instantly increases your potential penalties by 15-30%.

Don’t Let the AI Find You First

In 2026, tax evasion is a “data problem” that HMRC is winning. If you have undeclared property income, the Let Property Campaign is your only legal exit ramp.

Get my ‘Connect’ Risk Assessment

Categories
News

Mortgage Interest & Maintenance: Maximize Your Expenses in an LPC Disclosure

When you are making a historical disclosure via the Let Property Campaign, you aren’t just telling HMRC about the rent you received; you are also claiming the deductions you were entitled to over those years. Rental Tax relief.

At Felix Accountants, our expertise lies in identifying every possible “allowable expense” to ensure you only pay tax on your actual profit, not your gross turnover. In a 2026 disclosure, navigating the complex rules of Section 24 mortgage interest and the “Repair vs. Improvement” debate is where thousands of pounds can be saved.

1. The Section 24 “Mortgage Interest” Trap

Since 2020, the way landlords claim mortgage relief has changed fundamentally. You can no longer deduct mortgage interest from your rental income to reduce your taxable profit. Instead, you receive a 20% Tax Credit.

How it works in your disclosure:

If you are disclosing for years after 2020:

  1. We calculate your tax on your full rental income (minus maintenance and fees).

  2. We then take 20% of your mortgage interest and subtract that figure from your total tax bill.

The Impact: If you are a higher-rate (40%) taxpayer, you are effectively “losing” 20% of the relief you used to get. However, for many “accidental landlords” who remain in the basic rate band, the 20% credit still covers the full interest cost.

2. Maintenance: Is it a “Repair” or an “Improvement”?

This is the most contested area in any HMRC disclosure.

  • Repairs (Revenue Expenses): These are deductible from your rental income now.

  • Improvements (Capital Expenses): These cannot be used in your LPC disclosure. Instead, they are saved to reduce your Capital Gains Tax when you sell the property.

ItemClassificationTax Treatment
Fixing a broken boilerRepairDeduct from Rent (LPC)
Repainting between tenantsRepairDeduct from Rent (LPC)
Replacing broken windowsRepairDeduct from Rent (LPC)
Building an ExtensionImprovementDeduct from Sale (CGT)
Installing a New ConservatoryImprovementDeduct from Sale (CGT)
Upgrading a KitchenImprovement*Deduct from Sale (CGT)

*Note: If you replace an old kitchen with a “like-for-like” modern equivalent, it is often treated as a repair. If you upgrade from laminate to granite or add more cupboards, it becomes an improvement.

3. The “Wholly and Exclusively” Rule

To be deductible in your disclosure, an expense must be incurred “wholly and exclusively” for the purposes of the property business.

  • Allowable: Letting agent fees, landlord insurance, Gas Safety certificates, and accountancy fees for the disclosure itself.

  • Partial: If you use your car to visit the property, we can claim 45p per mile for those specific journeys.

  • Not Allowable: Your personal phone bill (unless you have a dedicated “landlord” line) or clothing bought for DIY work.

4. Replacement of Domestic Items Relief (RDIR)

In your disclosure, we can claim for the cost of replacing furnishings and appliances provided for the tenant’s use. This includes:

  • Movable furniture (beds, sofas).

  • Household appliances (fridges, washing machines).

  • Floor coverings and curtains.

Crucial Rule: You can only claim the cost of the replacement, not the initial purchase of the first item you put in the house.

Rental Tax relief.
Rental Tax relief

5. Maximizing Your “Pre-Letting” Expenses

Many landlords spend thousands fixing up a property before the first tenant moves in.

  • If the work was to fix “wear and tear” from the previous owner so it was in a fit state to rent, these are often Capital (Improvement) costs.

  • However, if the work was “revenue” in nature (decorating, minor repairs), we can often claim these as “Pre-trading expenses” provided they were incurred within 7 years of the rental start date.

6. How Felix Accountants Adds Value

In an LPC disclosure, every £1,000 of expenses we find could save you up to £400 in tax and £100 in penalties.

  1. Historical Record Reconstruction: We help you dig through old bank statements to find forgotten costs.

  2. Aggressive (but Legal) Deduction: We ensure you claim the maximum mileage and home-office allowances.

  3. Interest & Penalty Mitigation: By lowering the “tax gap” through expenses, the interest and penalties automatically decrease.

Frequently Asked Questions (FAQs)

Q1: I don’t have receipts from 4 years ago. Can I still claim?

Yes. HMRC accepts “Reasonable Estimates” if you can show a bank transfer or a clear need for the work (e.g., a plumber’s visit showing on a statement without the invoice).

Q2: Can I claim my own time if I did the DIY work myself?

No. You can only claim for the cost of materials. You cannot “charge” your own business for your labor.

Q3: Are letting agent fees deductible?

Absolutely. 100% of management fees, finders’ fees, and inventory costs are deductible from your rental income before tax is calculated.

Q4: What about the “Property Allowance”?

You have a £1,000 tax-free property allowance. If your total expenses are less than £1,000, it is usually better to just claim this “flat rate” rather than counting individual receipts.

Q5: Can I deduct my mortgage capital repayments?

No. Only the interest element of your mortgage payment qualifies for the 20% tax credit. The part of your payment that pays off the loan itself is not a tax-deductible expense.

Lower Your Disclosure Bill Today

Don’t pay more than you legally owe. A specialist review of your expenses is the most effective way to reduce the cost of your Let Property Campaign settlement.

Start My Expense Audit

Categories
Blogs FAQs News

How Far Back Can HMRC Go for Rental Income You Did Not Declare?

If you have undeclared rental income, it is natural to ask how far back HMRC can go for rental income. There is no single time limit that applies to every case. The answer depends on the tax years involved, whether you registered or filed returns, and the circumstances of the missing income. Start by checking what you reported and when you began receiving rent.

At Felix Accountants, we specialise in analysing your history to ensure you only pay for the years legally required. Here is a breakdown of the 4, 6, and 20-year rules.

1. The 4-Year Rule: “Reasonable Care”

Where a landlord filed a return and took reasonable care, HMRC guidance describes a shorter assessment period in appropriate cases. This does not mean every honest error is automatically limited to the same years. Check the filing history and the conditions that apply

What defines “Reasonable Care”?

HMRC acknowledges that tax is complicated. You might fall into this category if:

  • You sought advice from a professional that turned out to be incorrect.

  • You made an honest mathematical error despite keeping good records.

  • You reasonably believed you didn’t owe tax (e.g., your expenses legitimately wiped out your profit, but you didn’t realise you still had to file a nil return).

The Result: You pay the tax and interest for the last 4 years, and often, you can negotiate a 0% penalty.

2. The 6-Year Rule: “Careless” Behaviour

The most common category for “accidental landlords” is Careless Behaviour. This applies if you failed to tell HMRC about your rental income because you didn’t check the rules, but you weren’t trying to hide the money.

Examples of Careless Behaviour:

  • You moved in with a partner and rented your old flat but “forgot” to tell HMRC.

  • You assumed your letting agent was paying your tax for you.

  • You didn’t keep proper records and guessed your figures.

Carelessness may affect the years HMRC can assess, but the relevant dates and reporting history must be reviewed. The period for an incorrect return is not necessarily the same as one for failing to notify HMRC in the first place. Any penalty should be assessed separately from the tax years due.

3. The 20-Year Rule: “Deliberate” or “Failure to Notify”

HMRC may need to review a longer period where a person deliberately understated income or did not tell HMRC that tax was due. Those are different factual situations. If you never registered for Self Assessment or failed to report rent on existing returns, ask a qualified tax adviser to establish which rules apply

What defines “Deliberate” Behaviour?

  • You intentionally kept rental income out of your tax returns to pay less tax.

  • You provided false information to HMRC or concealed records.

  • You have been a landlord for a decade but never registered for Self Assessment.

The Result: You must disclose every year of income for the last two decades. Penalties for deliberate acts are much higher, ranging from 20% to 100% (and up to 200% if the income involves offshore accounts).

4. The “Offshore” Exception: The 12-Year Rule

If your case involves a property outside the UK or periods when you lived abroad, separate the property location, your residence history and the relevant tax reporting obligations. Offshore matters can be more complicated than a straightforward UK letting, so the period that can be assessed needs individual checking.

5. How Behaviour Impacts Your Penalty (The “Felix” Strategy)

Felix & Co. can help review your reporting history, the records available and your explanation of what went wrong. HMRC assesses the facts of each case, and it is important not to assume a particular behaviour category before reviewing the evidence. Our role is to prepare a clear, supported account.

  • Evidence-Based Arguments: We present your “Reasonable Excuse” (e.g., serious illness, bereavement, or reliance on a trusted family member) to move you from the 20-year bracket to the 6 or 4-year bracket.

  • Proactive Disclosure: By using the Let Property Campaign voluntarily, we demonstrate that you are not “concealing” income, which is the strongest defence against the 20-year rule.

    Tax Look-back
    Tax Look-back
BehaviourAssessment PeriodPenalty (Unprompted)
Reasonable Care4 Years0%
Careless6 Years0% – 30%
Deliberate20 Years20% – 70%
Deliberate & Concealed20 Years30% – 100%

6. Can HMRC Find Me After 20 Years?

If earlier rental years remain undeclared, it is safer to review the position than to assume it will never be queried. HMRC can obtain information through various lawful channels, but no particular sale or transaction means that an investigation is inevitable. Focus on establishing which years need correction and keeping a record of the steps you take.

How do I catch up on years of undeclared rental income?

Begin with a list of the tax years in which you received rent, noting the property, gross rent and any amounts already included on a tax return. Then gather letting-agent statements, tenancy agreements and bank records so you can work out what is still missing. Do not assume that every old year belongs in the same type of HMRC submission.

The Let Property Campaign guidance distinguishes years that should be reported through a Self Assessment return from earlier liabilities that may need to be disclosed. It also explains that income already reported should not be disclosed again. The sensible order is to map the facts, check the correct reporting route and then calculate tax, interest and any penalties. You can ask Felix & Co. to review that timeline before anything is submitted.

What if I rented out several properties over the years?

If you have rented more than one property, start by preparing a separate history for each address. Record when each property first produced rent, any periods when it was empty, and when it was sold or stopped being let. Next, bring those records together by tax year and compare them with the property income previously declared. HMRC confirms that the Let Property Campaign can apply to landlords with multiple residential properties.

What matters for your calculation is the rental income and relevant expenses for each year, rather than the number of properties you own today. If a property was jointly owned, check whose rental income needs to be reported and whether a separate disclosure is required for each person. A clearly organised schedule helps avoid both omissions and counting the same income twice

What proof should I keep for rental expenses?

A useful starting file includes rent statements, bank statements, invoices for repairs, letting-agent charges, insurance documents and any calculations used in earlier returns. Keep the details by property and tax year so it is clear which cost belongs to which period. HMRC’s Let Property Campaign guidance says that if your records are incomplete, you should use reasonable estimates and retain an explanation of how you arrived at them. It also recommends requesting replacement bank statements where possible.

Do not treat an unsupported guess as proof, and do not assume that every cost connected with a property is deductible. Capital improvements and day-to-day running costs can receive different tax treatment. If the records are incomplete, begin with what you have, document the gaps and ask for help working out which expenses can be claimed.

Frequently Asked Questions (FAQs)

Q1: What if my rental business made a loss 5 years ago?

If you made a legitimate tax loss in a specific year (e.g., due to major repairs), that year does not “count” toward your liability, though it still falls within the look-back window. We can often use those losses to offset profits in later years.

Q2: My father died and left me a rental property he never declared. How many years do I pay?

If an inherited rental property is involved, establish whether the income was received before or after the former owner died and who is responsible for each period. The position of an estate and the position of a new owner are not necessarily the same.

Q3: Does the 20-year rule apply if I simply didn’t know the law?

HMRC generally argues that “ignorance of the law is no excuse.” However, if we can show you had a “Reasonable Excuse” for not knowing (such as being given bad advice by a previous accountant), we can often fight to keep the period to 6 years.

Q4: If I come forward now, can I choose which years to pay?

You should not leave out relevant years simply because they are difficult to reconstruct. HMRC expects an accurate and complete disclosure of previously undeclared liabilities. However, a particular omission does not automatically mean fraud proceedings will follow. Ask an adviser to review the correct tax years and reporting route.

Q5: Will HMRC ask for bank statements from 20 years ago?

If you are in the 20-year bracket and don’t have records, we use “Reasonable Estimations.” We can use historic rental averages and ONS data to recreate your accounts in a way that HMRC will accept.

Know Your Years, Protect Your Future

Determining your “behaviour” is the most technical part of a tax disclosure. Don’t guess and end up paying for 20 years when you only owed 6.

Contact Felix Accountants today. We will review your history and ensure your disclosure is handled with the correct look-back period.

Book my 4-6-20 Year Review

Categories
News

The £7,500 Limit: When Your Lodger Income Triggers a Tax Bill

In 2026, with the cost of living remaining high, more UK homeowners than ever are turning to the Rent-a-Room Scheme. It’s a fantastic government incentive that allows you to earn a significant amount of tax-free income by letting out a furnished room in your main home.

However, there is a “magic number” you need to watch: £7,500. Go even a penny over this gross limit, and your tax position changes instantly. At Felix Accountants, we help live-in landlords navigate this threshold to ensure they stay compliant without overpaying. Here is the essential guide to the £7,500 limit.

1. How the Rent-a-Room Scheme Works in 2026

The scheme is designed for “resident landlords.” To qualify:

  • The property must be your only or main residence.

  • The room must be furnished.

  • You can be an owner-occupier or a tenant (as long as your lease allows sub-letting).

The Automatic Exemption

If your total gross receipts from lodgers are £7,500 or less per tax year, the income is tax-free. You don’t even need to tell HMRC about it unless you are already filing a Self Assessment tax return for other reasons.

2. What Counts Towards the £7,500?

A common mistake landlords make is thinking only the “rent” counts. In the eyes of HMRC, your gross receipts include everything the lodger pays you:

  • Base Rent: The monthly fee for the room.

  • Utility Contributions: If the lodger pays a share of the gas, electricity, or Wi-Fi.

  • Services: Any extra charges for laundry, cleaning, or providing meals.

Example: If you charge £600 a month in rent and £50 for bills, your annual gross receipts are £7,800. Even though your “profit” might be low, you have officially exceeded the £7,500 threshold.

3. The “Joint Owner” Trap: £3,750

If you own your home jointly with a spouse, partner, or friend, the £7,500 allowance is split equally.

  • Each person has a tax-free limit of £3,750.

  • This applies regardless of how you actually split the money. If you have one lodger paying £6,000 a year, and the property is jointly owned, you both have exceeded your individual £3,750 limits and must both file a tax return.

4. You’ve Gone Over £7,500: What Happens Next?

If you exceed the limit, you must complete a Self Assessment tax return. You then have two ways to calculate your tax:

Method A: The Rent-a-Room Method (Best for low expenses)

You pay tax only on the amount above £7,500. You cannot deduct any expenses (like repairs or utilities) because the £7,500 allowance is designed to cover them.

  • Example: Income is £9,000. You pay tax on £1,500.

Method B: The Actual Profit Method (Best for high expenses)

You ignore the Rent-a-Room scheme and pay tax on your actual profit (Total Income minus Actual Expenses).

  • Example: Income is £9,000, but you spent £3,000 on a new boiler for the lodger’s room and increased utility bills. Your profit is £6,000. In this case, Method B is better because you pay tax on £6,000 instead of the £7,500 “excess.”

    Rent-a-Room Scheme
    Rent-a-Room Scheme

5. Using the Let Property Campaign for Lodger Income

If you’ve had a lodger for several years and only just realized you were over the £7,500 limit, don’t panic. The Let Property Campaign (LPC) isn’t just for whole-house rentals; it’s also the perfect tool for live-in landlords to “catch up.”

  • Voluntary Disclosure: By coming forward via the LPC before HMRC finds you (perhaps via Airbnb data sharing), you can secure the lowest possible penalties.

  • Multiple Years: We can help you look back at your history, determine which years you were over the limit, and settle the total bill in one go.

6. How Felix Accountants Optimizes Your Lodger Tax

We don’t just “file your taxes”—we strategize.

  • Yearly Election: We calculate both Method A and Method B every year to see which saves you more. You can switch between them annually!

  • Expense Tracking: We help you identify “allowable expenses” you might have missed if you choose Method B.

  • HMRC Correspondence: If you receive a nudge letter regarding Airbnb or lodger income, we take over the communication.

Frequently Asked Questions (FAQs)

Q1: Can I use the Rent-a-Room scheme for an Airbnb?

Yes, provided the room is in your main home and you are living there during the guest’s stay. If you rent out a separate, self-contained annex or a second home, you cannot use this scheme.

Q2: Can I claim the £1,000 Property Allowance as well?

No. You cannot use both the Rent-a-Room relief and the £1,000 Property Allowance against the same income.

Q3: What if I have two lodgers?

The £7,500 limit is per property, not per lodger. If two lodgers pay you £5,000 each, your total income is £10,000, and you are over the limit.

Q4: My lodger is a “Monday to Friday” worker. Does the limit still apply?

Yes. The nature of the stay doesn’t matter, as long as the room is in your main home and furnished.

Q5: I share the house with my partner, but the mortgage is only in my name. Is the limit £7,500 or £3,750?

If you are the sole legal owner and the rent is paid to you, you usually get the full £7,500 allowance. If your partner starts receiving a share of the income, the limit splits to £3,750 each.

Don’t Let a Spare Room Become a Tax Burden

Having a lodger should be a financial help, not a source of stress. If you think you might be close to or over the £7,500 limit, Felix Accountants can help you crunch the numbers.

Book a Lodger Tax Review

Categories
News

Accidental Landlord Tax: What If You Rent Your Old Home?

For many, moving in with a partner is a major romantic milestone. It often leads to a practical question: “What do we do with my flat?” If you decide to keep your original home and rent it out, you have officially joined the ranks of the “Accidental Landlord.”

While it seems like a straightforward way to cover your mortgage or build an investment, renting out your former residence triggers a series of tax obligations that many people overlook until they receive a “nudge letter” from HMRC. At Felix & Co., we can help you check the tax position if you have started letting a former home and are unsure what needs to be reported

Here is everything you need to know about the tax implications of renting your first home when you move in with a partner.

1. Income Tax: Your New “Second Job”

Renting out a home can create taxable property income, even if you never intended to become a landlord. How and when you need to tell HMRC depends on the amount received and your circumstances.

The £1,000 Property Allowance

If your total rental income is less than £1,000 per year, you generally don’t need to do anything. However, for most landlords renting out a whole property, income will far exceed this.

Registering for Self Assessment

If your gross property income exceeds the property allowance, you may need to contact HMRC or register for Self Assessment, depending on the amount and your circumstances. You must notify HMRC by 5 October following the tax year in which you started receiving rent.

  • Example: If you moved in with your partner and started renting your flat in September 2025, you must register by 5 October 2026.

How Much Tax Will You Pay?

Rental profit is added to your other income (like your salary).

  • Basic Rate (20%): Total income between £12,571 and £50,270.

  • Higher Rate (40%): Total income between £50,271 and £125,140.

  • Additional Rate (45%): Total income over £125,140.

2. The Mortgage Interest Trap (Section 24)

Ten years ago, landlords could deduct their full mortgage interest from their rental income before paying tax. This is no longer the case.

You now pay tax on the full amount of rent minus “allowable expenses” (like insurance and repairs). For individual residential landlords, finance-cost relief is generally given as a basic-rate tax reduction and may be limited by the relevant tax rules. It is not the same as deducting the full mortgage payment

  • The Risk: If you are a higher-rate taxpayer (40%), you are still paying 40% tax on the income used to pay the mortgage but only getting 20% back in relief. This can lead to situations where your “cash flow” is positive, but you are actually losing money after tax.

3. Stamp Duty (SDLT): The Cost of the “Next” Home

If you move in with your partner but decide to buy a new home together while keeping your old one, you will likely hit the Stamp Duty Surcharge.

If you buy another home while keeping your first property, higher Stamp Duty Land Tax rates may apply in England and Northern Ireland. The position depends on the purchase and ownership circumstances. Scotland and Wales have different transaction taxes. On a £400,000 house, this surcharge alone adds £20,000 to your moving costs.

The 36-Month Refund: If you sell your original home within 36 months of buying the new one, you can usually claim a refund of that 5% surcharge.

4. Capital Gains Tax (CGT): Losing Your Relief

While you live in your home, it is exempt from Capital Gains Tax thanks to Private Residence Relief (PRR). However, the moment you move out and rent it, that exemption starts to “tarnish.”

When you eventually sell the property:

  • You get relief for the years you lived there as your main home.

  • You get relief for the final 9 months of ownership, even if you weren’t living there.

  • Letting a former home can affect the proportion of any future gain covered by Private Residence Relief. The calculation may also depend on other qualifying periods and the circumstances of the sale

The Rate: In 2026, CGT on residential property is 18% for basic rate taxpayers and 24% for higher rate taxpayers.

5. Don’t Forget the “Consent to Let”

Technically not a tax, but a legal must: You must notify your mortgage lender. Renting out a property on a standard residential mortgage without Consent to Let is a breach of contract. Lenders may increase your interest rate or demand immediate repayment if they find out via HMRC data sharing.

6. How the Let Property Campaign Can Help

If you moved in with a partner years ago and haven’t declared the rent, the Let Property Campaign (LPC) is your best solution. It allows “Accidental Landlords” to come forward voluntarily.

  • Lower Penalties: If earlier rental income was missed, the reason for the error and the records available should be reviewed before any penalty position is proposed. No particular penalty outcome can be promised.

  • Catching Up: We can help you file for multiple years at once, ensuring you are fully compliant before you buy your next home together.

Frequently Asked Questions (FAQs)

Q1: My partner and I aren’t married. How does that affect the tax?

If the property is in your name only, the income is 100% yours for tax purposes. If you own it jointly, the income is usually split 50/50. Being unmarried means you can’t use “Form 17” to shift income to the lower-earner as easily as married couples can.

Q2: Can I deduct the cost of the new furniture I bought for the tenants?

No. You cannot deduct the initial cost of furniture. However, you can claim Replacement of Domestic Items Relief when you eventually replace those items (like a broken sofa or fridge).

Q3: What if my rental income doesn’t cover my mortgage?

You may still owe tax. Because you can’t deduct the full mortgage payment (only the interest, and only as a 20% credit), you can have a “taxable profit” even if your bank account shows a loss each month.

Q4: Does HMRC really know if I’m renting out my old flat?

Yes. HMRC’s “Connect” system tracks Land Registry changes and matches them against the electoral roll and Tenancy Deposit Schemes.

Do not assume HMRC either knows everything or knows nothing about a tenancy. The sensible step is to check your own income records and reporting obligations.

Q5: I only plan to rent it for a year. Do I still need to tell HMRC?

Yes. There is no minimum time limit. If you earn over £1,000 in a tax year, it must be reported.

Q6: Do I need to tell HMRC if I rent my old home for just a few months?

Where to insert: After “The £1,000 Property Allowance” Suggested heading: Do I need to tell HMRC if I rent my old home for just a few months?

Don’t Let Your “New Start” Be Ruined by Old Tax

Moving in together should be an exciting time, not a source of future legal stress. If you’ve recently become an accidental landlord, let Felix Accountants review your numbers and handle the HMRC registration for you.

If earlier rental income was missed, the reason for the error and the records available should be reviewed before any penalty position is proposed. No particular penalty outcome can be promised

Get an Accidental Landlord Tax Review

Categories
News

The Non-Resident Landlord Guide: How Overseas Owners Can Use the LPC

Living abroad doesn’t mean you’re out of reach for HM Revenue & Customs (HMRC). In fact, in 2026, the digital trail left by overseas landlords is easier than ever for the UK tax office to follow. Whether you’re a UK expat working in Dubai, a retiree in Spain, or a foreign investor, if you receive income from a UK property, you generally owe UK tax. Expat Tax Rules

Many overseas landlords mistakenly believe that because they pay tax in their country of residence, or because their UK letting agent deducts tax at source, they have no further obligations. At Felix Accountants, we specialize in the Non-Resident Landlord Scheme (NRLS) and helping overseas owners regularize their past through the Let Property Campaign (LPC).

1. What is the Non-Resident Landlord Scheme (NRLS)?

The NRLS is a tax regulation designed to ensure HMRC gets its cut of rental income from landlords whose “usual place of abode” is outside the UK (typically staying abroad for 6 months or more).

Under the scheme, there are two ways tax is collected:

  1. Withholding at Source: Your letting agent (or your tenant, if they pay over £100/week) must deduct 20% basic rate tax from your rent and pay it directly to HMRC.

  2. Gross Payment: You can apply to HMRC using Form NRL1 to receive your rent in full. If approved, you are responsible for paying the tax yourself via a Self Assessment tax return.

The Common Trap: Receiving rent “gross” does not mean the rent is tax-free. It simply means you’ve promised HMRC you will handle the paperwork yourself. If you receive rent gross but fail to file a return, you are in breach of the scheme.

2. Why Overseas Landlords are “High Risk” for HMRC

In 2026, HMRC’s Connect system is linked to global exchange agreements. HMRC now receives data from banks in over 100 countries. If you are transferring funds from a UK letting agent to an overseas account, or if you have a UK mortgage but a foreign address, the system flags you.

Common reasons overseas landlords fall behind:

  • Assuming the Letting Agent handles it: They only deduct 20%; they don’t file your personal tax return or claim your personal allowance.

  • Double Taxation Confusion: Thinking you only pay tax where you live. (Most treaties state property income is taxed first in the country where the property is located).

  • The “Mortgage Wash” Myth: Thinking that if the rent just covers the mortgage, there is no profit to declare.

3. How the Let Property Campaign Works for Expats

If you’ve realized you have years of undeclared UK income, the Let Property Campaign (LPC) is your best route to safety. It is open to non-resident individuals (but not companies or trusts).

The Advantage for Expats:

If you come forward voluntarily, we can often argue that being “out of the country” or “confused by international rules” constitutes Reasonable Care or a Non-Deliberate error.

By using the LPC, you can:

  • Secure lower penalties (often 0% to 20%).

  • Avoid a formal, intrusive tax enquiry that might look into your other global assets.

  • Clean up your UK record before you decide to sell the property or move back.

4. Capital Gains Tax: The “Exit” Trap

If you are an overseas landlord looking to sell your UK property in 2026, you face a strict Non-Resident Capital Gains Tax (NRCGT) regime.

  • You must report the sale to HMRC within 60 days of completion.

  • You must pay the tax within that same 60-day window.

  • The Problem: If your rental income history isn’t clean, HMRC may hold up the sale or use the sale notification to trigger an audit of the last 20 years of rent.

Using the Let Property Campaign before you list the property for sale is a vital strategic move.

5. Claiming Your Personal Allowance

Even as a non-resident, many people (including UK citizens and EEA nationals) are still entitled to the UK Personal Allowance (£12,571 in 2026).

  • If your UK rental profit is £10,000, and you have no other UK income, you owe £0 in tax.

  • However, you must still file a return to claim this allowance. If your agent has been deducting 20% tax, you can actually use your tax return to claim a refund of every penny they took.

6. How Felix Accountants Supports Global Landlords

Distance shouldn’t be a barrier to compliance. We offer a digital-first service for overseas clients:

  • Remote Consultation: Video calls in your time zone.

  • Digital Disclosure: We handle the entire LPC submission through HMRC’s Digital Disclosure Service.

  • NRL1 Applications: We help you apply to receive rent gross for the future.

  • Refund Management: If you’ve overpaid via withholding tax, we get your money back.

Frequently Asked Questions (FAQs)

Q1: I pay tax in the USA/Dubai/Australia. Do I still pay in the UK?

Yes. The UK has the “primary taxing right” on UK land. You pay the UK first. You can then usually claim a “Foreign Tax Credit” in your home country so you don’t pay twice on the same money.

Q2: My tenant pays me directly into my UK bank account. Does HMRC know?

Highly likely. In 2026, banks share “suspicious activity” reports and data on large regular transfers with HMRC. Furthermore, the Land Registry records show you own the house but aren’t living there.

Q3: Can I use the LPC if I own the property through a BVI or Jersey company?

No. The Let Property Campaign is for individuals only. Non-resident companies must use a different disclosure route and are subject to UK Corporation Tax.

Q4: I haven’t lived in the UK for 10 years. How far back will they look?

If the failure to disclose was “Careless,” they look back 6 years. If they deem it “Deliberate” (because you knew the rules but ignored them), they can go back 20 years.

Q5: Will using the LPC affect my immigration status or visa?

Usually, no. HMRC is a separate department from the Home Office. In fact, having “clean” tax affairs is often a requirement for many visa renewals and citizenship applications.

Protect Your UK Investment from Abroad

Don’t let an administrative oversight in the UK turn into a global legal headache. Whether you owe tax or are due a refund, Felix Accountants will bridge the gap between you and HMRC.

Book a Global Expat Consultation

Categories
News

Joint Ownership Tax: Why Both Owners Must Disclose Separately to HMRC

One of the most common reasons landlords fail a tax audit is a misunderstanding of how Joint Tax Ownership. Many couples assume that if the rent goes into a joint bank account, or if one partner manages the property, only one tax return is needed.

In 2026, HMRC’s “Connect” system is specifically designed to flag properties with multiple owners where only one (or neither) is declaring income. At Felix Accountants, we frequently handle cases where a husband and wife are both pursued for back-tax because they didn’t realize that joint ownership requires dual disclosures.

1. The “50/50 Rule” for Married Couples

If you are married or in a civil partnership and living together, HMRC applies a strict “default” rule: Rental income is split 50/50 for tax purposes.

It does not matter if:

  • One of you earned all the money to buy the house.

  • The rent is paid into only one person’s bank account.

  • One of you does all the “work” of being a landlord.

Unless you have a specific legal agreement (see Form 17 below), HMRC will expect each of you to declare exactly 50% of the profit on your own individual tax returns.

2. The “Separate Disclosure” Requirement

This is the part that catches most people out during the Let Property Campaign (LPC). If a husband and wife have undeclared income from a jointly owned property:

  • You cannot make one joint disclosure.

  • Each person must notify HMRC separately.

  • Each person will receive their own unique Disclosure Reference Number (DRN).

  • Each person must submit their own 90-day calculation showing their share of the income.

The Risk: If only the husband discloses and the wife doesn’t, HMRC will accept the husband’s money but then open a separate investigation into the wife for her 50% share—often with higher “prompted” penalties.

3. Changing the Split: Form 17 and Deeds of Trust

Sometimes, it is more tax-efficient for the lower-earning partner to receive more of the income. For example, if the wife is a basic-rate taxpayer and the husband is a higher-rate taxpayer, you might want a 90/10 split in her favor.

To do this legally in 2026, you must:

  1. Have a Deed of Trust: A solicitor must draft a document showing you own the property in unequal shares (as “Tenants in Common”).

  2. Submit Form 17: You must notify HMRC of this unequal split within 60 days of signing the deed.

Important Note for LPC: You cannot backdate a Form 17. If you are disclosing for the last 6 years and you only just signed a Deed of Trust, you must still disclose the previous years on a 50/50 basis. You can only use the new split for the future.

Joint Ownership Tax_ Why Both Owners Must Disclose Separately to HMRC - visual selection
Joint Ownership Tax_ Why Both Owners Must Disclose Separately to HMRC – visual selection

4. Unmarried Joint Owners (Friends, Siblings, Partners)

If you own a property with someone you are not married to, the rules are different:

  • You are generally taxed according to your actual ownership share (e.g., if you own 70% of the house, you pay tax on 70% of the rent).

  • You can agree to a different split of profits and losses, but it must reflect the reality of your agreement and be supported by evidence.

  • Just like married couples, both of you must file separate tax returns or LPC disclosures.

5. The “Personal Allowance” Strategy

Joint ownership is often a powerful tool for reducing your total tax bill.

  • Example: A property makes £20,000 profit. If only one person owns it and they are a higher-rate taxpayer, they pay £8,000 in tax.

  • If a married couple owns it 50/50, they each have £10,000 profit. If neither has other income, that £10,000 falls within their Personal Allowance (£12,571), and the total tax bill is £0.

This is why HMRC is so aggressive in checking that both parties are declaring; the “missing” 50% often represents a significant amount of lost tax revenue for the government.

6. How Felix Accountants Manages Joint Disclosures

When a couple comes to us with a joint property issue, we provide a coordinated service:

  • Mirror-Image Disclosures: We prepare both disclosures simultaneously to ensure the figures match perfectly (HMRC will flag any discrepancies).

  • Penalty Mitigation: We argue that since you are disclosing as a household, you are showing maximum cooperation, which helps keep penalties for both partners at the minimum.

  • Future-Proofing: We help you decide if a Form 17 election is right for you moving forward to keep your future tax bills as low as possible.

    Joint Tax Disclosure
    Joint Tax Disclosure

Frequently Asked Questions (FAQs)

Q1: My husband is the only one on the mortgage, but we both own the house. Who pays the tax?

Tax follows beneficial ownership, not necessarily the mortgage. If you have a legal document showing you both own the property, you both must declare the income. If only one person is on the title deeds, that person is usually 100% responsible unless a “Trust” exists.

Q2: We have a joint bank account where the rent goes. Is that enough for HMRC?

No. A joint bank account is not proof of a joint tax liability. HMRC looks at the legal and beneficial ownership of the property itself.

Q3: Can one of us pay the full tax bill for both of us?

No. HMRC treats you as two separate taxpayers. You must each pay your own share of tax, interest, and penalties from your own (or joint) funds under your own reference numbers.

Q4: What if my partner refuses to disclose?

This is a difficult situation. You should still make your 50% disclosure to protect yourself. This prevents you from being charged with “Deliberate” concealment, even if your partner remains non-compliant.

Q5: If we sell the house, do we both pay Capital Gains Tax (CGT)?

Yes. Each owner has their own CGT Annual Exempt Amount. By owning the property jointly, you can effectively double your tax-free allowance when you sell.

Double the Owners, Double the Care

Joint ownership is a great way to share the rewards of property investment, but it comes with dual responsibilities. If you and your co-owner haven’t been filing separate returns, Felix Accountants can help you both get back on track together.

Joint Tax Disclosure

Book a Joint Property Consultation

Categories
News

Inherited Property: Is Your Rental Income Taxable if Used for Care Fees?

When a family member passes away or moves into full-time residential care, the practicalities of managing their home can be overwhelming. One of the most common solutions we see at Felix Accountants is for families to rent out the property to cover the significant costs of care home fees. Care home rent tax.

There is a widespread misconception that because the money is going directly to a “good cause”—like a nursing home—the income is not taxable. Unfortunately, in the eyes of HMRC, rental income is taxable regardless of how the profit is spent. This article clarifies the tax position for executors and beneficiaries to ensure you don’t inadvertently create a new tax debt while trying to care for a loved one.

1. The “Common Sense” Myth vs. Tax Reality

Many families assume that if the care home fees are £3,000 a month and the rent is £1,500 a month, there is “no profit” and therefore no tax.

The Tax Reality: Care home fees are considered a personal living expense, not a business expense. Just as you cannot deduct your own grocery bill or rent from your salary before paying tax, you cannot deduct care home fees from rental income.

  • Example: If you receive £18,000 in rent over a year and have £2,000 in allowable property expenses (insurance, repairs), your taxable profit is £16,000. It does not matter if all £16,000 was paid to a nursing home; you still owe tax on that profit.

2. Who is Responsible for the Tax?

The person or entity responsible for paying the tax depends on the current legal status of the property.

Scenario A: The owner is still alive but in care

If your parent or relative is still the legal owner, the rental income belongs to them.

  • The Process: They (or you, via Power of Attorney) must file a Self Assessment tax return in their name.

  • The Benefit: They still get their Personal Allowance (£12,571). If their only other income is a small state pension, much of the rental income might fall within their tax-free threshold.

Scenario B: The owner has passed away (The Probate Period)

If the owner has died but the property hasn’t been legally transferred to the beneficiaries yet, the property belongs to the “Deceased’s Estate.”

  • The Process: The Executor is responsible for reporting the income.

  • The Tax Rate: Estates do not get a Personal Allowance. Rental income is usually taxed at a flat 20% basic rate from the first pound of profit.

Scenario C: You have inherited the property

Once the property is transferred into your name, the income is yours.

  • The Process: You must report the income on your own Self Assessment return. The tax rate will depend on your other earnings (20%, 40%, or 45%).

3. The Danger of “Power of Attorney” Errors

We often help clients like “Adam,” who had Power of Attorney for his father. Adam rented out his father’s house to pay for a nursing home and assumed that because he wasn’t personally keeping the money, he didn’t need to tell HMRC.

The Risk: HMRC’s “Connect” system sees the property is being rented. If no tax return is filed, they will eventually issue a “nudge letter.” If the owner is elderly or incapacitated, this can create a stressful legal situation for the family. Using the Let Property Campaign is the safest way to correct these historical oversights.

4. Allowable Expenses: What You Can Deduct

While you cannot deduct the care fees, you can deduct legitimate property costs to lower the tax bill:

  • Letting Agent Fees: Management and finders’ fees.

  • Maintenance & Repairs: Fixing a leaky roof or broken boiler (but not “improvements” like an extension).

  • Property Insurance: Landlord-specific policies.

  • Utility Bills: If paid by the landlord during void periods.

  • Accountancy Fees: The cost of preparing the rental accounts.

5. Inheritance Tax (IHT) and the “Care Fee Debt”

If the local authority is paying for care via a Deferred Payment Agreement (DPA), they are essentially placing a loan against the house.

  • When the person passes away, this “debt” is deducted from the value of the estate before Inheritance Tax is calculated.

  • However, the rental income earned while the person was alive remains subject to Income Tax. You cannot offset the IHT debt against the Income Tax bill.

6. How Felix Accountants Can Help

Managing the affairs of a relative in care is emotionally draining. The last thing you need is a dispute with HMRC. We provide:

  • Estate Tax Management: We handle the filings for executors during probate.

  • LPC Disclosures: If you’ve been renting a relative’s home for years without realizing it was taxable, we can use the Let Property Campaign to settle the history with minimum penalties.

  • Power of Attorney Support: we work with Attorneys to ensure the donor’s tax affairs are kept in perfect order.

Frequently Asked Questions (FAQs)

Q1: Is there any “Care Home Relief” for property tax?

No. There is no specific relief in the UK tax code that allows rental income to be tax-free simply because it pays for care.

Q2: What if the property is held in a Life Interest Trust?

In this case, the “Life Tenant” (the person in care) is usually entitled to the income. The trustees are responsible for ensuring the tax is paid, but it is typically taxed at the Life Tenant’s rates.

Q3: Can I split the income with my siblings to use our Personal Allowances?

Only if you all legally own a share of the property. If the property is still in your parent’s name, the income must be reported as theirs. If you have inherited it jointly, the income is split according to your ownership shares.

Q4: We are selling the house to pay the care fees. Do we pay tax on the rent in the meantime?

Yes. Even if you only rent the property for six months while waiting for a sale, that income must be declared if it exceeds the £1,000 allowance.

Q5: Does HMRC find out about inherited properties?

Yes. HMRC receives data from the Probate Office and the Land Registry. If a property changes hands and then appears on a rental site or has a tenant deposit registered, the “Connect” system will flag it.

Compassionate, Expert Tax Support

Dealing with care fees is difficult enough without a surprise tax bill. If you are managing a relative’s property, let Felix Accountants take the tax burden off your shoulders.

Book a Consultation for Estate/Care Property

Categories
News

The Certificate of Tax Position: Why You Shouldn’t Sign It (Yet)

If you have received an HMRC “nudge letter” regarding undeclared rental income, you likely found a document titled “Certificate of Tax Position” enclosed, Tax Position Cert.
The letter usually asks you to tick a box, sign the declaration, and return it within 30 days.

At Felix Accountants, our advice to landlords is simple: Do not sign this certificate without professional representation. While the document looks like a standard administrative form, it is a legally binding declaration with significant risks. This article explains why the certificate is a “trap” for the unwary and how you should respond instead to protect your interests.

1. What is the Certificate of Tax Position?

The Certificate of Tax Position is a voluntary declaration form issued by HMRC. It is designed to “nudge” taxpayers into confirming their tax status. Usually, it offers you three or four checkboxes, such as:

  • I have declared all my rental income.

  • I have not been a landlord during the specified period.

  • I have additional tax to disclose (and will use the Let Property Campaign).

HMRC uses these certificates to filter their data. If you sign saying you are up to date, they may cross-reference your signature against their “Connect” database. If there is a discrepancy, your signature becomes evidence of a deliberate false statement.

2. The Legal “Catch”: It’s Not a Statutory Requirement

One of the most important things to understand is that there is no legal obligation to sign the Certificate of Tax Position. Unlike your annual Self Assessment tax return, which you are legally required to file, this certificate is an informal request. HMRC phrases the letter to make it seem mandatory, but they cannot legally penalize you simply for refusing to sign this specific form.

Why HMRC prefers the certificate over a letter:

By getting you to sign the certificate, HMRC forces you into a “Yes/No” corner. It removes the nuance of your specific situation. A professional letter from an accountant, however, allows for context, “Reasonable Excuse,” and technical explanations that the form simply doesn’t accommodate.

3. Four Major Risks of Signing Prematurely

Risk A: The “Perjury” Trap

The certificate often includes a declaration that the information is “correct and complete to the best of my knowledge and belief.” If you sign this and it is later proven that you missed even a small amount of income, HMRC can escalate the case from a “civil error” to a criminal investigation for “Dishonest Disclosure.”

Risk B: No “Look-Back” Limit

A standard tax return covers one year. The Certificate of Tax Position often covers all previous years. By signing it, you are making a blanket statement about your entire history as a landlord. If you haven’t performed a thorough “health check” on your records for the last 20 years, you are effectively signing a blank check for HMRC to investigate you if they find a single historical error.

Risk C: Admission of Guilt

If you tick the box saying “I need to disclose,” you have formally admitted to a tax irregularity before you even know the full figures. This can sometimes limit your ability to argue for lower penalties later, as you have already conceded that your affairs were not in order.

Risk D: Triggering a Formal Enquiry

Ironically, signing the “I am up to date” box can sometimes trigger the very investigation you were trying to avoid. If HMRC’s “Connect” system has strong data suggesting you owe tax, and you sign a document saying you don’t, they will view it as a “red flag” and open a full, intrusive enquiry.

4. Why Professional “Letter of Representation” is Better

Instead of signing the certificate, Felix Accountants typically recommends responding with a formal Letter of Representation.

A letter allows us to:

  • Acknowledge the Nudge: We show HMRC you are being cooperative (which helps keep penalties low).

  • Provide Context: We can explain why income wasn’t declared (e.g., you thought the “Rent-a-Room” scheme covered it, or you were living abroad).

  • Request More Time: We can formally ask for an extension to the 30-day deadline to conduct a proper audit.

  • Specify the Route: We can state that you are using the Let Property Campaign, which is a separate and more favorable disclosure route than the certificate.

5. What If My Tax Affairs Really Are Correct?

Even if you are 100% certain you owe no tax, we still advise against signing the certificate.

If you owe nothing (perhaps because your expenses exceed your income, or you qualify for specific reliefs), a detailed letter from an accountant explaining the math is far more likely to “close” the case than a ticked box. Ticking a box provides no proof; a professional letter provides evidence.

6. How Felix Accountants Protects You

When you bring your nudge letter to us, we follow a rigorous “Protection Protocol”:

  1. Data Verification: We check what HMRC actually knows versus what your bank statements say.

  2. Strategic Refusal: We notify HMRC that our client will not be signing the certificate but will provide a full response via our firm.

  3. The “Reasonable Care” Argument: We build a case that any errors were not “deliberate,” potentially saving you thousands in penalties.

  4. Peace of Mind: We act as the “buffer” between you and HMRC, handling all correspondence so you don’t have to deal with them directly.

Frequently Asked Questions (FAQs)

Q1: The letter says I must respond within 30 days. What happens if I don’t?

Ignoring the letter is the worst option. If you don’t respond, HMRC will assume the worst and likely open a formal tax enquiry. This is much more expensive and stressful than a voluntary disclosure.

Q2: Can HMRC fine me for not signing the certificate?

No. They cannot fine you for refusing to sign the certificate itself. However, they can fine you for the underlying unpaid tax. Our goal is to fix the tax issue without using their “trap” document.

Q3: My letting agent already deducts tax. Do I still need to worry about the certificate?

Yes. Letting agents often only deduct tax for “Non-Resident Landlords,” and even then, they might not deduct the correct amount. You are still responsible for filing a personal tax return and ensuring the total tax paid is accurate.

Q4: I already signed and sent the certificate. Am I in trouble?

Not necessarily, but you should contact us immediately. If you made a mistake on the certificate, we can “pre-empt” HMRC by submitting a correction through the Let Property Campaign before they start an investigation.

Q5: Will HMRC be annoyed if I don’t use their form?

HMRC investigators are used to dealing with accountants. They actually prefer a well-structured professional disclosure over a poorly completed form, as it makes their job of closing the case easier.

Don’t Sign Your Rights Away

The HMRC nudge letter is the start of a negotiation. Don’t give away your leverage by signing a document you don’t fully understand.

Contact Felix Accountants today for a confidential review of your nudge letter and a professional alternative to the Certificate of Tax Position.

Book a Confidential Consultation