Categories
Blogs FAQs Guides

Let Property Campaign Disclosure Process: A Practical Guide

The Let Property Campaign (LPC) provides residential landlords with a route to bring their UK tax affairs up to date by disclosing previously undeclared rental income to HM Revenue & Customs (HMRC).

HMRC introduced the campaign in 2013 to encourage landlords to correct their tax affairs voluntarily. It may be relevant if you have received an HMRC nudge letter or discovered that you have not reported rental income correctly.

Making a complete disclosure can help you establish the correct tax liability and may reduce penalties, depending on the circumstances. The amount payable will depend on the tax years involved, your rental profits, the nature of the error and whether your disclosure is prompted or unprompted.

Understanding the Let Property Campaign disclosure process before you begin can help you prepare the necessary records, meet HMRC’s deadline and avoid common mistakes.

Let Property Campaign Disclosure Process: Overview

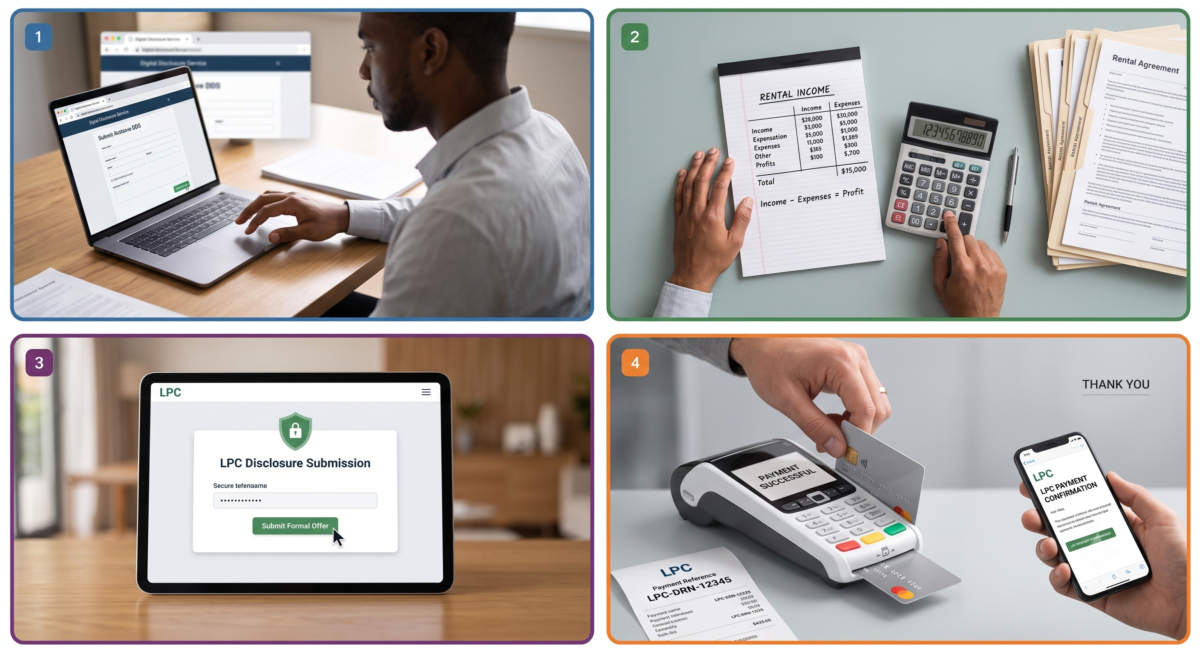
StepActionKey tasks and outputs
1. Notify HMRCSubmit the Digital Disclosure Service (DDS) notificationHMRC issues a disclosure reference number and payment reference number after notification.
2. Calculate tax and penaltiesCalculate rental profits and outstanding liabilitiesEstablish the tax, interest and any applicable penalties for the relevant years within the 90-day window.
3. Submit formal disclosureSend the completed disclosure and formal offer to HMRCHMRC reviews the submission and may ask for more details.
4. Settle the liabilityPay the amount due or discuss payment difficulties with HMRC beforehandPay by HMRC’s deadline or discuss payment difficulties with HMRC beforehand.

What Is the Difference Between Notifying HMRC and Making the Disclosure?

Notification is the first stage. You tell HMRC that you intend to put right unpaid tax from residential letting, but you do not have to provide all the rental figures at that point.

HMRC then issues reference numbers and a notification acknowledgement. The disclosure is the later stage, when you calculate the relevant income, expenses, tax, interest and any penalties and present the full explanation.

You must check the deadline on the acknowledgement. HMRC’s Let Property Campaign guidance says the disclosure must be made within 90 days of the date you receive that acknowledgement, and it explains what to do if the amount cannot be paid in full.

Keep the acknowledgement with your records and note its date. If you have several properties or years to correct, prepare one clear schedule for each year. The aim is a complete, consistent explanation that HMRC can review.

Eligibility for Let Property Campaign Disclosure

The Let Property Campaign covers individuals with undeclared income from residential property. You may be eligible if you have received rental income that was not correctly reported to HMRC.

Examples include:

  • Renting out a room in your main home where the Rent a Room relief conditions or limits have not been correctly applied.
  • Renting out one or multiple residential properties.
  • Living abroad while renting out UK residential property.
  • Living in the UK while renting out residential property overseas, where the relevant UK tax rules apply.
  • Receiving income from a holiday home that you rent out, even if you also use the property personally.

Eligibility depends on your circumstances and the type of property and income involved.

Can My Spouse and I Make One Joint Rental Income Disclosure?

HMRC says that a single Let Property Campaign disclosure cannot include more than one person. If spouses or other co-owners each have undeclared rental income, they need separate notifications and disclosures for their respective shares.

Before completing either form, compare the tenancy agreements and ownership records with the amounts shown in any previous tax returns. Agree a consistent schedule of gross rent, relevant costs and the tax years involved, then check how the income should be attributed to each person.

Do not simply assume that all jointly held properties must be reported in the same way without reviewing the facts. If one owner has already reported their share, that does not remove the need to review the other owner’s position.

Felix & Co. can help both owners prepare a clear record of what each person needs to disclose.

Exceptions

The Let Property Campaign is intended for residential landlords and does not cover every type of property or taxpayer.

It is generally not the appropriate route for:

  • Commercial property income, such as income from shops, commercial garages or storage units.
  • Rental income belonging to companies or other entities rather than an individual landlord.

Trusts and other ownership arrangements can require specific consideration. Check the current HMRC guidance to establish the correct disclosure route for your circumstances.

HMRC Nudge Letters

HMRC uses information from a range of sources to identify potential discrepancies between property ownership, rental activity and reported income. These sources may include property records and information supplied by third parties.

If HMRC identifies a possible discrepancy, it may send a letter asking you to review your tax position.

If you receive a nudge letter, read it carefully and note any response deadline. Check which tax years and properties it refers to, gather the relevant records and establish whether your previous tax returns were complete.

Do not assume that every letter has the same legal status or that receiving one automatically prevents you from making a disclosure through the campaign. Your options depend on the nature of HMRC’s contact and whether a formal enquiry or compliance check has begun.

For more information, read our guide to prompted versus unprompted disclosure.

How to Start a Let Property Campaign Disclosure

Following the correct steps helps you prepare an accurate disclosure and respond to HMRC’s requirements.

Step 1: Notify HMRC

Start by informing HMRC of your intention to disclose previously undeclared rental income. Submit your notification through the official Digital Disclosure Service (DDS) on GOV.UK.

If you are reporting income on behalf of someone who has died, make it clear that you are acting for the estate and follow HMRC’s instructions for that situation.

At this stage, you are notifying HMRC of your intention to disclose. You do not need to complete the full rental income calculation as part of the initial notification.

HMRC will issue a disclosure reference number and payment reference number. Keep these details safe and use the relevant reference when communicating with HMRC or making payments.

Information to Prepare

Personal details: When notifying HMRC, provide the information requested by the current HMRC notification service. At this stage you are notifying your intention to disclose; detailed rental figures are prepared for the later disclosure.

Property details: Prepare the addresses, years let, ownership shares, rent received and relevant records for the calculation stage. HMRC may ask for further details during the disclosure process.

You should also begin collecting tenancy agreements, rental statements, expense receipts, previous tax returns and correspondence with HMRC.

Step 2: Calculate the Tax Owed

After receiving your notification acknowledgement, you generally have 90 days to prepare and submit your formal disclosure. Check the exact deadline stated in HMRC’s acknowledgement and guidance.

For each relevant tax year, calculate your total rental income and deduct the allowable expenses for that year.

Depending on your circumstances, allowable expenses may include:

  • Letting agent fees.
  • Repairs and maintenance.
  • Property insurance.
  • Relevant safety certificates and compliance costs.
  • Other qualifying costs incurred wholly and exclusively for the rental business.

The rules for expenses, finance costs, property allowances and reliefs can vary according to the tax year and the nature of your letting activity. Do not automatically deduct every payment connected with a property.

Calculate the taxable rental profit using the rules applicable to each year. Then establish the tax due, taking account of your other income, relevant allowances, reliefs and the tax rates applicable to that period.

Do not include income that has already been correctly declared, except where a correction to the original figures is required.

You should also calculate any interest and applicable penalties. These depend on the facts of your case, including the tax years involved, the type of error and your behaviour.

Preparing clear supporting calculations for each year makes it easier to explain the figures if HMRC requests further information.

For help preparing the documents for your rental disclosure, ensure that your records are complete and consistent before submitting your figures.

Step 3: Submit the Formal Disclosure

Once you have completed your calculations, prepare the formal disclosure using HMRC’s prescribed process.

Your disclosure should explain the rental income that was omitted, the relevant tax years, the calculations supporting your figures and the circumstances that led to the original error.

Include the tax, interest and applicable penalties in accordance with HMRC’s requirements, and make the appropriate formal offer.

A formal disclosure does not mean HMRC has automatically accepted your calculations. HMRC will review the information and may ask you or your adviser to provide clarification or additional evidence.

Ensure that the figures agree with your supporting records and that any estimates are clearly explained.

Step 4: Arrange Payment

You must deal with the outstanding liability in line with HMRC’s deadline and payment instructions.

Use the payment reference number provided by HMRC when making the payment. Check the amount and reference carefully to help ensure that your payment is allocated correctly.

If you cannot pay the full amount immediately, contact HMRC as early as possible to discuss whether a Time to Pay arrangement is available. Explain your financial circumstances and provide any information HMRC requests.

Do not assume that requesting an instalment arrangement automatically changes your disclosure deadline or payment obligations. Confirm the arrangements and any relevant deadlines directly with HMRC.

What Happens After HMRC Receives My Disclosure?

HMRC reviews the disclosure and may ask you or your adviser to explain amounts, estimates or the reason for the original omission.

Its published guidance says that, where HMRC is satisfied that a full disclosure has been made, it will write to accept the offer. This is not a promise of immediate acceptance or an agreed processing time for every case.

Keep the submitted calculation, proof of payment and correspondence in a secure folder. If HMRC asks questions, answer accurately and provide the relevant working papers rather than changing figures without explanation.

Once the earlier years have been dealt with, check what needs reporting through the normal tax return process in future. If HMRC has contacted you already, the correspondence should also be reviewed when deciding how the disclosure should be described.

Ask Felix & Co. to review the documents if you need help responding.

Penalties Under the Let Property Campaign

HMRC may charge penalties when rental income has not been correctly reported or a taxpayer has failed to notify HMRC of a tax liability.

The penalty depends on the applicable legislation, the tax year, the type of failure and the circumstances. HMRC considers factors such as whether the error was careless or deliberate, whether information was concealed and whether the disclosure was prompted by HMRC.

A voluntary disclosure may help reduce the penalty where the relevant conditions are met, but it does not guarantee a particular reduction or eliminate the underlying tax and interest.

How Cooperation Can Affect Penalties

When determining the reduction available for certain penalties, HMRC may consider the quality of your disclosure and your cooperation.

  • Telling: Explain clearly what was wrong and provide a complete account of the missing income.
  • Helping: Answer questions and cooperate with HMRC in checking the relevant figures.
  • Giving access to records: Respond to HMRC’s requests for relevant information and supporting evidence.

The applicable penalty rules and reduction calculations should be checked against the legislation and HMRC guidance relevant to your case.

Penalties for Failure to Notify

A failure-to-notify penalty may apply if you did not tell HMRC about a tax liability when required to do so.

The potential penalty depends on the relevant tax regime, when notification was required, the nature of the behaviour and whether the disclosure was prompted or unprompted.

Non-deliberate failure to notify, timing and penalty position should be checked against the relevant legislation and year.

Other categories, including deliberate and deliberate-and-concealed behaviour, also require a case-specific assessment. Do not rely on a single percentage range without confirming that it applies to the particular tax year and circumstances.

Penalties for Inaccurate Tax Returns

Different rules may apply if you submitted Self Assessment tax returns but omitted rental income or entered incorrect figures.

The outcome depends on whether you took reasonable care, made a careless error or deliberately submitted an inaccurate return. The distinction matters because the applicable penalty rules and potential reductions can differ.

If you discover an error in a previously submitted return, establish which years are affected and whether HMRC has already contacted you. Then determine the appropriate correction and disclosure route.

For a more detailed explanation, read our guide to Let Property Campaign penalties.

What If HMRC Has Already Written to Me About Undeclared Rent?

You may still need to correct the tax position after HMRC contacts you, but you should not assume the disclosure is unprompted.

HMRC looks at the circumstances, including what you had reason to believe it had already discovered. Read the letter carefully and keep its date, any attached certificate and the stated response deadline.

Check what information HMRC is asking for, and do not send a guess simply to meet the date. Compare the years mentioned with your rental records and decide whether you need advice before responding.

Penalty treatment depends on the type of error, the facts and the quality of the disclosure, so a fixed percentage should not be promised.

A complete explanation is still worthwhile even where HMRC has made contact. Felix & Co. can help you work through the letter and supporting records.

Frequently Asked Questions

How does HMRC find out about undeclared rental income?

HMRC can compare information from different sources to identify potential discrepancies between property ownership, rental activity and declared income. Information from property records and third parties may contribute to compliance checks.

A discrepancy does not automatically establish that tax is owed, but it may lead HMRC to request further information or investigate the circumstances.

How far back can HMRC look into undeclared rental income?

The period HMRC can assess depends on the relevant tax legislation, the type of error and the circumstances.

Different time limits may apply where reasonable care was taken, where a loss of tax arose through careless behaviour, or where the loss was deliberate. Longer periods can apply in certain cases involving deliberate behaviour.

Do not assume a single look-back period applies to every Let Property Campaign disclosure. Review the relevant years with reference to the rules applicable to your case.

What happens if I ignore an HMRC nudge letter?

Ignoring HMRC correspondence can make it harder to resolve a potential tax discrepancy and may increase the risk of further compliance action.

Read the letter, establish what HMRC is asking for and respond by the stated deadline where required. If you are unsure how to proceed, seek professional advice before sending an incomplete or inaccurate response.

Does an LPC disclosure need to include other income sources?

The disclosure should follow HMRC’s requirements and cover the liabilities that need to be corrected. If you have other previously undeclared income or gains, you should establish whether these need to be reported through the same or a different disclosure route.

Do not assume that every type of income can automatically be included in a Let Property Campaign disclosure. Check the relevant HMRC guidance for the particular income and circumstances.

Can I pay my tax liability in instalments?

You may be able to arrange a Time to Pay agreement with HMRC if you cannot afford to pay the full liability immediately.

Contact HMRC as early as possible, explain your circumstances and confirm what arrangements are available. Do not assume that an instalment request automatically extends your disclosure deadline or changes your obligations.

Can I use the Let Property Campaign if HMRC has already started investigating me?

You should not assume that the campaign remains available if HMRC has already opened a formal enquiry or compliance check.

The correct route depends on the nature and stage of HMRC’s contact. Review the correspondence and obtain advice if necessary before deciding how to disclose the outstanding liability.

Even where the campaign is not available, correcting the position and cooperating with HMRC may remain important when the applicable penalty rules are considered.

What should I do if I am unsure how to calculate my rental profits?

Start by gathering rental statements, tenancy agreements, expense records, ownership documents and previous tax returns. Organise the information by property and tax year.

Check which costs are allowable, how any property finance costs should be treated and how the rental income should be attributed between co-owners. Professional advice can help identify errors before the disclosure is submitted.

Get Help With Your Let Property Campaign Disclosure

Correcting undeclared rental income can involve several tax years, detailed calculations and decisions about interest, penalties and payment arrangements.

The right approach depends on your rental history, ownership structure, previous tax returns and any correspondence you have received from HMRC.

Felix & Co. can help you review your rental tax position, organise the supporting records and understand the steps involved in making an accurate disclosure.

Ask Felix & Co. to review your rental tax position before submitting your disclosure.

LPC Disclosure Guide: Step-by-Step HMRC Process  Book Your Comprehensive Property Tax Review
Categories
Articles Blogs FAQs Guides News

The Best Expert Guide to UK Landlord Tax Deductions in 2026

Understanding UK landlord tax deductions 2026

You must understand UK landlord tax deductions to make the most profit from your rental property. It also helps you avoid paying more tax than necessary in 2026. Therefore, knowing what costs you can legally claim keeps you compliant with HMRC while improving your property tax efficiency.

What are allowable UK landlord tax deductions?

UK property tax efficiency

A cost must be wholly and exclusively for your rental property business to qualify as an allowable expense. These deductions reduce your taxable rental profit and can help landlords manage their tax responsibilities more effectively.

Common UK landlord tax deductions include property safety checks such as gas certificates, EICRs, and fire alarm inspections. Landlords can also claim property management costs, including letting agent fees, tenant referencing, inventory checks, and advertising costs.

Additionally, professional costs such as accounting services and certain legal fees may be deductible. Insurance costs, including landlord insurance, buildings insurance, and liability cover, can also qualify. Travel expenses related to managing the rental property, repairs, or inspections may be allowed if they meet HMRC rules.

Repairs vs Improvements: UK landlord tax deductions

Understanding the difference between repairs and improvements is important because they receive different tax treatment.

Repairs restore a property to its original condition and are normally deductible. Examples include repairing a leaking roof, fixing broken windows, replacing damaged flooring, or repairing an existing boiler.

However, improvements add value or upgrade the property beyond its original state. Examples include building an extension, adding a loft conversion, or installing a luxury kitchen. These costs are usually not deducted from rental income, but keeping records is important because they may help reduce your Capital Gains Tax when selling the property.

How to document expenses for HMRC

HMRC compliance

Keeping accurate records is essential for every landlord. Digital record keeping makes it easier to track expenses and prepare your tax return.

Landlords should keep invoices, receipts, bank statements, and digital copies of expenses. Using accounting software or a receipt management app can prevent missing important deductions. Separating rental income and expenses through a dedicated bank account can also make tax reporting easier.

Good record keeping also helps landlords prepare for changes such as Making Tax Digital (MTD) requirements and ensures evidence is available if HMRC requests supporting documents.

Common grey area deductions

Some landlord expenses are not always straightforward. Many landlords ask whether they can claim administrative costs, home office expenses, or professional membership fees.

Some costs may qualify if they are directly connected to running the rental property business. For example, certain legal costs, property management expenses, and professional advice fees may be allowable. Always check that expenses meet HMRC requirements before claiming them.

Frequently Asked Questions About UK Landlord Tax Deductions 2026

1. What tax deductions can UK landlords claim in 2026?

UK landlords can claim allowable expenses that are directly related to renting out their property. These may include repairs, insurance, letting agent fees, property management costs, accountant fees, safety certificates, and other necessary rental business expenses.

2. Can landlords claim mortgage payments as a tax deduction?

No. Individual landlords cannot normally deduct the full mortgage payment from rental income. However, mortgage interest may qualify for tax relief through the finance cost restriction rules.

3. Are property repairs tax deductible for landlords?

Yes. Repairs that maintain the property and return it to its original condition are usually allowable deductions. Examples include fixing leaks, repairing damage, replacing broken parts, and maintaining existing facilities.

4. What is the difference between repairs and improvements?

Repairs maintain the existing property, while improvements add value or create something new. Repairs are usually deducted from rental income, but improvements are generally treated as capital expenses and may only provide relief when calculating Capital Gains Tax.

5. Can landlords claim letting agent fees?

Yes. Fees paid to letting agents for finding tenants, managing properties, collecting rent, or carrying out tenant checks are normally allowable UK landlord tax deductions.

6. Can landlords claim insurance costs?

Yes. Landlord insurance, buildings insurance, and certain liability insurance costs connected with renting out a property can usually be claimed as allowable expenses.

7. Do landlords need receipts for tax deductions?

Yes. Landlords should keep receipts, invoices, bank statements, and digital records for all claimed expenses. Proper documentation helps support your claims if HMRC requests evidence.

8. Can landlords claim expenses when a property is empty?

Some expenses during an empty period may still qualify if they are necessary for preparing or maintaining the property for rental. The expense must still meet HMRC’s rules for allowable deductions.

9. Can landlords claim accountant fees?

Yes. Professional fees for preparing tax returns, managing rental accounts, and receiving property tax advice can usually be claimed as allowable expenses.

10. How can landlords reduce tax legally in the UK?

Landlords can reduce tax legally by claiming all eligible expenses, keeping accurate records, understanding available tax reliefs, and getting professional advice to structure their property investments efficiently.

Need Help With Your UK Landlord Tax?

Managing rental property taxes can be complicated. Missing allowable deductions could mean paying more tax than necessary. Contact Felix & Co. Accountants for professional property tax advice and support with your 2026 tax return.

Understanding UK landlord tax deductions 2026 helps property owners maximise their rental profits while staying compliant with HMRC rules. From repairs and insurance to professional fees and property management costs, claiming the correct expenses can significantly reduce your taxable rental income.

Landlords should keep detailed records, understand the difference between repairs and improvements, and seek professional advice when unsure. With proper tax planning, landlords can make better financial decisions and manage their property investments more effectively.

Understanding UK landlord tax deductions 2026  Book Your Comprehensive Property Tax Review

Categories
Articles FAQs Guides

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Small businesses can write off the entire purchase price of qualifying equipment, software, and vehicles in the exact tax year they put those assets to work. This Section 179 tax code provision represents a significant opportunity to save cash and lower business overhead. Instead of writing off a fraction of a computer or truck purchase over a five-year recovery schedule, you can deduct the full amount immediately.

The rules shifted favorably recently. Thanks to the One Big Beautiful Bill Act (OBBBA), the deduction ceiling grew substantially. For the 2026 tax year, you can claim up to $2,560,000 in immediate write-offs.

Section 179 tax Deduction Basics

Most business assets lose value over time. Usually, you must spread your deduction for that loss over several years. Section 179 changes this standard system. It lets you accelerate the write-off process by claiming the entire depreciation expense in year one.

To use this tax break, you must meet key timing requirements. You must buy or lease the asset and place it into service by midnight on December 31 of the tax year. “Placed in service” means the equipment is fully functional and ready for its intended business use. Merely purchasing the item or leaving it in its box does not count.

The deduction is subject to a dollar-for-dollar phase-out. For 2026, the spending threshold begins at $4,090,000.If your company spends more than that on qualifying business property, your maximum allowed deduction decreases by the excess amount. Once your capital equipment spending hits $6,650,000, your deduction drops to zero.

How to Calculate Your Section 179 tax Write-Off

Calculating your savings requires three numbers. You need your total equipment purchase cost, your business use percentage, and your tax rate.

If you use an asset for both personal and business purposes, you must prorate the deduction. The asset must serve your business more than 50% of the time to qualify at all. For example, suppose you purchase a $10,000 heavy-duty printer. You use it 80% for client work and 20% for personal printing. Your qualifying cost basis becomes $8,000.

Here is a straightforward calculation for a business using 100% business-use equipment:

Calculation StepExample Values
Total Equipment Cost$150,000
Section 179 Deduction$150,000
Estimated Tax Rate35%
Direct Tax Cash Savings$52,500
Net Cost of Equipment$97,500

If your total purchases exceed the $4,090,000 threshold, apply this formula:

Deduction Limit=$2,560,000−(Total Purchases−$4,090,000)

For example, if you buy $4,500,000 in equipment, your excess spending is $410,000. Your modified deduction ceiling drops to $2,150,000.

Section Section 179 tax

Qualifying Property Under Section 179 tax Rules

The IRS limits this deduction to specific asset types. Most tangible personal property used in your business qualifies.

The primary categories include:

  • Office furniture like desks, chairs, and conference tables.
  • Computers, servers, laptops, and networking hardware.
  • Off-the-shelf software available to the general public with a non-exclusive license.
  • Manufacturing machinery, printing presses, and specialized tools.
  • Qualified Improvement Property (QIP) including interior renovations to commercial buildings.
  • Building security systems, fire alarms, HVAC units, and commercial roofing.

Both new and used equipment qualify for the write-off. The used equipment must be new to your business. You cannot purchase used gear from a related family member or business entity to claim the write-off.

Vehicle Rules and Weight Limits

Vehicles face stricter standards due to historical abuse of the tax code. The IRS categorizes vehicles by Gross Vehicle Weight Rating (GVWR). You can find this rating on the manufacturer label inside the driver side door jamb.

Passenger cars and light trucks under 6,000 lbs GVWR have a low caps limit. For 2026, these light vehicles are subject to a maximum first-year depreciation limit of $20,300.

Heavy SUVs, pickup trucks, and cargo vans with a GVWR between 6,001 and 14,000 lbs qualify for a higher threshold. In 2026, the maximum Section 179 deduction for these heavy SUVs is capped at $32,000.Large commercial vehicles exceeding 14,000 lbs GVWR escape passenger limits entirely. Delivery trucks, box trucks, buses, and heavy construction equipment qualify for the full Section 179 write-off up to the $2,560,000 cap.

Section 179 tax vs Bonus Depreciation

Bonus depreciation is another accelerated tax incentive, but it operates under different rules. Under the current 2026 rules, 100% bonus depreciation is available for qualified property.

Unlike Section 179, bonus depreciation does not cap your total deduction amount. It does not decrease based on your total capital purchases during the year.

Another major difference involves business income. You cannot use Section 179 to create a net business loss. Your Section 179 deduction is limited to your net taxable business income. Bonus depreciation has no such limit. You can use it to create or increase a Net Operating Loss (NOL), which you can carry forward to offset future profits.

The standard approach is to apply Section 179 first to maximize deductions on specific assets. You then apply 100% bonus depreciation to any remaining asset basis.

How to Claim the Deduction on Your Taxes

To claim this tax break, you must file IRS Form 4562 with your annual tax return. You will list the qualifying assets, their total cost, and the specific deduction amount you elect to expense.

Keep meticulous records for each purchase. Save the original invoices, receipts, and purchase contracts. Document the exact date you placed the equipment in service. If the asset has split business and personal use, maintain a log to prove your business use percentage exceeds the 50% threshold.

Section Section 179 tax

Frequently Asked Questions

Who qualifies for Section 179 tax?

All active businesses that purchase, finance, or lease qualifying new or used equipment during the tax year qualify for this write-off. You must use the acquired property for business operations more than 50% of the time to lock in your eligibility. Meeting these criteria lets you claim the Section 179 tax deduction to lower your tax liability.

What are the Section 179 limits for 2026?

For the 2026 tax year, the maximum Section 179 tax deduction limit is $2,560,000. This limit begins to phase out dollar-for-dollar when your total qualifying equipment purchases exceed $4,090,000. Once your annual equipment spending reaches $6,650,000, the deduction is completely unavailable.

Can used equipment qualify for Section 179?

Yes, used equipment qualifies for the write-off as long as it is new to your business. You cannot buy the used assets from a related business or family member. The Section 179 tax provisions treat qualifying used machinery, furniture, and tools exactly like brand-new hardware.

What is the difference between Section 179 and bonus depreciation?

The Section 179 tax deduction cannot exceed your active business taxable income, meaning it cannot create a net loss. It is capped at $2,560,000. Conversely, 100% bonus depreciation is uncapped and can create a net operating loss to offset taxes in other years.

Does a vehicle qualify for Section 179?

Yes, vehicles qualify for this write-off, but the IRS applies strict weight limits. Light passenger cars under 6,000 lbs have low caps. Heavy work trucks, cargo vans, and specialized passenger vehicles over 6,000 lbs GVWR are eligible to receive the full Section 179 tax write-off.

How do you calculate a Section 179 deduction?

Multiply the total cost of your qualified equipment by your business-use percentage to find your depreciable basis. If your total annual spending is under $4,090,000, you can write off the entire basis up to $2,560,000 using the Section 179 tax code.

What is the maximum Section 179 deduction for an SUV?

For heavy passenger SUVs with a GVWR between 6,001 and 14,000 lbs, the maximum first-year Section 179 tax write-off is limited to $32,000 in 2026. You can depreciate any remaining value using bonus or standard MACRS schedules.

Can Section Section 179 tax create a net operating loss?

No, the Section 179 tax deduction cannot exceed your net business taxable income. If your business operates at a loss before the deduction, you cannot claim it to create a net operating loss. Any disallowed portion carries forward to the next tax year.

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Book Your Comprehensive Property Tax Review

Categories
Articles Blogs Guides

HMRC Watchlist for Landlords: What the Term Really Means

Finding your business placed on an HMRC watchlist The term “HMRC watchlist for landlords” is sometimes used online, but it is not a single published list covering everyone HMRC may review. A routine query about rental income is different from formal monitoring under HMRC’s Managing Serious Defaulters programme. This article explains the distinction and the sensible steps landlords can take.

If you suspect you are under investigation, you must act quickly. Ignoring the warning signs only increases your exposure to back taxes, interest, and criminal prosecution.

Understanding the HMRC Watchlist Programs

The tax authority uses two primary monitoring systems to track high-risk taxpayers. While many people refer to these collectively as a watchlist, they operate under different legal frameworks.

The Managing Serious Defaulters Programme

HMRC’s Managing Serious Defaulters programme concerns people or businesses that meet specific serious-default criteria, including certain deliberate tax behaviour. It is not the same as receiving an ordinary landlord information request.

HMRC says monitoring under this programme depends on the case. It may include checking returns and payments, reviewing records and carrying out compliance checks. Some visits may be announced or unannounced. Additional return information is required only in specified circumstances.

The Publishing Details of Deliberate Defaulters List

HMRC may publish details of some people who receive qualifying penalties for deliberate tax defaults. Publication depends on the law and facts, including relevant thresholds and the finality of penalties. Do not treat every landlord enquiry or late disclosure as a publication case.

How to Handle an HMRC Watchlist Investigation

If you are placed on a monitoring list, you must take immediate steps to protect your assets. The following workflow shows how to systematically address an active enquiry.

1.   Appoint a Specialist Tax Representative: Immediate.

HMRC may publish details of some people who receive qualifying penalties for deliberate tax defaults. Publication depends on the law and facts, including relevant thresholds and the finality of penalties. Do not treat every landlord enquiry or late disclosure as a publication case.

2.   Conduct a Voluntary Internal Audit: Within 14 Days.

Review your financial records for the last six years. Identify any discrepancies in your VAT, PAYE, or Corporate Tax returns before investigators point them out.

3.  Submit an Unprompted Disclosure: Before Findings Finalise.

If you find an error, consider how to correct it promptly. Whether a disclosure is prompted or unprompted depends on the circumstances and prior HMRC contact.

4.   Implement Strict Compliance Systems: Ongoing.

Install digital accounting software that complies with Making Tax Digital (MTD) rules. Keep perfect transaction records and submit all future returns ahead of schedule.

Key Differences in HMRC watchlist Monitoring Regimes

The table below outlines the operational differences between standard tax compliance checks and active watchlist monitoring.

FeatureStandard Compliance CheckActive Watchlist Monitoring
Public DisclosureNonePublic name-and-shame for deliberate defaults over £25k
Duration of TrackingEnds when the check closesTypically 2 to 5 years under the MSD program
Inspection FrequencyPre-arranged visitsUnannounced spot checks of premises
Record RequirementsStandard statutory booksFull, non-simplified returns with detailed ledgers
Average Penalty Range0% to 30% of tax owed35% to 100% (or up to 200% for offshore issues)

Avoiding Common Triggers for Special Monitoring

HMRC has published data-gathering powers, including obtaining certain third-party information for compliance purposes. The exact reason for a particular enquiry may not be known. Avoid assuming that specific spending patterns or software automatically trigger a landlord investigation.

To keep your business off their radar, avoid these common red flags:

  • Consistently filing returns late or making frequent retroactive amendments.
  • Showing lifestyle assets or property purchases that do not align with your declared personal income.
  • Declaring zero profits or claiming continuous tax losses for multiple consecutive years.
  • Failing to reconcile your digital payment processor receipts with your bank deposits.

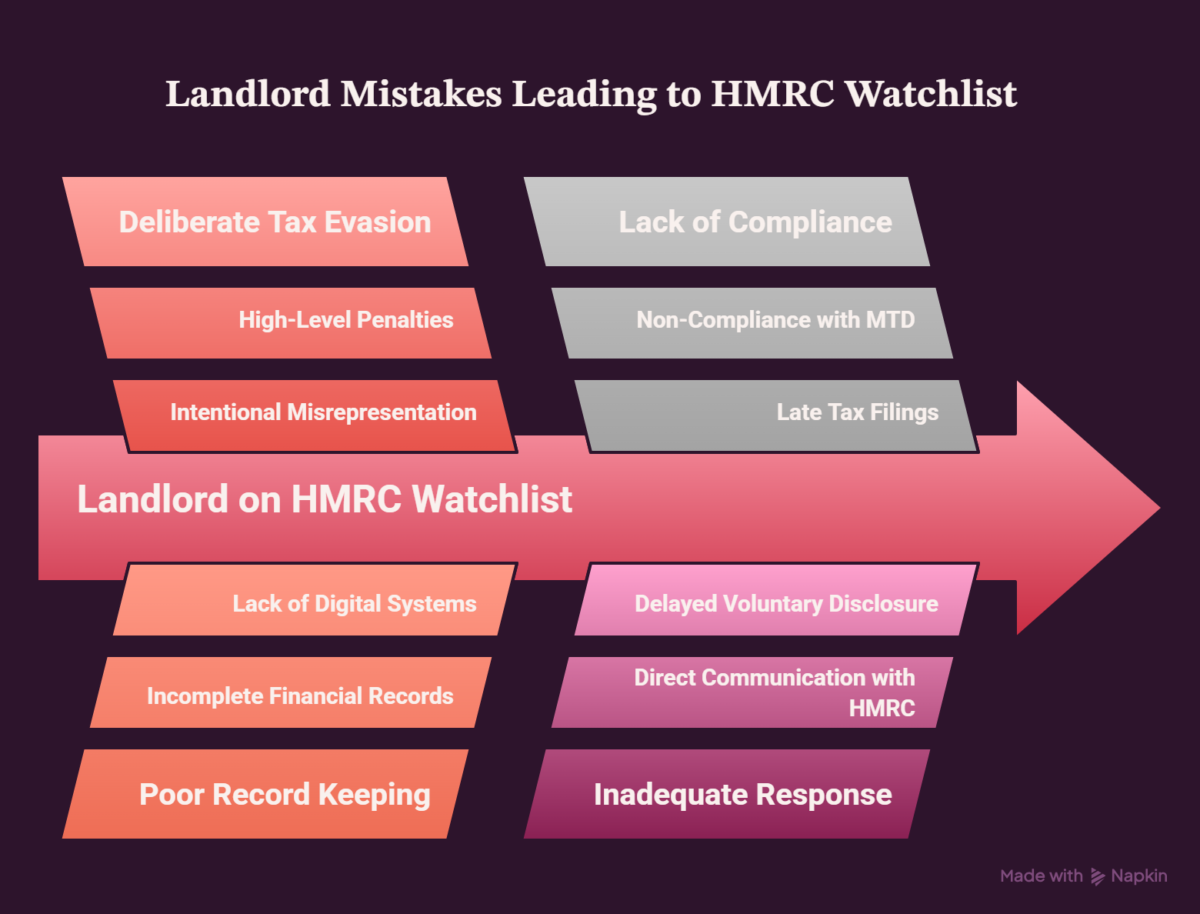
    Mistakes Landlords Make That Can Land Them on HMRC's Watchlist
    HMRC’s Watchlist

Frequently Asked Questions

How do you know if HMRC watchlist are investigating you?

HMRC will formally notify you by sending an opening enquiry letter in the post. This letter specifies the tax years and returns under review. It also requests detailed financial documentation to support your filings. You will not receive prior warning before this official notification arrives.

How far back can HMRC go in an audit?

If you made an honest mistake, HMRC can review your records up to four years back. For careless errors, the limit extends to six years. However, if they suspect deliberate tax fraud or evasion, they can audit your accounts up to 20 years back.

What triggers an HMRC tax investigation?

An investigation is usually triggered by anomalies flagged by HMRC’s Connect data-matching software. Common triggers include declaring sudden drops in income, reporting continuous business losses, and omitting offshore assets. Discrepancies between your VAT submissions and bank accounts also draw attention.

Can you stop an HMRC compliance check?

You cannot legally block an active HMRC compliance check once it starts. However, you can apply for Alternative Dispute Resolution (ADR) if you disagree with their methodology. You can also appeal formal information notices if the requested data is irrelevant to the tax period.

What is the penalty for deliberate tax evasion in the UK?

Penalties for deliberate tax evasion range from 35% to 100% of the unpaid tax liability. If the evasion involves offshore assets, the fine can reach 200%. Furthermore, the tax authority can initiate criminal prosecutions leading to prison sentences.

How long does a serious tax investigation take?

A standard aspect check often concludes within three to six months. In contrast, a serious fraud or deliberate evasion investigation can last between one and three years. The duration depends on the complexity of your accounts and how cooperatively you provide the requested records.

Who gets put on the HMRC watchlist deliberate defaulters list?

HMRC publishes details of some deliberate tax defaulters who satisfy specific statutory conditions. An ordinary error, a nudge letter or a compliance enquiry does not automatically place a landlord on that list.

Is there an official HMRC watchlist for ordinary landlords?

There is no single published HMRC list that confirms which ordinary landlords are being checked for rental income. The term ‘watchlist’ is often used informally and can be misleading. HMRC does operate named programmes for some serious defaults, including the Managing Serious Defaulters programme. That is a different matter from a request asking you to check your rental tax return.

If you receive correspondence, focus on what the letter actually says: does it ask for information, identify a compliance check or explain inclusion in a specific programme? Keep a copy and respond using the instructions applicable to that letter. If you are worried about undisclosed rent, check the relevant years and property records before assuming a particular enforcement outcome.

What happens during an HMRC watchlist fraud investigation?

Investigators will examine your financial statements, bank records, and physical assets with extreme scrutiny. They may conduct unannounced site visits, interview you under caution, or secure search warrants. The process ends with either a formal tax settlement or criminal prosecution.

Mistakes Landlords Make That Can Land Them on HMRC’s WatchlistBook Your Comprehensive Property Tax Review


Categories
Blogs FAQs Guides

Common Tax Mistakes That Cost Small Businesses Money

When you run a company, managing your business tax obligations is often the most stressful part of the job, a single missed deduction or late filing can result in steep IRS penalties. Fortunately, most of these issues are entirely preventable. Let us look at where founders slip up and how you can keep more money in your pocket.

1. Mixing Personal and Business Accounts

Co-mingling your funds is the fastest way to trigger an IRS audit. If you buy groceries with your company credit card, you cloud your financial tracking.

Keep your accounts completely separate. Open a dedicated business checking account on day one. Pay for your software, inventory, and office supplies exclusively from this account. Doing so makes it incredibly simple to track write-offs and proves your business legitimacy to the IRS.

2. Missing Out on Valid Deductions

Many founders fail to claim legitimate write-offs. They leave money on the table out of fear of audits. If you use part of your home strictly for work, you can claim the home office deduction.

Keep a detailed log of your vehicle mileage. Save every receipt for meals with clients. Use accounting software to scan and categorize bills automatically. Over a year, these small deductions add up to thousands of dollars in business tax savings.

3. Misclassifying Your Workers

The IRS heavily polices the line between independent contractors and employees. If you control when, where, and how a worker performs their tasks, they are likely an employee.

Misclassifying a worker on a Form 1099 instead of a Form W-2 can cost you. You could face back taxes for FICA, federal unemployment taxes, and steep penalties. Review the IRS common law rules to ensure you classify your team members correctly.

How Business Tax Oversight Compares

The table below breaks down the financial impact of three frequent mistakes.

MistakeTypical Direct CostSimple Fix
Co-mingling FundsHigh audit risk, lost deduction trackingOpen a dedicated business account
Worker MisclassificationThousands in unpaid payroll taxes & finesUse IRS Form SS-8 for determination
Missing Mileage Tracking$0.67 per mile lost (IRS standard rate)Use an automatic mileage tracking app

4. Forgetting Estimated Quarterly Taxes

The US tax system operates on a pay-as-you-go model. If you expect to owe more than $1,000 when you file your annual return, you must make quarterly payments.

Missing these deadlines leads to underpayment penalties. Set aside 25% to 30% of your net income each month in a separate savings account. Pay your estimated installments by April 15, June 15, September 15, and January 15.

5. Filing Your Taxes Late

Procrastinating on your tax return is expensive. The failure-to-file penalty is 5% of your unpaid taxes per month. This fee is ten times higher than the failure-to-pay penalty of 0.5%.

Even if you do not have the money to pay your bill, you must file your return on time. Alternatively, file Form 7004 or Form 4868 to request an automatic six-month extension. This simple step eliminates the harsh late-filing fees.

businesses tax
businesses tax

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture makes an error, the IRS sends a notice detailing the discrepancy. You may face penalties and interest on unpaid balances. Correcting the issue quickly minimizes financial damage. Working with a CPA helps resolve these issues.

Can you write off small business expenses without revenue?

Yes. You can write off startup costs up to $5,000 in your first active year. If your business has not launched yet, these costs are capitalized. They are then amortized over 15 years instead of being deducted immediately.

What is the most common businesses tax write-off for small businesses?

The most common deduction is ordinary and necessary operating expenses. This category includes rent, utilities, software subscriptions, advertising, and professional fees. Tracking these items continuously ensures you lower your overall business tax burden during filing season.

Do small businesses get audited often?

Small businesses face relatively low audit rates, usually under 1%. However, high-risk behaviors increase your chances of a review. These triggers include reporting consistent net losses, mixing personal expenses, and failing to report 1099 payments.

Is it better to file small business taxes as an LLC or S-Corp?

It depends on your net income. An LLC is simple and avoids double taxation. However, an S-Corp can reduce self-employment taxes once your business generates significant revenue. Consult a professional to see which structure fits your growth.

How much can a business write off without receipts?

The IRS generally requires receipts for any business expense over $75. However, you still need to document the time, place, and business purpose. Keeping digital copies of all receipts is the safest way to defend your deductions.

What happens if you do not pay estimated quarterly taxes?

If you skip quarterly payments, the IRS charges an underpayment penalty. The fee is calculated based on how much you owed and how late you paid. You can easily avoid this by making timely, estimated payments.

Can you deduct personal cell phone use for business?

Yes, you can deduct the business portion of your personal phone bill. You must calculate the exact percentage of time you use the device for work. Keep itemized phone bills to prove this split during an audit.

Learn More


Categories
Articles Blogs FAQs Guides

UK Stamp Duty Guide 2026

Understanding Stamp Duty UK 2026 is essential before buying a home or investment property. Whether you’re a first-time buyer, homeowner, landlord, or investor, knowing how Stamp Duty Land Tax (SDLT) works can help you avoid unnecessary costs and stay compliant with UK property purchase tax rules.

Everything you need to know about Stamp Duty UK 2026:

What Is Stamp Duty Land Tax (SDLT)?

Stamp Duty Land Tax (SDLT) is a tax paid when purchasing residential or commercial property in England and Northern Ireland above the applicable threshold. The amount you pay depends on the property’s value, your buyer status, and whether you’re purchasing an additional property.

For a complete explanation of UK property taxes, read our Property Tax Guide.

How Much Stamp Duty Will I Pay in 2026?

Your Stamp Duty bill depends on the property’s purchase price, whether you’re a first-time buyer, and if you’re buying an additional property. Current SDLT rates and reliefs should always be checked before completing your purchase.

You can also learn how to legally reduce your SDLT bill by reading our How to Reduce Stamp Duty Legally guide.

Who Is Exempt From Paying Stamp Duty?

Some buyers may qualify for exemptions or reliefs, including eligible first-time buyers and certain property transfers. Always confirm your eligibility before claiming any relief.

Do First-Time Buyers Pay Stamp Duty?

Many first-time buyers qualify for Stamp Duty relief, helping reduce the amount of tax payable on qualifying property purchases.

How Is Stamp Duty Calculated?

Stamp Duty is calculated based on the property’s purchase price, current SDLT tax bands, buyer status, and whether additional property surcharges apply.

If you’re buying property as an investment, our Property Investor Tax Strategy Guide can help you plan ahead.

When Do I Have to Pay Stamp Duty?

Stamp Duty is normally due shortly after completing your property purchase. Missing the deadline may result in penalties and interest.

Can I Reduce My Stamp Duty Bill Legally?

Yes. There are legitimate Stamp Duty reliefs and exemptions available depending on your circumstances. Professional tax advice can help ensure you only pay what you legally owe.

What Happens If I Pay Stamp Duty Late?

Late payment can lead to HMRC penalties, interest charges, and unnecessary delays. Paying on time helps you avoid additional costs.suspects-fraud-cop9

Official HMRC Guidance

For the latest Stamp Duty Land Tax rates and official government guidance, visit the HMRC Stamp Duty Land Tax page.

HMRC compliance
HMRC compliance

You can also check the latest residential Stamp Duty rates on the UK Government SDLT Rates page.


Need expert advice on Stamp Duty UK 2026?
Contact Felix & Co Chartered Tax for professional guidance on Stamp Duty Land Tax, property purchase tax, and all UK property tax matters.

Book a Free Consultation

Categories
News

How UK Property Accountants Reduced a £9,000+ HMRC Penalty to Nil

A landlord in Berkshire opened a letter from HMRC and saw a penalty demand for more than £9,000. Nine months later, that figure was zero. Nothing about the tax owed had changed. What changed was how the disclosure was handled, and that’s the part most people get wrong.

This is a walkthrough of that case, anonymised for client confidentiality, and what it shows about how HMRC actually calculates and reduces penalties for undeclared rental income.

How the Penalty Reached Over £9,000 in the First Place

The client owned two rental properties in Reading, bought them in 2019 and 2021, and had never registered for Self Assessment on the rental income. This wasn’t tax evasion in any deliberate sense. He’d moved from an employed role into buy-to-let almost by accident, inherited one property, remortgaged to buy the second, and assumed his letting agent or his old employer’s payroll department was somehow “sorting the tax.” Neither was.

HMRC caught up with him through its Connect system, which cross-references Land Registry data, mortgage records, and letting agent reports against Self Assessment filings. He received what’s commonly called a nudge letter, a prompt asking him to check his tax position and come forward voluntarily. Ignoring it, or responding badly, is what usually turns a manageable situation into an expensive one. We’ve written before about what to do when an HMRC nudge letter arrives, and the short version is: don’t wait.

By the time he came to us, roughly £30,000 of rental income across four tax years had gone undeclared. The tax owed on that was significant on its own. But it was the penalty, calculated as a percentage of what HMRC calls the “potential lost revenue,” that pushed the total demand past £9,000.

Why the Penalty Was Calculated the Way It Was

Failure to notify HMRC of taxable income falls into three categories: non-deliberate, deliberate, and deliberate with concealment. Almost every landlord case we see is non-deliberate; people genuinely didn’t realise letting income needed reporting, or believed a small profit margin meant nothing was owed.

For a non-deliberate failure to notify, disclosed more than 12 months after the tax was due, the penalty range runs from 20% to 30% of the potential lost revenue if HMRC prompts the disclosure. Get there first, unprompted, and the range drops to 10% to 20%, sometimes lower. That gap between prompted and unprompted is the single biggest lever available, and it’s one reason speed matters more than most people assume. We break the distinction down properly on our prompted vs unprompted disclosure page.

Why This Situation Is So Common Among Landlords

Most people picture tax evasion as something calculated. In practice, the overwhelming majority of landlord disclosures we handle look nothing like that. A few patterns come up again and again:

  • Someone inherits a property, keeps renting it out, and never thinks of themselves as running a rental “business.”
  • A homeowner relocates for work, lets their old house rather than sell it, and treats the rent as background income rather than something requiring a tax return.
  • An accidental landlord assumes that because the mortgage swallows most of the rent, there’s no profit and therefore nothing to declare, which isn’t how HMRC calculates taxable profit.
  • A property investor with several units loses track of which ones are actually registered for Self Assessment as their portfolio grows.

If any of that sounds familiar, it’s worth reading our guide on accidental landlord tax obligations before HMRC gets in touch first.

The Strategy That Brought the Penalty Down to Nil

Getting from a £9,000+ demand to a nil penalty involved three separate arguments, run in parallel rather than as a single request for leniency.

Registering Through the Let Property Campaign

The Let Property Campaign is HMRC’s disclosure route specifically for landlords with undeclared rental income. It’s not an amnesty and it doesn’t erase the tax owed, but it structures the process in a way that lets a taxpayer demonstrate cooperation from the outset, which matters enormously when penalties are calculated. Because the client had already received a nudge letter, his disclosure was classed as prompted rather than unprompted, which meant the starting penalty range was higher than it would otherwise have been. Our Let Property Campaign guide covers how registration works and what HMRC expects at each stage.

Building the Quality of Disclosure

Within the penalty calculation, HMRC allows a reduction based on three factors: telling, helping, and giving. Telling covers how much the taxpayer volunteers unprompted, before HMRC has to ask. Helping covers the level of cooperation during the process, answering questions promptly, providing records without repeated requests. Giving covers access to documents and figures, including bank statements, mortgage certificates, and letting agent statements.

Combined, these three factors can reduce a penalty by up to 70% even where the disclosure itself was prompted. We prepared a complete, well-organised disclosure package before HMRC asked for a single follow-up document, which is the part most self-filed disclosures miss. People often register for the Let Property Campaign and then respond to HMRC’s questions reactively, one letter at a time, which reads to HMRC as reluctant cooperation rather than genuine transparency.

Arguing Special Circumstances

HMRC has the power to reduce a penalty, or not charge it at all, where it considers this right because of special circumstances. This isn’t the same as a reasonable excuse defence, which applies to the underlying failure itself; special reduction applies to the penalty specifically, and HMRC has discretion over when to use it.

In this case, we presented evidence of the client’s genuine and reasonable belief that his letting agent was managing tax reporting, alongside a clean compliance history and full, proactive cooperation once the nudge letter arrived. None of that erased the tax liability. What it did was give HMRC grounds to apply special reduction on top of the quality-of-disclosure reduction already secured.

Penalty typeStandard rangeReduction applied in this case
Non-deliberate, prompted disclosure, over 12 months late20%–30% of tax owedQuality of disclosure reduction (telling, helping, giving)
Reduced rate after quality-of-disclosure reductionAs low as 10% of the reduced rangeSpecial reduction applied on top
Final penalty£9,000+ as originally issued£0

The tax due on the £30,000 of previously undeclared income was still paid in full, along with interest for late payment. That part doesn’t disappear, and no legitimate accountant will tell a client otherwise. What disappeared was the penalty sitting on top of it.

What This Case Actually Teaches Other Landlords

A few things stand out from working through cases like this one:

  • Speed changes the penalty band. A voluntary, unprompted disclosure starts from a lower base than one triggered by a nudge letter, and a nudge letter starts from a lower base than a formal HMRC enquiry.
  • The quality of the disclosure package matters as much as the disclosure itself. HMRC assesses cooperation, not just honesty.
  • Special reduction is discretionary, not automatic. HMRC won’t apply it unless the case for it is made clearly, with evidence.
  • None of this reduces the tax owed. It reduces the penalty sitting on top of the tax owed, which is a different thing entirely.

If you want a rough sense of what a penalty might look like before you speak to anyone, our penalty calculator gives a starting estimate, though the real figure depends heavily on the disclosure route and quality factors described above.

Avoiding This Situation Before HMRC Gets Involved

The cheapest way to deal with an HMRC penalty is to never trigger one. For landlords who suspect they might have gaps in their rental income reporting, whether from a single let property or a growing portfolio, a few practical steps matter more than people expect.

Get Ahead of a Nudge Letter

If you haven’t received one yet but suspect your position isn’t fully compliant, an unprompted disclosure through the Let Property Campaign is almost always cheaper than waiting. Once a letter arrives, the disclosure is classed as prompted and the penalty range moves against you.

Keep Records HMRC Would Recognise

Bank statements showing rent received, mortgage interest certificates, and invoices for allowable expenses all matter when calculating potential lost revenue accurately, rather than HMRC estimating a figure in your absence. Our guide to allowable expenses for property investors is worth reading even if you’re not currently under review, since it affects how much profit is actually taxable in the first place.

Understand Your Local HMRC Activity

HMRC compliance activity around the Let Property Campaign isn’t evenly spread across the country. We work regularly with landlords facing enquiries in Reading, Windsor, Oxford, London, and Slough, and the pattern of nudge letters we see in each area gives us a reasonably clear picture of where HMRC is currently focusing attention.

Frequently Asked Questions

Can HMRC reduce or cancel a penalty entirely?

Yes. HMRC can apply what’s called special reduction where it considers this right because of special circumstances, and this can apply on top of standard reductions for quality of disclosure. It’s discretionary rather than guaranteed, which is why the way a case is presented matters.

What’s the difference between a prompted and unprompted disclosure?

An unprompted disclosure means you told HMRC before they had any reason to suspect an issue. A prompted disclosure, such as one made after a nudge letter, starts from a higher penalty range because HMRC had already identified you as a possible risk before you came forward.

What counts as a reasonable excuse for not notifying HMRC?

HMRC recognises things like serious illness, a genuine misunderstanding of a legal obligation, or events like fire, flood or theft that prevented compliance. A vague belief that “someone else was handling it,” on its own, rarely qualifies as a reasonable excuse, though it can support an argument for special reduction if backed by evidence.

What happens if I ignore an HMRC penalty notice?

Interest continues to accrue and HMRC can escalate to enforcement action, including debt recovery. You generally have 30 days from the date of the penalty notice to appeal or challenge it, and missing that window makes the process considerably harder.

Do I need a specialist accountant for a Let Property Campaign disclosure?

You can register and disclose without one, but the penalty calculation depends heavily on how the disclosure is presented, not just what’s disclosed. An accountant experienced with HMRC’s quality-of-disclosure factors and special reduction criteria can materially change the outcome, as this case shows.

How much rental income can trigger an HMRC investigation?

There’s no fixed threshold. HMRC’s Connect system cross-references property records, mortgage data, and letting agent reports against tax filings, so even modest undeclared rental profit can surface. The safer approach is registering for Self Assessment as soon as letting income begins, regardless of the amount.

Every case is different, and penalty outcomes depend on individual circumstances, evidence, and how a disclosure is handled from the first letter onward.

Felix & Co. work with landlords and property investors across Slough, Reading, Windsor, London and Oxford on exactly this kind of disclosure.

Book a Free Consultation Call
Categories
Articles Articles Blogs Guides

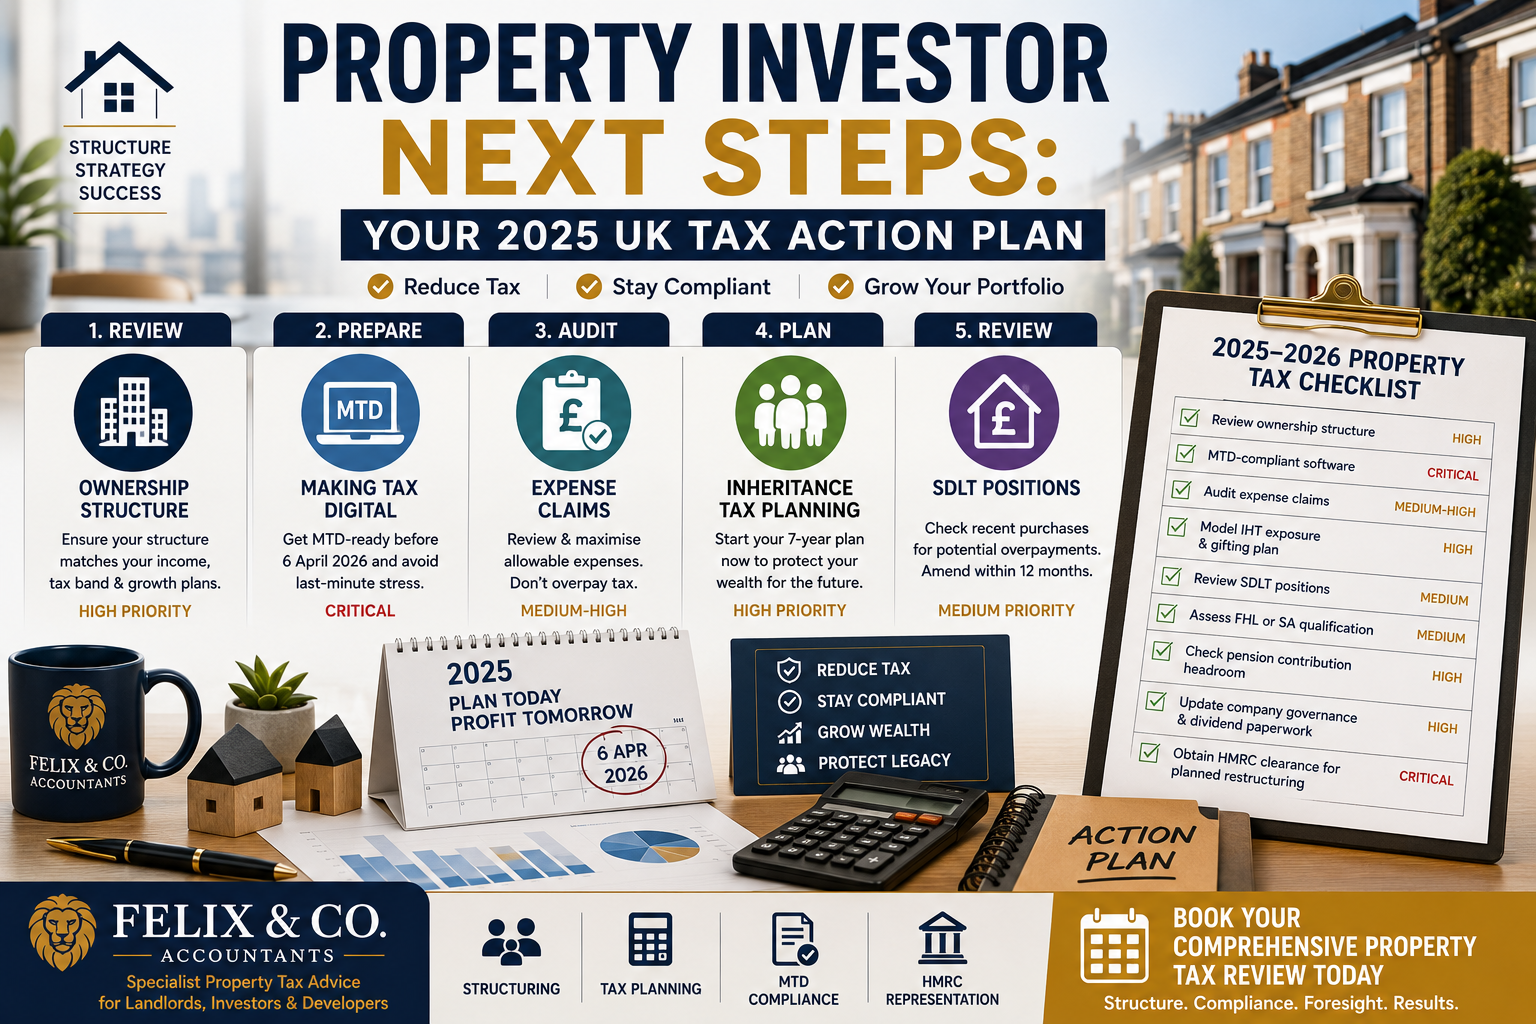
Property Investor Next Steps: Your 2025 UK Tax Action Plan

As a property investor, understanding tax rules is only the first step. The real value comes from turning that knowledge into practical action. Throughout this series, we’ve explored ownership structures, allowable expenses, SDLT planning, inheritance tax, company structures, and compliance obligations. This final guide provides a clear and prioritised property investor tax strategy for 2025, helping you protect profits, reduce tax liabilities, and prepare for future growth.

property investor

The Core Principle Every Property Investor Should Follow
Tax efficiency in property is not a one-time decision — it is a continuous process. Tax legislation changes. Your portfolio grows. Your income changes. Your family circumstances evolve. An annual review of your tax position is not optional; it is a professional obligation to your own financial future.


Property Investor Action 1: Review Your Ownership Structure

Ask yourself whether your current structure — personal, corporate, or LLP — still aligns with your investment strategy and income needs. Key triggers for a structure review:

  • You own four or more properties personally and are a higher-rate taxpayer
  • Your mortgage interest is significantly restricted under Section 24
  • You are reinvesting profits rather than living off them
  • You have family members who could benefit from share gifting
  • You are planning to grow the portfolio significantly in the next 5 years

Personal vs company ownership — 2025 guide


Property Investor Action 2: Prepare for Making Tax Digital

If your property income exceeds £50,000, you must be fully MTD-compliant from 6 April 2026 — less than 12 months away. Steps to take immediately:

  1. Select an HMRC-approved accounting platform (QuickBooks, Xero, FreeAgent, or a property-specific system)
  2. Migrate from spreadsheets to the new platform and reconcile current-year figures
  3. Set up bank feeds for automatic transaction capture
  4. Confirm your bookkeeper or accountant is familiar with MTD quarterly submission requirements

Property records and Making Tax Digital


Property Investor Action 3: Audit Your Expense Claims

Most landlords underclaim expenses. A professional review of your last two years of tax returns commonly identifies missed claims for replacement domestic items, apportioned phone and broadband costs, travel to inspect properties, and professional fees. Each missed £1,000 of expense costs between £200 and £450 in unnecessary tax.

Allowable expenses for property investors


Property Investor Action 4: Start Inheritance Tax Planning Now

IHT planning has a minimum seven-year horizon. The best time to start was seven years ago; the second best time is today. Key steps:

  1. Prepare an up-to-date inventory of all property assets with current market values
  2. Calculate your total IHT exposure above available NRB and RNRB allowances
  3. Identify which properties could be gifted (as shares if in a company) to begin the seven-year clock
  4. Review whether a Family Investment Company or trust would benefit your specific circumstances
  5. Ensure a current will is in place that correctly reflects all property ownership structures

Pass on property wealth without paying too much tax


Property Investor Action 5: Review SDLT Positions on Recent Purchases

If you have purchased property in the last 12 months, a professional SDLT review may identify overpayments — particularly where a mixed-use classification or Multiple Dwellings Relief could have applied but wasn’t claimed. HMRC allows amendments within 12 months of the filing date.

How to legally reduce stamp duty


Property Investor Tax Checklist for 2025–2026

ActionPriorityTimeline
Review ownership structure with a specialist accountantHighWithin 3 months
Select and migrate to MTD-compliant softwareCritical (if income >£50k)Before 6 April 2026
Audit last 2 years of expense claimsMedium-HighBefore next tax return
Model IHT exposure and begin gifting planHighWithin 6 months
Review SDLT positions on recent purchasesMediumWithin 12 months of each purchase
Assess FHL or SA qualification for short-term letsMediumAt portfolio review
Check pension contribution headroom for corp tax efficiencyHighBefore year-end
Ensure company board minutes and dividend documentation are currentHighAnnually
Obtain advance HMRC clearance for any planned restructuringCriticalBefore any transaction
Felix Accountants: Your Property Tax Partner
From first-time landlords to multi-entity developers, Felix Accountants provides specialist property tax advice, structuring, MTD compliance, and HMRC representation. Whether you need a tax review, incorporation planning, or a complete group restructure — we are your trusted property tax partner.


Complete Article Series — Internal Links

1 — Ownership structure | 2 — Allowable expenses | 3 — Paying yourself | 4 — Incorporation relief | 5 — VAT and property

6 — SPV structures | 7 — Records and MTD | 8 — Reducing SDLT | 9 — Pension property investment | 10 — Advanced structures

11 — Inheritance tax | 12 — Portfolio demergers | 13 — SA and HMO tax | 14 — Furnished Holiday Lets

Frequently Asked Questions

How often should I review my property tax position?

At minimum annually — ideally before the end of each tax year (5 April) and immediately after any significant transaction such as a purchase, sale, refinance, or structural change to your portfolio. Tax legislation changes frequently; your accountant should flag relevant changes proactively.


What is the single most impactful tax action a UK landlord can take in 2025?

For higher-rate taxpayers owning properties personally with significant mortgage debt, reviewing whether to incorporate (transferring to a limited company) typically delivers the largest single improvement in after-tax income. The combination of lower corporation tax and full interest deduction can add thousands annually per property.


How do I know if I need specialist property tax advice vs a general accountant?

If you own more than two properties, operate any form of company structure, have significant mortgage debt, are planning to pass assets to family, or are considering serviced accommodation or development, you need a specialist. General accountants may miss reliefs that a property tax specialist would apply as standard.


What should I do first if I am worried about unpaid property tax?

Consider the Let Property Campaign — HMRC’s voluntary disclosure process that allows landlords to bring their tax affairs up to date with significantly reduced penalties. An unprompted disclosure through the LPC consistently results in lower penalties than an HMRC-initiated investigation. See felixaccountants.com/let-property-campaign/ for detailed guidance.


How can Felix Accountants help me with my property tax?

Felix Accountants provides a full spectrum of UK property tax services: ownership structure reviews, incorporation planning, SDLT mitigation, MTD compliance setup, IHT structuring, FHL qualification reviews, corporate group design, and Let Property Campaign disclosures. Book a free 30-minute consultation at calendly.com/fndeloh/30min to discuss your specific position.


Property success in 2025 and beyond depends on structure, compliance, and foresight. Book your comprehensive property tax review with Felix Accountants today.

Book Your Comprehensive Property Tax Review


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

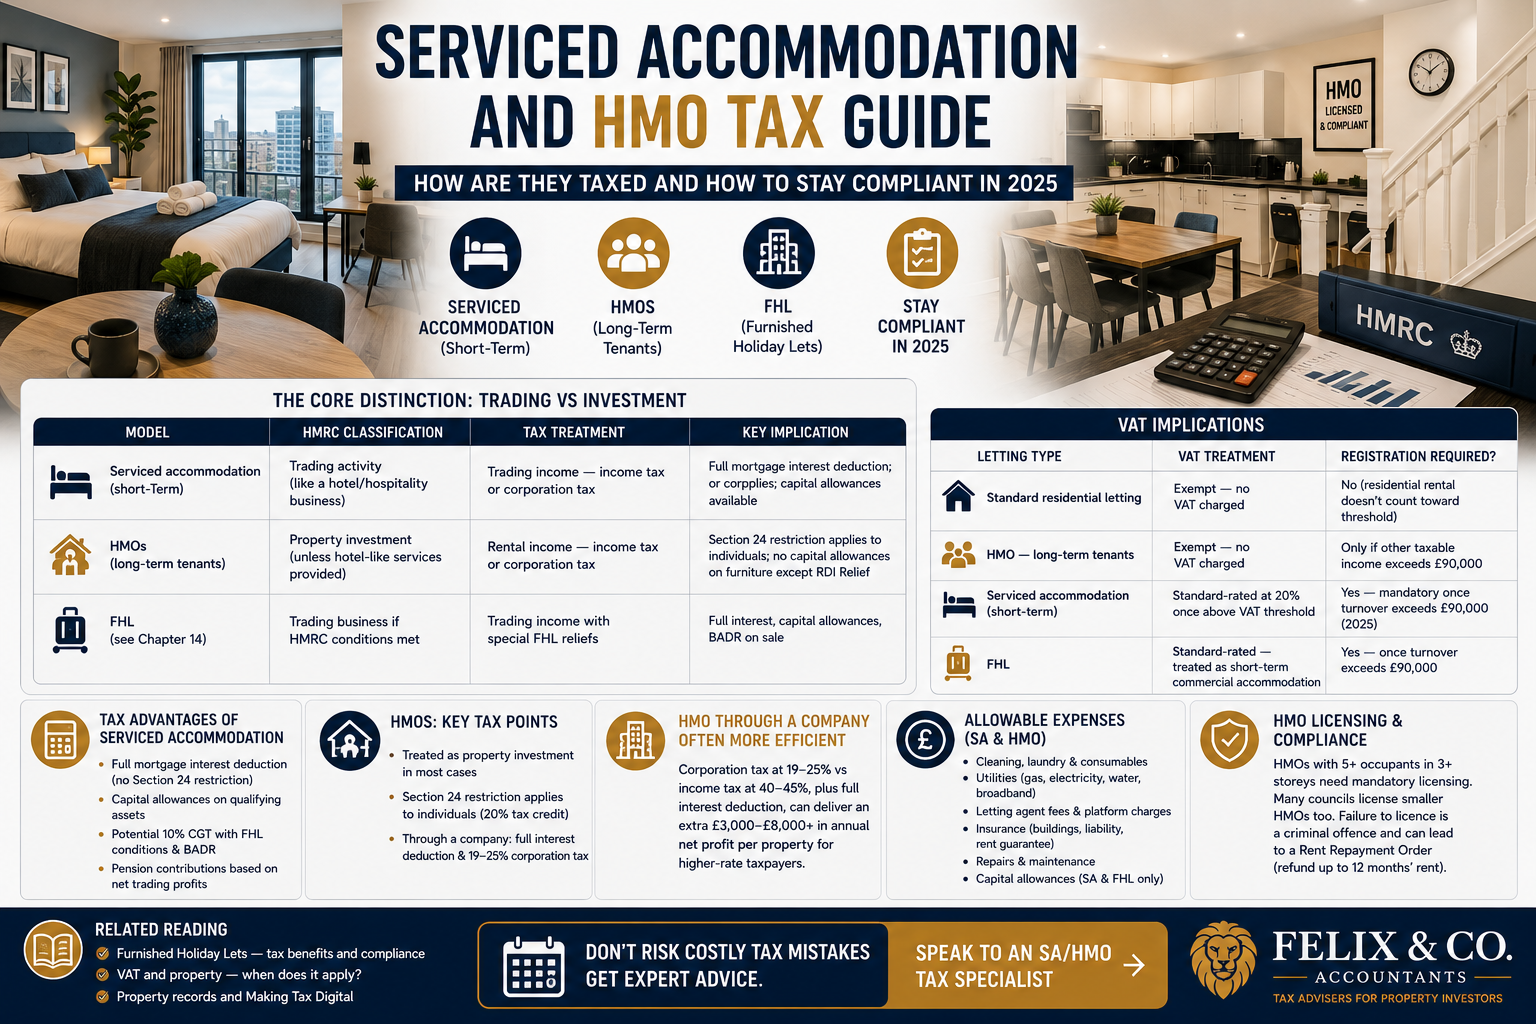
Serviced Accommodation and HMO Tax Guide: How Are They Taxed and How to Stay Compliant in 2025

Serviced accommodation and HMOs have transformed from niche strategies into mainstream property businesses — but their tax treatment is substantially different from standard buy-to-let, and HMRC is paying increasing attention to operators who blur the boundaries. This guide explains exactly how each model is taxed and what you must do to remain compliant.

serviced accommodation

Serviced Accommodation vs HMO Tax Treatment

ModelHMRC ClassificationTax TreatmentKey Implication
Serviced accommodation (short-term)Trading activity (like a hotel/hospitality business)Trading income — income tax or corporation taxFull mortgage interest deduction; NIC applies; capital allowances available
HMOs (long-term tenants)Property investment (unless hotel-like services provided)Rental income — income tax or corporation taxSection 24 restriction applies to individuals; no capital allowances on furniture except RDI Relief
FHL (see Chapter 14)Trading business if HMRC conditions metTrading income with special FHL reliefsFull interest, capital allowances, BADR on sale


Serviced Accommodation Tax Rules

Serviced accommodation income is generally classed as trading income. This delivers several significant advantages over standard residential letting:

  • Full mortgage interest deduction — Section 24 restriction does not apply to trading activity
  • Capital allowances on furniture, fixtures, equipment, and technology installations
  • Potential Business Asset Disposal Relief at 10% CGT rate on sale where FHL conditions are also met
  • Pension contributions can be made based on net trading profits

However, trading classification also means: Class 2 and Class 4 National Insurance contributions may apply to individual operators; and local authority business rates replace council tax for most SA properties.

Tax Treatment: HMOs

HMOs are typically treated as standard residential property investment. Individual HMO landlords face the Section 24 mortgage interest restriction (20% tax credit only). Through a limited company, interest remains fully deductible and corporation tax rates of 19–25% apply.

HMO Through a Company — Often More Efficient
For HMO landlords with significant mortgage borrowing, the limited company route can substantially improve net returns. Corporation tax at 19–25% versus income tax at 40–45%, combined with full interest deduction, frequently delivers an extra £3,000–£8,000+ in annual net profit per property for higher-rate taxpayers.


VAT on Serviced Accommodation and HMOs

Letting TypeVAT TreatmentRegistration Required?
Standard residential lettingExempt — no VAT chargedNo (residential rental doesn’t count toward threshold)
HMO — long-term tenantsExempt — no VAT chargedOnly if other taxable income exceeds £90,000
Serviced accommodation (short-term)Standard-rated at 20% once above VAT thresholdYes — mandatory once turnover exceeds £90,000 (2025)
FHLStandard-rated — treated as short-term commercial accommodationYes — once turnover exceeds £90,000


Allowable Expenses for SA and HMO

  • Cleaning, laundry, and consumable supplies (toiletries, linen, kitchen essentials)
  • Utilities (gas, electricity, water, broadband) — where paid by the landlord
  • Letting agent and management fees; booking platform charges (Airbnb, Booking.com)
  • Buildings and liability insurance; rent guarantee insurance
  • Repairs and maintenance (not capital improvements)
  • Capital allowances on furniture, TVs, appliances, CCTV (SA and FHL operators only)


HMO Licensing and Regulatory Compliance

HMOs with 5 or more occupants in 3 or more storeys require mandatory licensing from the local authority. Many councils have introduced additional licensing requirements for smaller HMOs. Failure to licence is a criminal offence and can result in a Rent Repayment Order requiring the landlord to refund up to 12 months of rent.

Related Reading

Furnished Holiday Lets — tax benefits and compliance | VAT and property — when does it apply? | Property records and Making Tax Digital

Frequently Asked Questions

Is Airbnb income taxed as a trade or rental income?

If you let a property short-term on Airbnb with cleaning, linen changes, and guest services, HMRC typically treats this as trading income. If you simply let the property without services and guests manage themselves, the distinction is less clear. The FHL tests (if applicable) provide the clearest framework — if those are not met, the income may be taxed as property investment income.


Do I need to register for VAT for my serviced accommodation?

Yes, once your gross turnover from short-term letting (including all SA and FHL income) exceeds £90,000 per year (2025/26 threshold), you must register for VAT and charge 20% on income. You can then reclaim VAT on all business expenses including cleaning, utilities, and refurbishments.


Can I claim capital allowances on my HMO furniture?

Not on standard buy-to-let HMO furniture. The Replacement of Domestic Items Relief allows a deduction only when you replace an existing item like-for-like — there are no capital allowances on initial furnishing costs. Serviced accommodation and FHL operators can claim capital allowances on all eligible fixtures and equipment.


What is a Rent Repayment Order and when can tenants apply for one?

A Rent Repayment Order (RRO) allows tenants to reclaim up to 12 months of rent from a landlord who has committed a housing offence — including operating an unlicensed HMO or failing to comply with an improvement notice. The First-Tier Tribunal can order repayment even where the landlord is later prosecuted.


Should I hold my HMO portfolio in a company or personally?

For higher-rate taxpayers with significant mortgage borrowing, a limited company typically provides substantially better returns: full interest deduction, 19–25% corporation tax versus 40–45% income tax, and greater extraction flexibility. The decision depends on current leverage, income needs, and long-term portfolio plans.


Don’t manage your serviced accommodation or HMO tax position without professional support. Book a consultation with Felix Accountants today.

Speak to an SA/HMO Tax Specialist


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

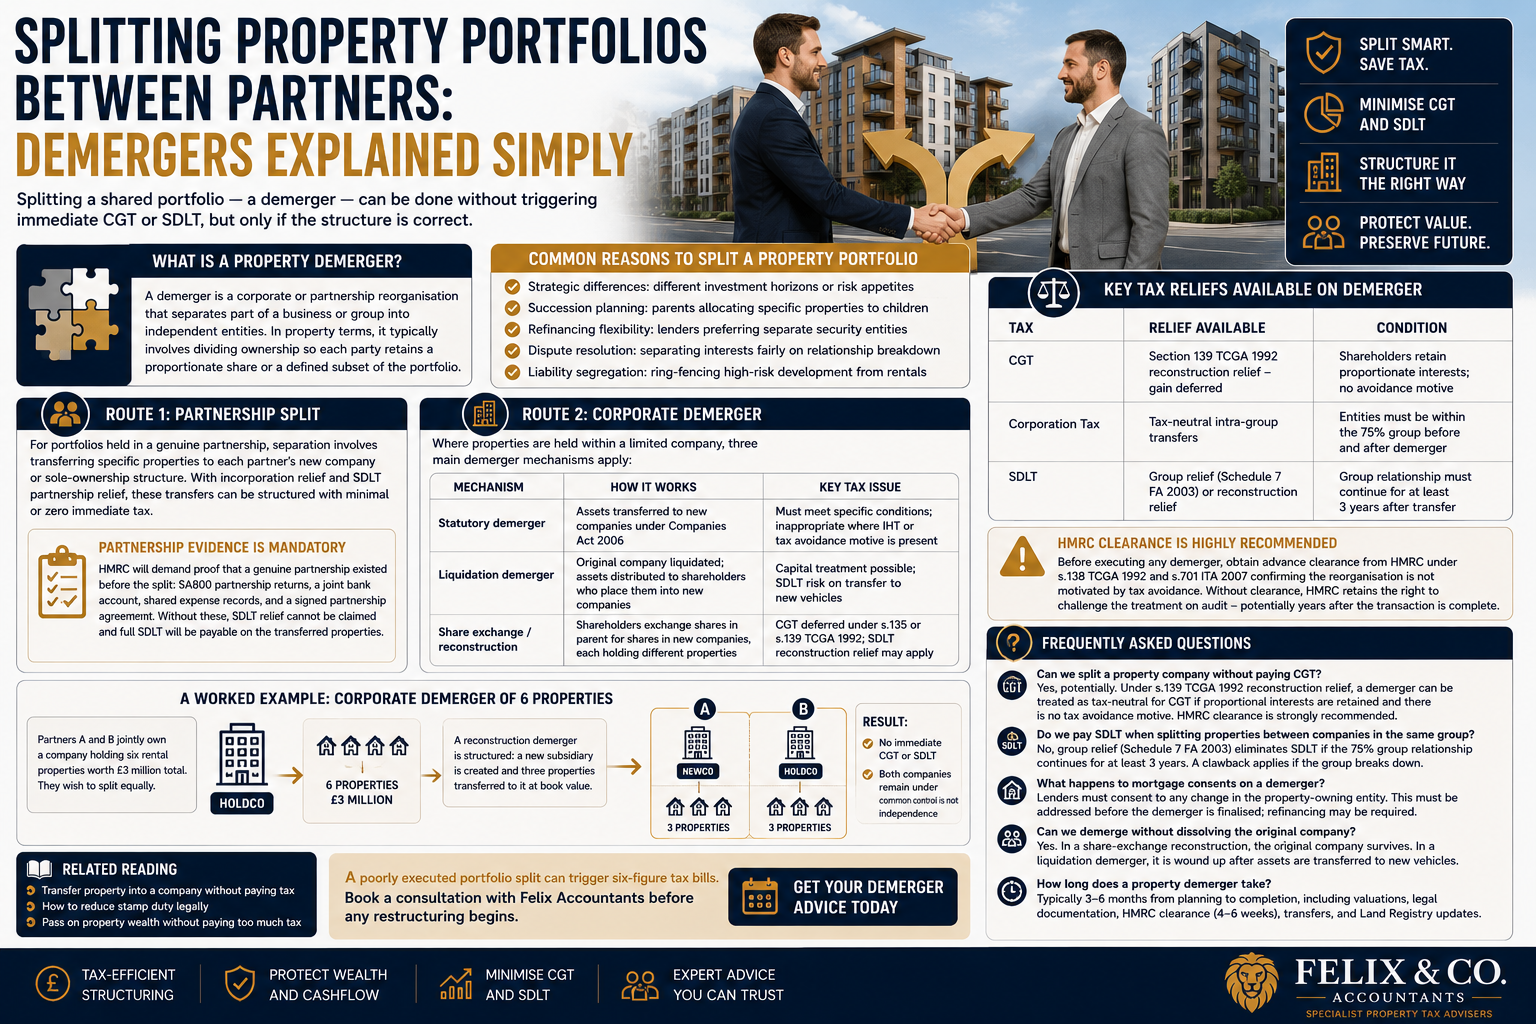
Splitting Property Portfolios Between Partners: Demergers Explained Simply

A property portfolio demerger allows property investors, business partners and family members to split shared property holdings in a tax-efficient way. As property partnerships evolve, partners often reach a point where their strategic objectives diverge. One wants to continue growing a rental portfolio; another wants to focus on development. Others simply wish to go their separate ways. Splitting a shared portfolio — a demerger — can be done without triggering immediate CGT or SDLT, but only if the structure is correct.

Property portfolio demerger

What Is a Property Portfolio Demerger?

A demerger is a corporate or partnership reorganisation that separates part of a business or group into independent entities. In property terms, it typically involves dividing ownership so each party retains a proportionate share or a defined subset of the portfolio.

Why Investors Use a Property Portfolio Demerger

  • Strategic differences: different investment horizons or risk appetites between partners
  • Succession planning: parents allocating specific properties to individual children
  • Refinancing flexibility: lenders preferring separate security entities per investor
  • Dispute resolution: separating interests fairly on relationship breakdown
  • Liability segregation: ring-fencing high-risk development projects from stable rental assets


Property Portfolio Demerger Through a Partnership Split

For portfolios held in a genuine partnership, separation involves transferring specific properties to each partner’s new company or sole-ownership structure. Where incorporation relief and SDLT partnership relief apply (as discussed in Chapter 4), these transfers can be structured with minimal or zero immediate tax.

Partnership Evidence Is Mandatory
HMRC will demand proof that a genuine partnership existed before the split: SA800 partnership returns, a joint bank account, shared expense records, and a signed partnership agreement. Without these, SDLT relief cannot be claimed and full SDLT will be payable on the transferred properties.


 Property Portfolio Demerger Through a Corporate Restructure

Where properties are held within a limited company, three main demerger mechanisms apply:

MechanismHow It WorksKey Tax Issue
Statutory demergerAssets transferred to new companies under Companies Act 2006Must meet specific conditions; inappropriate where IHT or tax avoidance motive is present
Liquidation demergerOriginal company liquidated; assets distributed to shareholders who place them into new companiesCapital treatment possible; SDLT risk on transfer to new vehicles
Share exchange / reconstructionShareholders exchange shares in parent for shares in new companies, each holding different propertiesCGT deferred under s.135 or s.139 TCGA 1992; SDLT reconstruction relief may apply


Key Tax Reliefs for a Property Portfolio Demerger

TaxRelief AvailableCondition
CGTSection 139 TCGA 1992 reconstruction relief — gain deferredShareholders retain proportionate interests; no avoidance motive
Corporation TaxTax-neutral intra-group transfersEntities must be within the 75% group before and after demerger
SDLTGroup relief (Schedule 7 FA 2003) or reconstruction reliefGroup relationship must continue for at least 3 years after transfer
HMRC Clearance Is Highly Recommended
Before executing any demerger, obtain advance clearance from HMRC under s.138 TCGA 1992 and s.701 ITA 2007 confirming the reorganisation is not motivated by tax avoidance. Without clearance, HMRC retains the right to challenge the treatment on audit — potentially years after the transaction is complete.


A Worked Example: Corporate Demerger of 6 Properties

Partners A and B jointly own a company holding six rental properties worth £3 million total. They wish to split equally. A reconstruction demerger is structured: a new subsidiary is created and three properties transferred to it at book value. A receives shares in the new subsidiary; B retains shares in the original company. Result: no immediate CGT or SDLT, both companies remain under common control until independence.

Related Reading

Transfer property into a company without paying tax | How to reduce stamp duty legally | Pass on property wealth without paying too much tax

Frequently Asked Questions

Can we split a property company without paying CGT?

Potentially, yes. Under s.139 TCGA 1992 reconstruction relief, a demerger structured so that shareholders retain proportionate interests in the separated entities can be treated as tax-neutral for CGT. The structure must not be motivated by tax avoidance, and advance HMRC clearance is strongly recommended.


Do we pay SDLT when splitting properties between companies in the same group?

Group relief (Schedule 7 FA 2003) eliminates SDLT on transfers between companies within the same 75% corporate group, provided the group relationship is maintained for at least three years after the transfer. A clawback applies if the group relationship breaks down within that period.


What happens to mortgage consents on a demerger?

Existing lenders must consent to any change in the property-owning entity. This is a practical constraint that must be addressed before the demerger structure is finalised. In some cases, refinancing is required, which can create additional cost and delay.


Can we demerge without dissolving the original company?

Yes. In a share-exchange reconstruction, the original company survives — shareholders simply swap some shares for shares in a newly created company. In a liquidation demerger, the original company is wound up, but properties transfer to the shareholders’ new vehicles before dissolution.


How long does a property demerger take?

A well-prepared demerger typically takes 3–6 months from initial planning to completion. This includes obtaining valuations, drafting legal documents, applying for HMRC clearance (which can take 4–6 weeks), executing the transfers, and registering new ownership at HM Land Registry.


A poorly executed portfolio split can trigger six-figure tax bills. Book a consultation with Felix Accountants before any restructuring begins.

Get Your Demerger Advice Today


JSON-LD Schema Markup