Categories
Articles FAQs Guides

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Small businesses can write off the entire purchase price of qualifying equipment, software, and vehicles in the exact tax year they put those assets to work. This Section 179 tax code provision represents a significant opportunity to save cash and lower business overhead. Instead of writing off a fraction of a computer or truck purchase over a five-year recovery schedule, you can deduct the full amount immediately.

The rules shifted favorably recently. Thanks to the One Big Beautiful Bill Act (OBBBA), the deduction ceiling grew substantially. For the 2026 tax year, you can claim up to $2,560,000 in immediate write-offs.

Section 179 tax Deduction Basics

Most business assets lose value over time. Usually, you must spread your deduction for that loss over several years. Section 179 changes this standard system. It lets you accelerate the write-off process by claiming the entire depreciation expense in year one.

To use this tax break, you must meet key timing requirements. You must buy or lease the asset and place it into service by midnight on December 31 of the tax year. “Placed in service” means the equipment is fully functional and ready for its intended business use. Merely purchasing the item or leaving it in its box does not count.

The deduction is subject to a dollar-for-dollar phase-out. For 2026, the spending threshold begins at $4,090,000.If your company spends more than that on qualifying business property, your maximum allowed deduction decreases by the excess amount. Once your capital equipment spending hits $6,650,000, your deduction drops to zero.

How to Calculate Your Section 179 tax Write-Off

Calculating your savings requires three numbers. You need your total equipment purchase cost, your business use percentage, and your tax rate.

If you use an asset for both personal and business purposes, you must prorate the deduction. The asset must serve your business more than 50% of the time to qualify at all. For example, suppose you purchase a $10,000 heavy-duty printer. You use it 80% for client work and 20% for personal printing. Your qualifying cost basis becomes $8,000.

Here is a straightforward calculation for a business using 100% business-use equipment:

Calculation StepExample Values
Total Equipment Cost$150,000
Section 179 Deduction$150,000
Estimated Tax Rate35%
Direct Tax Cash Savings$52,500
Net Cost of Equipment$97,500

If your total purchases exceed the $4,090,000 threshold, apply this formula:

Deduction Limit=$2,560,000−(Total Purchases−$4,090,000)

For example, if you buy $4,500,000 in equipment, your excess spending is $410,000. Your modified deduction ceiling drops to $2,150,000.
Section Section 179 tax

Qualifying Property Under Section 179 tax Rules

The IRS limits this deduction to specific asset types. Most tangible personal property used in your business qualifies.

The primary categories include:

  • Office furniture like desks, chairs, and conference tables.
  • Computers, servers, laptops, and networking hardware.
  • Off-the-shelf software available to the general public with a non-exclusive license.
  • Manufacturing machinery, printing presses, and specialized tools.
  • Qualified Improvement Property (QIP) including interior renovations to commercial buildings.
  • Building security systems, fire alarms, HVAC units, and commercial roofing.

Both new and used equipment qualify for the write-off. The used equipment must be new to your business. You cannot purchase used gear from a related family member or business entity to claim the write-off.

Vehicle Rules and Weight Limits

Vehicles face stricter standards due to historical abuse of the tax code. The IRS categorizes vehicles by Gross Vehicle Weight Rating (GVWR). You can find this rating on the manufacturer label inside the driver side door jamb.

Passenger cars and light trucks under 6,000 lbs GVWR have a low caps limit. For 2026, these light vehicles are subject to a maximum first-year depreciation limit of $20,300.

Heavy SUVs, pickup trucks, and cargo vans with a GVWR between 6,001 and 14,000 lbs qualify for a higher threshold. In 2026, the maximum Section 179 deduction for these heavy SUVs is capped at $32,000.Large commercial vehicles exceeding 14,000 lbs GVWR escape passenger limits entirely. Delivery trucks, box trucks, buses, and heavy construction equipment qualify for the full Section 179 write-off up to the $2,560,000 cap.

Section 179 tax vs Bonus Depreciation

Bonus depreciation is another accelerated tax incentive, but it operates under different rules. Under the current 2026 rules, 100% bonus depreciation is available for qualified property.

Unlike Section 179, bonus depreciation does not cap your total deduction amount. It does not decrease based on your total capital purchases during the year.

Another major difference involves business income. You cannot use Section 179 to create a net business loss. Your Section 179 deduction is limited to your net taxable business income. Bonus depreciation has no such limit. You can use it to create or increase a Net Operating Loss (NOL), which you can carry forward to offset future profits.

The standard approach is to apply Section 179 first to maximize deductions on specific assets. You then apply 100% bonus depreciation to any remaining asset basis.

How to Claim the Deduction on Your Taxes

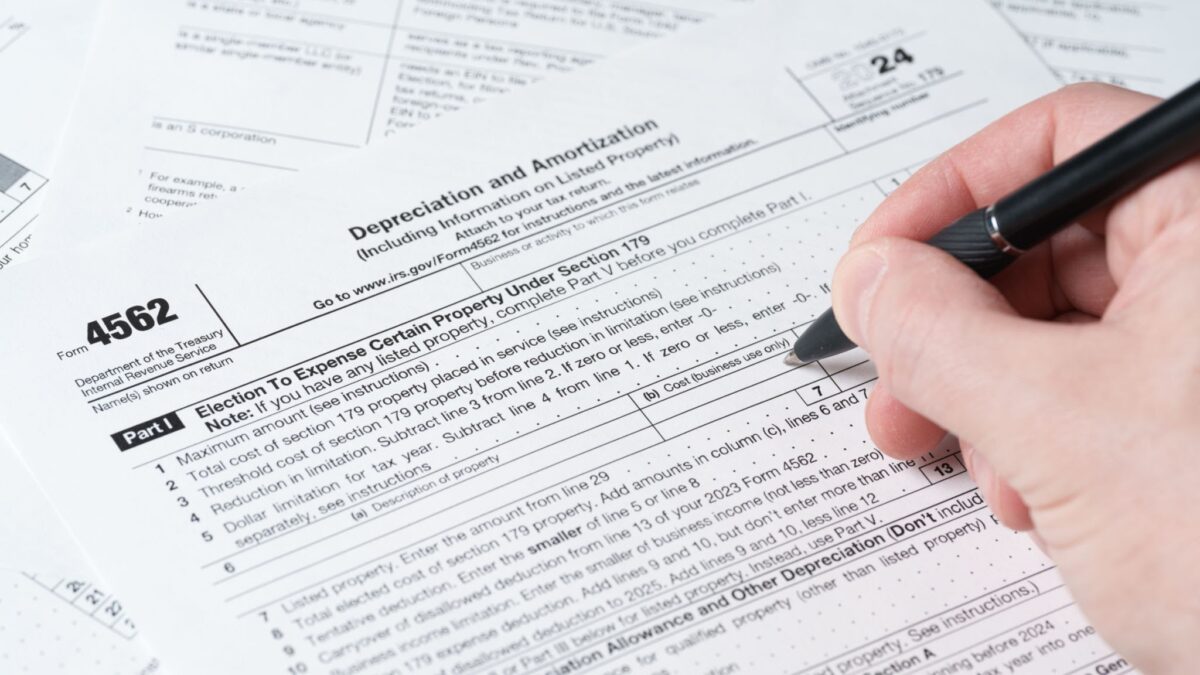
To claim this tax break, you must file IRS Form 4562 with your annual tax return. You will list the qualifying assets, their total cost, and the specific deduction amount you elect to expense.

Keep meticulous records for each purchase. Save the original invoices, receipts, and purchase contracts. Document the exact date you placed the equipment in service. If the asset has split business and personal use, maintain a log to prove your business use percentage exceeds the 50% threshold.
Section Section 179 tax

Frequently Asked Questions

Who qualifies for Section 179 tax?

All active businesses that purchase, finance, or lease qualifying new or used equipment during the tax year qualify for this write-off. You must use the acquired property for business operations more than 50% of the time to lock in your eligibility. Meeting these criteria lets you claim the Section 179 tax deduction to lower your tax liability.

What are the Section 179 limits for 2026?

For the 2026 tax year, the maximum Section 179 tax deduction limit is $2,560,000. This limit begins to phase out dollar-for-dollar when your total qualifying equipment purchases exceed $4,090,000. Once your annual equipment spending reaches $6,650,000, the deduction is completely unavailable.

Can used equipment qualify for Section 179?

Yes, used equipment qualifies for the write-off as long as it is new to your business. You cannot buy the used assets from a related business or family member. The Section 179 tax provisions treat qualifying used machinery, furniture, and tools exactly like brand-new hardware.

What is the difference between Section 179 and bonus depreciation?

The Section 179 tax deduction cannot exceed your active business taxable income, meaning it cannot create a net loss. It is capped at $2,560,000. Conversely, 100% bonus depreciation is uncapped and can create a net operating loss to offset taxes in other years.

Does a vehicle qualify for Section 179?

Yes, vehicles qualify for this write-off, but the IRS applies strict weight limits. Light passenger cars under 6,000 lbs have low caps. Heavy work trucks, cargo vans, and specialized passenger vehicles over 6,000 lbs GVWR are eligible to receive the full Section 179 tax write-off.

How do you calculate a Section 179 deduction?

Multiply the total cost of your qualified equipment by your business-use percentage to find your depreciable basis. If your total annual spending is under $4,090,000, you can write off the entire basis up to $2,560,000 using the Section 179 tax code.

What is the maximum Section 179 deduction for an SUV?

For heavy passenger SUVs with a GVWR between 6,001 and 14,000 lbs, the maximum first-year Section 179 tax write-off is limited to $32,000 in 2026. You can depreciate any remaining value using bonus or standard MACRS schedules.

Can Section Section 179 tax create a net operating loss?

No, the Section 179 tax deduction cannot exceed your net business taxable income. If your business operates at a loss before the deduction, you cannot claim it to create a net operating loss. Any disallowed portion carries forward to the next tax year.

How Small Businesses Can Use Section 179 to Save Thousands on Taxes

Book Your Comprehensive Property Tax Review

Categories
Articles Blogs Guides

Mistakes Landlords Make That Can Land Them on HMRC’s Watchlist

Finding your business placed on an HMRC watchlist is a serious financial emergency. When His Majesty’s Revenue and Customs targets you, your routine operations face severe disruption. The tax authority monitors your transactions, visits your premises, and audits your filings with intense scrutiny.

If you suspect you are under investigation, you must act quickly. Ignoring the warning signs only increases your exposure to back taxes, interest, and criminal prosecution.

Understanding the HMRC Watchlist Programs

The tax authority uses two primary monitoring systems to track high-risk taxpayers. While many people refer to these collectively as a watchlist, they operate under different legal frameworks.

The Managing Serious Defaulters Programme

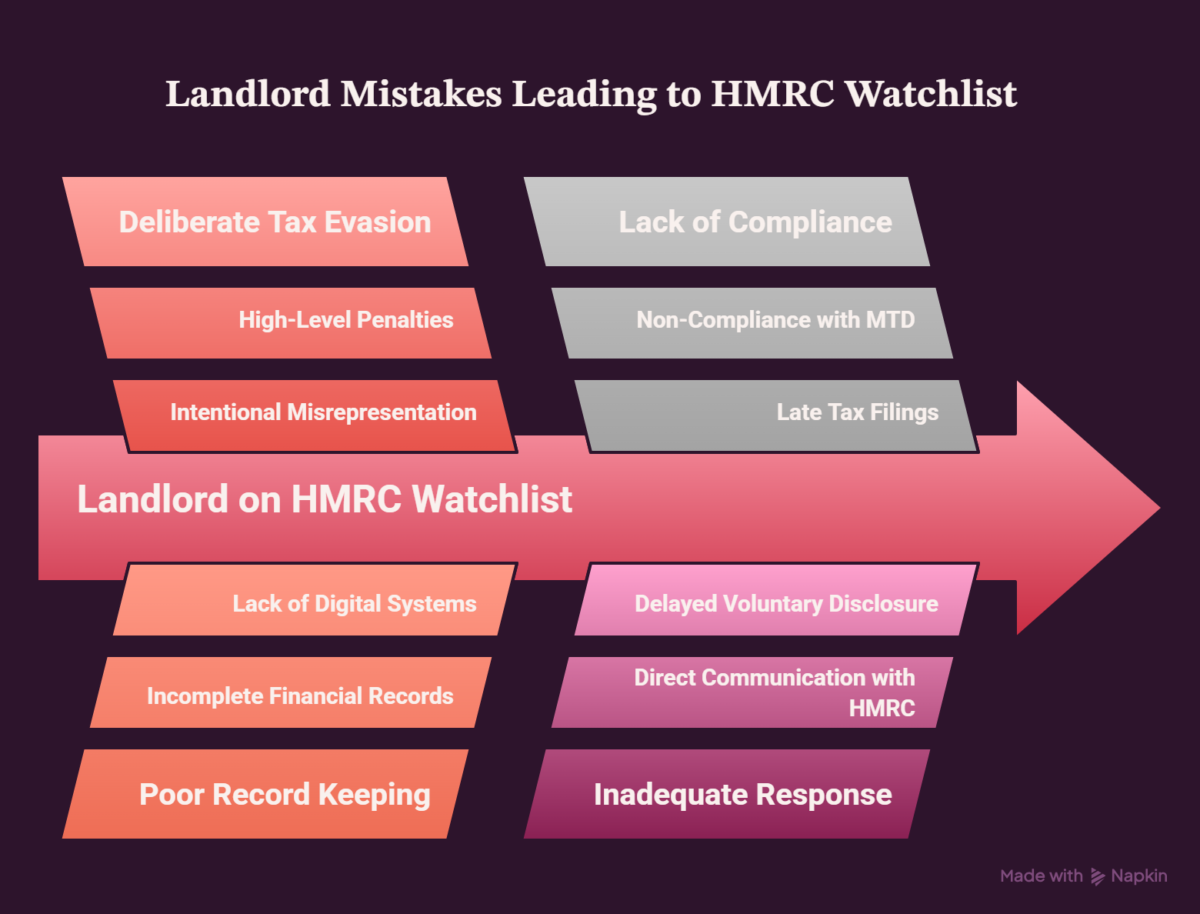
The Managing Serious Defaulters (MSD) program is an intensive, non-public monitoring regime. HMRC places you in this category if you have committed deliberate tax evasion or received high-level penalties.

Under MSD monitoring, you lose your right to file simplified tax returns. Instead, you must submit exhaustive financial records for up to five years. Officers frequently conduct unannounced physical inspections of your business premises.

The Publishing Details of Deliberate Defaulters List

If your deliberate defaults exceed £25,000, HMRC can publish your details on their official website. This public list remains online for exactly 12 months. The published information includes your name, business address, industry, and the exact penalty amount. This public exposure can destroy your professional reputation and invalidate your commercial credit terms.

How to Handle an HMRC Watchlist Investigation

If you are placed on a monitoring list, you must take immediate steps to protect your assets. The following workflow shows how to systematically address an active enquiry.

1.   Appoint a Specialist Tax Representative: Immediate.

Do not communicate with investigators directly. Retain a qualified tax dispute lawyer or a chartered accountant who specializes in HMRC investigations to handle all correspondence.

2.   Conduct a Voluntary Internal Audit: Within 14 Days.

Review your financial records for the last six years. Identify any discrepancies in your VAT, PAYE, or Corporate Tax returns before investigators point them out.

3.  Submit an Unprompted Disclosure: Before Findings Finalise.

If you discover errors, disclose them to HMRC voluntarily. Making an unprompted disclosure significantly lowers your overall penalty rate and can keep you off the public defaulters list.

4.   Implement Strict Compliance Systems: Ongoing.

Install digital accounting software that complies with Making Tax Digital (MTD) rules. Keep perfect transaction records and submit all future returns ahead of schedule.

Key Differences in HMRC watchlist Monitoring Regimes

The table below outlines the operational differences between standard tax compliance checks and active watchlist monitoring.

FeatureStandard Compliance CheckActive Watchlist Monitoring
Public DisclosureNonePublic name-and-shame for deliberate defaults over £25k
Duration of TrackingEnds when the check closesTypically 2 to 5 years under the MSD program
Inspection FrequencyPre-arranged visitsUnannounced spot checks of premises
Record RequirementsStandard statutory booksFull, non-simplified returns with detailed ledgers
Average Penalty Range0% to 30% of tax owed35% to 100% (or up to 200% for offshore issues)

Avoiding Common Triggers for Special Monitoring

HMRC selects targets using a sophisticated data-matching system called Connect. This software cross-references your bank accounts, property registries, credit card transactions, and online sales data.

To keep your business off their radar, avoid these common red flags:

  • Consistently filing returns late or making frequent retroactive amendments.
  • Showing lifestyle assets or property purchases that do not align with your declared personal income.
  • Declaring zero profits or claiming continuous tax losses for multiple consecutive years.
  • Failing to reconcile your digital payment processor receipts with your bank deposits.

    Mistakes Landlords Make That Can Land Them on HMRC's Watchlist
    HMRC’s Watchlist

Frequently Asked Questions

How do you know if HMRC watchlist are investigating you?

HMRC will formally notify you by sending an opening enquiry letter in the post. This letter specifies the tax years and returns under review. It also requests detailed financial documentation to support your filings. You will not receive prior warning before this official notification arrives.

How far back can HMRC go in an audit?

If you made an honest mistake, HMRC can review your records up to four years back. For careless errors, the limit extends to six years. However, if they suspect deliberate tax fraud or evasion, they can audit your accounts up to 20 years back.

What triggers an HMRC tax investigation?

An investigation is usually triggered by anomalies flagged by HMRC’s Connect data-matching software. Common triggers include declaring sudden drops in income, reporting continuous business losses, and omitting offshore assets. Discrepancies between your VAT submissions and bank accounts also draw attention.

Can you stop an HMRC compliance check?

You cannot legally block an active HMRC compliance check once it starts. However, you can apply for Alternative Dispute Resolution (ADR) if you disagree with their methodology. You can also appeal formal information notices if the requested data is irrelevant to the tax period.

What is the penalty for deliberate tax evasion in the UK?

Penalties for deliberate tax evasion range from 35% to 100% of the unpaid tax liability. If the evasion involves offshore assets, the fine can reach 200%. Furthermore, the tax authority can initiate criminal prosecutions leading to prison sentences.

How long does a serious tax investigation take?

A standard aspect check often concludes within three to six months. In contrast, a serious fraud or deliberate evasion investigation can last between one and three years. The duration depends on the complexity of your accounts and how cooperatively you provide the requested records.

Who gets put on the HMRC watchlist deliberate defaulters list?

HMRC places individuals and businesses on this public list if they deliberately understate their tax obligations. The defaults must involve more than £25,000 in unpaid tax. You can avoid publication by making a full, cooperative disclosure before HMRC closes the investigation.

What happens during an HMRC watchlist fraud investigation?

Investigators will examine your financial statements, bank records, and physical assets with extreme scrutiny. They may conduct unannounced site visits, interview you under caution, or secure search warrants. The process ends with either a formal tax settlement or criminal prosecution.

Mistakes Landlords Make That Can Land Them on HMRC’s WatchlistBook Your Comprehensive Property Tax Review


Categories
Blogs FAQs Guides

Common Tax Mistakes That Cost Small Businesses Money

When you run a company, managing your business tax obligations is often the most stressful part of the job, a single missed deduction or late filing can result in steep IRS penalties. Fortunately, most of these issues are entirely preventable. Let us look at where founders slip up and how you can keep more money in your pocket.

1. Mixing Personal and Business Accounts

Co-mingling your funds is the fastest way to trigger an IRS audit. If you buy groceries with your company credit card, you cloud your financial tracking.

Keep your accounts completely separate. Open a dedicated business checking account on day one. Pay for your software, inventory, and office supplies exclusively from this account. Doing so makes it incredibly simple to track write-offs and proves your business legitimacy to the IRS.

2. Missing Out on Valid Deductions

Many founders fail to claim legitimate write-offs. They leave money on the table out of fear of audits. If you use part of your home strictly for work, you can claim the home office deduction.

Keep a detailed log of your vehicle mileage. Save every receipt for meals with clients. Use accounting software to scan and categorize bills automatically. Over a year, these small deductions add up to thousands of dollars in business tax savings.

3. Misclassifying Your Workers

The IRS heavily polices the line between independent contractors and employees. If you control when, where, and how a worker performs their tasks, they are likely an employee.

Misclassifying a worker on a Form 1099 instead of a Form W-2 can cost you. You could face back taxes for FICA, federal unemployment taxes, and steep penalties. Review the IRS common law rules to ensure you classify your team members correctly.

How Business Tax Oversight Compares

The table below breaks down the financial impact of three frequent mistakes.

MistakeTypical Direct CostSimple Fix
Co-mingling FundsHigh audit risk, lost deduction trackingOpen a dedicated business account
Worker MisclassificationThousands in unpaid payroll taxes & finesUse IRS Form SS-8 for determination
Missing Mileage Tracking$0.67 per mile lost (IRS standard rate)Use an automatic mileage tracking app

4. Forgetting Estimated Quarterly Taxes

The US tax system operates on a pay-as-you-go model. If you expect to owe more than $1,000 when you file your annual return, you must make quarterly payments.

Missing these deadlines leads to underpayment penalties. Set aside 25% to 30% of your net income each month in a separate savings account. Pay your estimated installments by April 15, June 15, September 15, and January 15.

5. Filing Your Taxes Late

Procrastinating on your tax return is expensive. The failure-to-file penalty is 5% of your unpaid taxes per month. This fee is ten times higher than the failure-to-pay penalty of 0.5%.

Even if you do not have the money to pay your bill, you must file your return on time. Alternatively, file Form 7004 or Form 4868 to request an automatic six-month extension. This simple step eliminates the harsh late-filing fees.

businesses tax
businesses tax

Frequently Asked Questions

What happens if a small business tax makes a mistakes?

If your venture makes an error, the IRS sends a notice detailing the discrepancy. You may face penalties and interest on unpaid balances. Correcting the issue quickly minimizes financial damage. Working with a CPA helps resolve these issues.

Can you write off small business expenses without revenue?

Yes. You can write off startup costs up to $5,000 in your first active year. If your business has not launched yet, these costs are capitalized. They are then amortized over 15 years instead of being deducted immediately.

What is the most common businesses tax write-off for small businesses?

The most common deduction is ordinary and necessary operating expenses. This category includes rent, utilities, software subscriptions, advertising, and professional fees. Tracking these items continuously ensures you lower your overall business tax burden during filing season.

Do small businesses get audited often?

Small businesses face relatively low audit rates, usually under 1%. However, high-risk behaviors increase your chances of a review. These triggers include reporting consistent net losses, mixing personal expenses, and failing to report 1099 payments.

Is it better to file small business taxes as an LLC or S-Corp?

It depends on your net income. An LLC is simple and avoids double taxation. However, an S-Corp can reduce self-employment taxes once your business generates significant revenue. Consult a professional to see which structure fits your growth.

How much can a business write off without receipts?

The IRS generally requires receipts for any business expense over $75. However, you still need to document the time, place, and business purpose. Keeping digital copies of all receipts is the safest way to defend your deductions.

What happens if you do not pay estimated quarterly taxes?

If you skip quarterly payments, the IRS charges an underpayment penalty. The fee is calculated based on how much you owed and how late you paid. You can easily avoid this by making timely, estimated payments.

Can you deduct personal cell phone use for business?

Yes, you can deduct the business portion of your personal phone bill. You must calculate the exact percentage of time you use the device for work. Keep itemized phone bills to prove this split during an audit.

Learn More


Categories
Articles Blogs FAQs Guides

UK Stamp Duty Guide 2026

Understanding Stamp Duty UK 2026 is essential before buying a home or investment property. Whether you’re a first-time buyer, homeowner, landlord, or investor, knowing how Stamp Duty Land Tax (SDLT) works can help you avoid unnecessary costs and stay compliant with UK property purchase tax rules.

Everything you need to know about Stamp Duty UK 2026:

What Is Stamp Duty Land Tax (SDLT)?

Stamp Duty Land Tax (SDLT) is a tax paid when purchasing residential or commercial property in England and Northern Ireland above the applicable threshold. The amount you pay depends on the property’s value, your buyer status, and whether you’re purchasing an additional property.

For a complete explanation of UK property taxes, read our Property Tax Guide.

How Much Stamp Duty Will I Pay in 2026?

Your Stamp Duty bill depends on the property’s purchase price, whether you’re a first-time buyer, and if you’re buying an additional property. Current SDLT rates and reliefs should always be checked before completing your purchase.

You can also learn how to legally reduce your SDLT bill by reading our How to Reduce Stamp Duty Legally guide.

Who Is Exempt From Paying Stamp Duty?

Some buyers may qualify for exemptions or reliefs, including eligible first-time buyers and certain property transfers. Always confirm your eligibility before claiming any relief.

Do First-Time Buyers Pay Stamp Duty?

Many first-time buyers qualify for Stamp Duty relief, helping reduce the amount of tax payable on qualifying property purchases.

How Is Stamp Duty Calculated?

Stamp Duty is calculated based on the property’s purchase price, current SDLT tax bands, buyer status, and whether additional property surcharges apply.

If you’re buying property as an investment, our Property Investor Tax Strategy Guide can help you plan ahead.

When Do I Have to Pay Stamp Duty?

Stamp Duty is normally due shortly after completing your property purchase. Missing the deadline may result in penalties and interest.

Can I Reduce My Stamp Duty Bill Legally?

Yes. There are legitimate Stamp Duty reliefs and exemptions available depending on your circumstances. Professional tax advice can help ensure you only pay what you legally owe.

What Happens If I Pay Stamp Duty Late?

Late payment can lead to HMRC penalties, interest charges, and unnecessary delays. Paying on time helps you avoid additional costs.suspects-fraud-cop9

Official HMRC Guidance

For the latest Stamp Duty Land Tax rates and official government guidance, visit the HMRC Stamp Duty Land Tax page.

HMRC compliance
HMRC compliance

You can also check the latest residential Stamp Duty rates on the UK Government SDLT Rates page.


Need expert advice on Stamp Duty UK 2026?
Contact Felix & Co Chartered Tax for professional guidance on Stamp Duty Land Tax, property purchase tax, and all UK property tax matters.

Book a Free Consultation

Categories
News

How UK Property Accountants Reduced a £9,000+ HMRC Penalty to Nil

A landlord in Berkshire opened a letter from HMRC and saw a penalty demand for more than £9,000. Nine months later, that figure was zero. Nothing about the tax owed had changed. What changed was how the disclosure was handled, and that’s the part most people get wrong.

This is a walkthrough of that case, anonymised for client confidentiality, and what it shows about how HMRC actually calculates and reduces penalties for undeclared rental income.

How the Penalty Reached Over £9,000 in the First Place

The client owned two rental properties in Reading, bought them in 2019 and 2021, and had never registered for Self Assessment on the rental income. This wasn’t tax evasion in any deliberate sense. He’d moved from an employed role into buy-to-let almost by accident, inherited one property, remortgaged to buy the second, and assumed his letting agent or his old employer’s payroll department was somehow “sorting the tax.” Neither was.

HMRC caught up with him through its Connect system, which cross-references Land Registry data, mortgage records, and letting agent reports against Self Assessment filings. He received what’s commonly called a nudge letter, a prompt asking him to check his tax position and come forward voluntarily. Ignoring it, or responding badly, is what usually turns a manageable situation into an expensive one. We’ve written before about what to do when an HMRC nudge letter arrives, and the short version is: don’t wait.

By the time he came to us, roughly £30,000 of rental income across four tax years had gone undeclared. The tax owed on that was significant on its own. But it was the penalty, calculated as a percentage of what HMRC calls the “potential lost revenue,” that pushed the total demand past £9,000.

Why the Penalty Was Calculated the Way It Was

Failure to notify HMRC of taxable income falls into three categories: non-deliberate, deliberate, and deliberate with concealment. Almost every landlord case we see is non-deliberate; people genuinely didn’t realise letting income needed reporting, or believed a small profit margin meant nothing was owed.

For a non-deliberate failure to notify, disclosed more than 12 months after the tax was due, the penalty range runs from 20% to 30% of the potential lost revenue if HMRC prompts the disclosure. Get there first, unprompted, and the range drops to 10% to 20%, sometimes lower. That gap between prompted and unprompted is the single biggest lever available, and it’s one reason speed matters more than most people assume. We break the distinction down properly on our prompted vs unprompted disclosure page.

Why This Situation Is So Common Among Landlords

Most people picture tax evasion as something calculated. In practice, the overwhelming majority of landlord disclosures we handle look nothing like that. A few patterns come up again and again:

  • Someone inherits a property, keeps renting it out, and never thinks of themselves as running a rental “business.”
  • A homeowner relocates for work, lets their old house rather than sell it, and treats the rent as background income rather than something requiring a tax return.
  • An accidental landlord assumes that because the mortgage swallows most of the rent, there’s no profit and therefore nothing to declare, which isn’t how HMRC calculates taxable profit.
  • A property investor with several units loses track of which ones are actually registered for Self Assessment as their portfolio grows.

If any of that sounds familiar, it’s worth reading our guide on accidental landlord tax obligations before HMRC gets in touch first.

The Strategy That Brought the Penalty Down to Nil

Getting from a £9,000+ demand to a nil penalty involved three separate arguments, run in parallel rather than as a single request for leniency.

Registering Through the Let Property Campaign

The Let Property Campaign is HMRC’s disclosure route specifically for landlords with undeclared rental income. It’s not an amnesty and it doesn’t erase the tax owed, but it structures the process in a way that lets a taxpayer demonstrate cooperation from the outset, which matters enormously when penalties are calculated. Because the client had already received a nudge letter, his disclosure was classed as prompted rather than unprompted, which meant the starting penalty range was higher than it would otherwise have been. Our Let Property Campaign guide covers how registration works and what HMRC expects at each stage.

Building the Quality of Disclosure

Within the penalty calculation, HMRC allows a reduction based on three factors: telling, helping, and giving. Telling covers how much the taxpayer volunteers unprompted, before HMRC has to ask. Helping covers the level of cooperation during the process, answering questions promptly, providing records without repeated requests. Giving covers access to documents and figures, including bank statements, mortgage certificates, and letting agent statements.

Combined, these three factors can reduce a penalty by up to 70% even where the disclosure itself was prompted. We prepared a complete, well-organised disclosure package before HMRC asked for a single follow-up document, which is the part most self-filed disclosures miss. People often register for the Let Property Campaign and then respond to HMRC’s questions reactively, one letter at a time, which reads to HMRC as reluctant cooperation rather than genuine transparency.

Arguing Special Circumstances

HMRC has the power to reduce a penalty, or not charge it at all, where it considers this right because of special circumstances. This isn’t the same as a reasonable excuse defence, which applies to the underlying failure itself; special reduction applies to the penalty specifically, and HMRC has discretion over when to use it.

In this case, we presented evidence of the client’s genuine and reasonable belief that his letting agent was managing tax reporting, alongside a clean compliance history and full, proactive cooperation once the nudge letter arrived. None of that erased the tax liability. What it did was give HMRC grounds to apply special reduction on top of the quality-of-disclosure reduction already secured.

Penalty typeStandard rangeReduction applied in this case
Non-deliberate, prompted disclosure, over 12 months late20%–30% of tax owedQuality of disclosure reduction (telling, helping, giving)
Reduced rate after quality-of-disclosure reductionAs low as 10% of the reduced rangeSpecial reduction applied on top
Final penalty£9,000+ as originally issued£0

The tax due on the £30,000 of previously undeclared income was still paid in full, along with interest for late payment. That part doesn’t disappear, and no legitimate accountant will tell a client otherwise. What disappeared was the penalty sitting on top of it.

What This Case Actually Teaches Other Landlords

A few things stand out from working through cases like this one:

  • Speed changes the penalty band. A voluntary, unprompted disclosure starts from a lower base than one triggered by a nudge letter, and a nudge letter starts from a lower base than a formal HMRC enquiry.
  • The quality of the disclosure package matters as much as the disclosure itself. HMRC assesses cooperation, not just honesty.
  • Special reduction is discretionary, not automatic. HMRC won’t apply it unless the case for it is made clearly, with evidence.
  • None of this reduces the tax owed. It reduces the penalty sitting on top of the tax owed, which is a different thing entirely.

If you want a rough sense of what a penalty might look like before you speak to anyone, our penalty calculator gives a starting estimate, though the real figure depends heavily on the disclosure route and quality factors described above.

Avoiding This Situation Before HMRC Gets Involved

The cheapest way to deal with an HMRC penalty is to never trigger one. For landlords who suspect they might have gaps in their rental income reporting, whether from a single let property or a growing portfolio, a few practical steps matter more than people expect.

Get Ahead of a Nudge Letter

If you haven’t received one yet but suspect your position isn’t fully compliant, an unprompted disclosure through the Let Property Campaign is almost always cheaper than waiting. Once a letter arrives, the disclosure is classed as prompted and the penalty range moves against you.

Keep Records HMRC Would Recognise

Bank statements showing rent received, mortgage interest certificates, and invoices for allowable expenses all matter when calculating potential lost revenue accurately, rather than HMRC estimating a figure in your absence. Our guide to allowable expenses for property investors is worth reading even if you’re not currently under review, since it affects how much profit is actually taxable in the first place.

Understand Your Local HMRC Activity

HMRC compliance activity around the Let Property Campaign isn’t evenly spread across the country. We work regularly with landlords facing enquiries in Reading, Windsor, Oxford, London, and Slough, and the pattern of nudge letters we see in each area gives us a reasonably clear picture of where HMRC is currently focusing attention.

Frequently Asked Questions

Can HMRC reduce or cancel a penalty entirely?

Yes. HMRC can apply what’s called special reduction where it considers this right because of special circumstances, and this can apply on top of standard reductions for quality of disclosure. It’s discretionary rather than guaranteed, which is why the way a case is presented matters.

What’s the difference between a prompted and unprompted disclosure?

An unprompted disclosure means you told HMRC before they had any reason to suspect an issue. A prompted disclosure, such as one made after a nudge letter, starts from a higher penalty range because HMRC had already identified you as a possible risk before you came forward.

What counts as a reasonable excuse for not notifying HMRC?

HMRC recognises things like serious illness, a genuine misunderstanding of a legal obligation, or events like fire, flood or theft that prevented compliance. A vague belief that “someone else was handling it,” on its own, rarely qualifies as a reasonable excuse, though it can support an argument for special reduction if backed by evidence.

What happens if I ignore an HMRC penalty notice?

Interest continues to accrue and HMRC can escalate to enforcement action, including debt recovery. You generally have 30 days from the date of the penalty notice to appeal or challenge it, and missing that window makes the process considerably harder.

Do I need a specialist accountant for a Let Property Campaign disclosure?

You can register and disclose without one, but the penalty calculation depends heavily on how the disclosure is presented, not just what’s disclosed. An accountant experienced with HMRC’s quality-of-disclosure factors and special reduction criteria can materially change the outcome, as this case shows.

How much rental income can trigger an HMRC investigation?

There’s no fixed threshold. HMRC’s Connect system cross-references property records, mortgage data, and letting agent reports against tax filings, so even modest undeclared rental profit can surface. The safer approach is registering for Self Assessment as soon as letting income begins, regardless of the amount.

Every case is different, and penalty outcomes depend on individual circumstances, evidence, and how a disclosure is handled from the first letter onward.

Felix & Co. work with landlords and property investors across Slough, Reading, Windsor, London and Oxford on exactly this kind of disclosure.

Book a Free Consultation Call
Categories
Articles Articles Blogs Guides

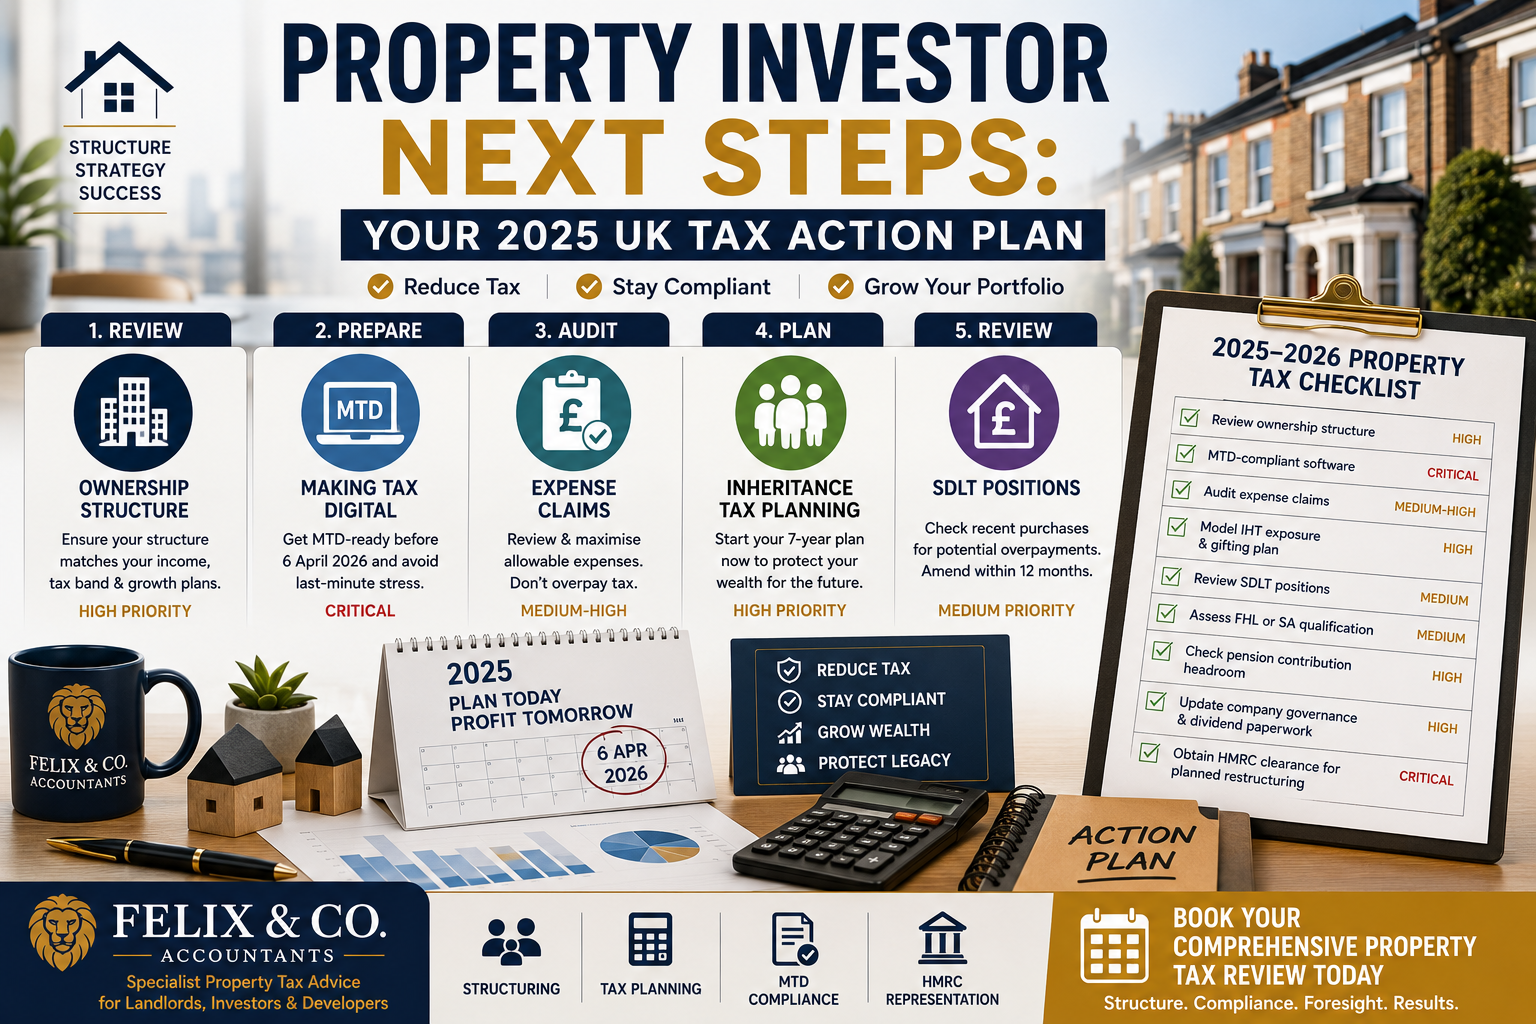
Property Investor Next Steps: Your 2025 UK Tax Action Plan

As a property investor, understanding tax rules is only the first step. The real value comes from turning that knowledge into practical action. Throughout this series, we’ve explored ownership structures, allowable expenses, SDLT planning, inheritance tax, company structures, and compliance obligations. This final guide provides a clear and prioritised property investor tax strategy for 2025, helping you protect profits, reduce tax liabilities, and prepare for future growth.

property investor

The Core Principle Every Property Investor Should Follow
Tax efficiency in property is not a one-time decision — it is a continuous process. Tax legislation changes. Your portfolio grows. Your income changes. Your family circumstances evolve. An annual review of your tax position is not optional; it is a professional obligation to your own financial future.


Property Investor Action 1: Review Your Ownership Structure

Ask yourself whether your current structure — personal, corporate, or LLP — still aligns with your investment strategy and income needs. Key triggers for a structure review:

  • You own four or more properties personally and are a higher-rate taxpayer
  • Your mortgage interest is significantly restricted under Section 24
  • You are reinvesting profits rather than living off them
  • You have family members who could benefit from share gifting
  • You are planning to grow the portfolio significantly in the next 5 years

Personal vs company ownership — 2025 guide


Property Investor Action 2: Prepare for Making Tax Digital

If your property income exceeds £50,000, you must be fully MTD-compliant from 6 April 2026 — less than 12 months away. Steps to take immediately:

  1. Select an HMRC-approved accounting platform (QuickBooks, Xero, FreeAgent, or a property-specific system)
  2. Migrate from spreadsheets to the new platform and reconcile current-year figures
  3. Set up bank feeds for automatic transaction capture
  4. Confirm your bookkeeper or accountant is familiar with MTD quarterly submission requirements

Property records and Making Tax Digital


Property Investor Action 3: Audit Your Expense Claims

Most landlords underclaim expenses. A professional review of your last two years of tax returns commonly identifies missed claims for replacement domestic items, apportioned phone and broadband costs, travel to inspect properties, and professional fees. Each missed £1,000 of expense costs between £200 and £450 in unnecessary tax.

Allowable expenses for property investors


Property Investor Action 4: Start Inheritance Tax Planning Now

IHT planning has a minimum seven-year horizon. The best time to start was seven years ago; the second best time is today. Key steps:

  1. Prepare an up-to-date inventory of all property assets with current market values
  2. Calculate your total IHT exposure above available NRB and RNRB allowances
  3. Identify which properties could be gifted (as shares if in a company) to begin the seven-year clock
  4. Review whether a Family Investment Company or trust would benefit your specific circumstances
  5. Ensure a current will is in place that correctly reflects all property ownership structures

Pass on property wealth without paying too much tax


Property Investor Action 5: Review SDLT Positions on Recent Purchases

If you have purchased property in the last 12 months, a professional SDLT review may identify overpayments — particularly where a mixed-use classification or Multiple Dwellings Relief could have applied but wasn’t claimed. HMRC allows amendments within 12 months of the filing date.

How to legally reduce stamp duty


Property Investor Tax Checklist for 2025–2026

ActionPriorityTimeline
Review ownership structure with a specialist accountantHighWithin 3 months
Select and migrate to MTD-compliant softwareCritical (if income >£50k)Before 6 April 2026
Audit last 2 years of expense claimsMedium-HighBefore next tax return
Model IHT exposure and begin gifting planHighWithin 6 months
Review SDLT positions on recent purchasesMediumWithin 12 months of each purchase
Assess FHL or SA qualification for short-term letsMediumAt portfolio review
Check pension contribution headroom for corp tax efficiencyHighBefore year-end
Ensure company board minutes and dividend documentation are currentHighAnnually
Obtain advance HMRC clearance for any planned restructuringCriticalBefore any transaction
Felix Accountants: Your Property Tax Partner
From first-time landlords to multi-entity developers, Felix Accountants provides specialist property tax advice, structuring, MTD compliance, and HMRC representation. Whether you need a tax review, incorporation planning, or a complete group restructure — we are your trusted property tax partner.


Complete Article Series — Internal Links

1 — Ownership structure | 2 — Allowable expenses | 3 — Paying yourself | 4 — Incorporation relief | 5 — VAT and property

6 — SPV structures | 7 — Records and MTD | 8 — Reducing SDLT | 9 — Pension property investment | 10 — Advanced structures

11 — Inheritance tax | 12 — Portfolio demergers | 13 — SA and HMO tax | 14 — Furnished Holiday Lets

Frequently Asked Questions

How often should I review my property tax position?

At minimum annually — ideally before the end of each tax year (5 April) and immediately after any significant transaction such as a purchase, sale, refinance, or structural change to your portfolio. Tax legislation changes frequently; your accountant should flag relevant changes proactively.


What is the single most impactful tax action a UK landlord can take in 2025?

For higher-rate taxpayers owning properties personally with significant mortgage debt, reviewing whether to incorporate (transferring to a limited company) typically delivers the largest single improvement in after-tax income. The combination of lower corporation tax and full interest deduction can add thousands annually per property.


How do I know if I need specialist property tax advice vs a general accountant?

If you own more than two properties, operate any form of company structure, have significant mortgage debt, are planning to pass assets to family, or are considering serviced accommodation or development, you need a specialist. General accountants may miss reliefs that a property tax specialist would apply as standard.


What should I do first if I am worried about unpaid property tax?

Consider the Let Property Campaign — HMRC’s voluntary disclosure process that allows landlords to bring their tax affairs up to date with significantly reduced penalties. An unprompted disclosure through the LPC consistently results in lower penalties than an HMRC-initiated investigation. See felixaccountants.com/let-property-campaign/ for detailed guidance.


How can Felix Accountants help me with my property tax?

Felix Accountants provides a full spectrum of UK property tax services: ownership structure reviews, incorporation planning, SDLT mitigation, MTD compliance setup, IHT structuring, FHL qualification reviews, corporate group design, and Let Property Campaign disclosures. Book a free 30-minute consultation at calendly.com/fndeloh/30min to discuss your specific position.


Property success in 2025 and beyond depends on structure, compliance, and foresight. Book your comprehensive property tax review with Felix Accountants today.

Book Your Comprehensive Property Tax Review


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

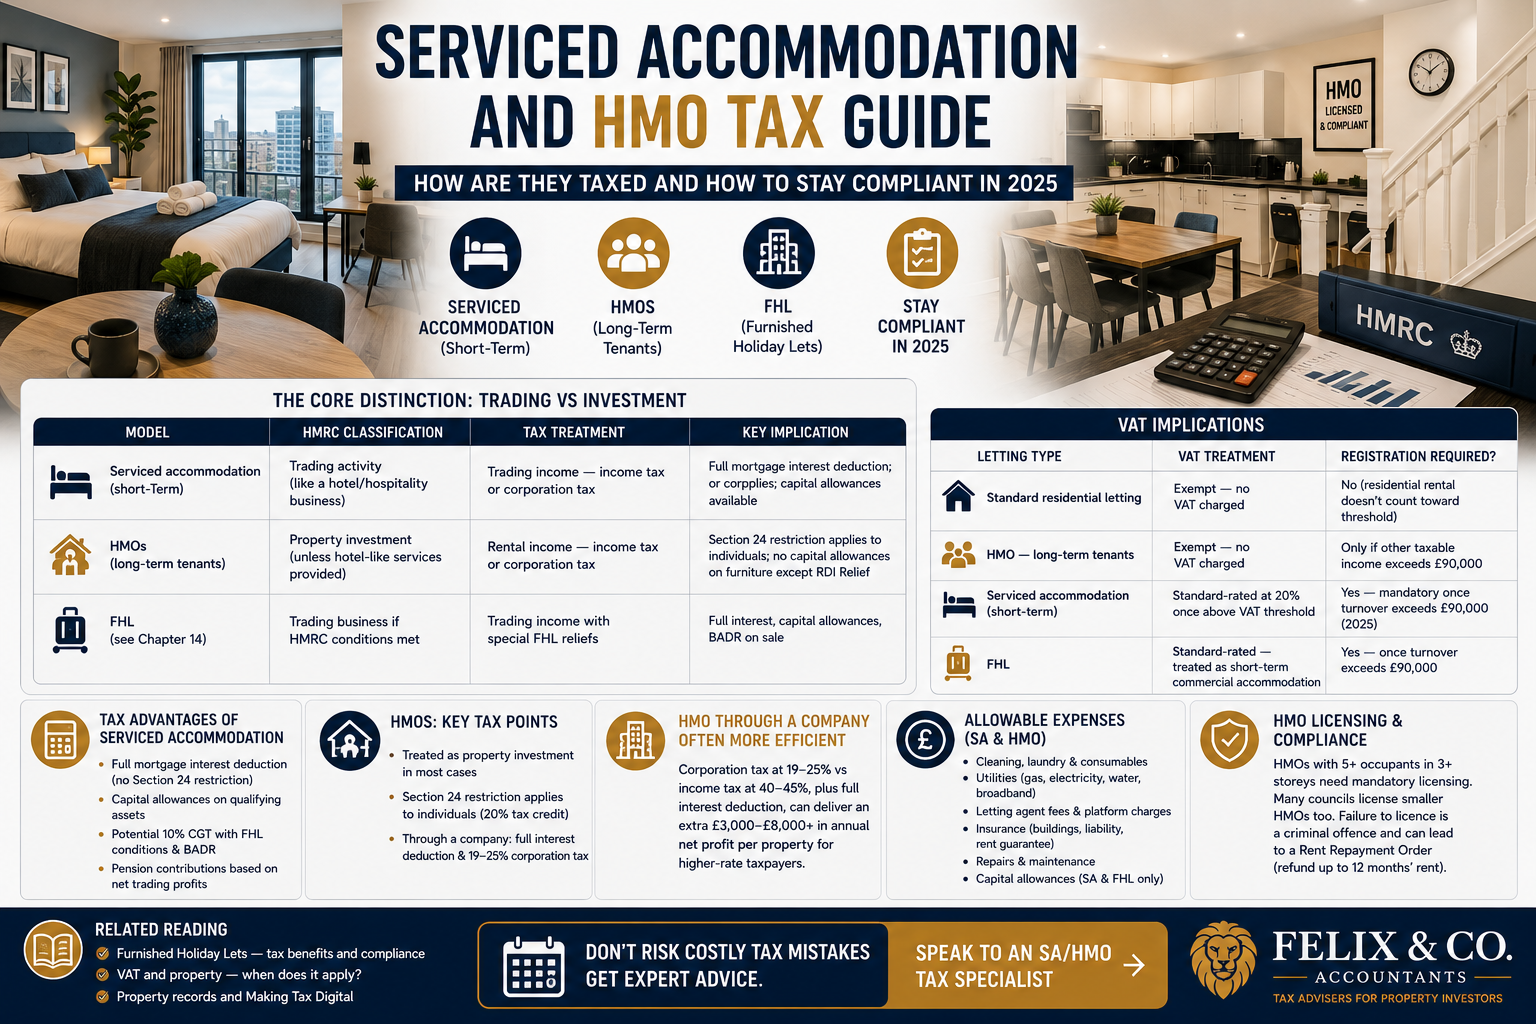
Serviced Accommodation and HMO Tax Guide: How Are They Taxed and How to Stay Compliant in 2025

Serviced accommodation and HMOs have transformed from niche strategies into mainstream property businesses — but their tax treatment is substantially different from standard buy-to-let, and HMRC is paying increasing attention to operators who blur the boundaries. This guide explains exactly how each model is taxed and what you must do to remain compliant.

serviced accommodation

Serviced Accommodation vs HMO Tax Treatment

ModelHMRC ClassificationTax TreatmentKey Implication
Serviced accommodation (short-term)Trading activity (like a hotel/hospitality business)Trading income — income tax or corporation taxFull mortgage interest deduction; NIC applies; capital allowances available
HMOs (long-term tenants)Property investment (unless hotel-like services provided)Rental income — income tax or corporation taxSection 24 restriction applies to individuals; no capital allowances on furniture except RDI Relief
FHL (see Chapter 14)Trading business if HMRC conditions metTrading income with special FHL reliefsFull interest, capital allowances, BADR on sale


Serviced Accommodation Tax Rules

Serviced accommodation income is generally classed as trading income. This delivers several significant advantages over standard residential letting:

  • Full mortgage interest deduction — Section 24 restriction does not apply to trading activity
  • Capital allowances on furniture, fixtures, equipment, and technology installations
  • Potential Business Asset Disposal Relief at 10% CGT rate on sale where FHL conditions are also met
  • Pension contributions can be made based on net trading profits

However, trading classification also means: Class 2 and Class 4 National Insurance contributions may apply to individual operators; and local authority business rates replace council tax for most SA properties.

Tax Treatment: HMOs

HMOs are typically treated as standard residential property investment. Individual HMO landlords face the Section 24 mortgage interest restriction (20% tax credit only). Through a limited company, interest remains fully deductible and corporation tax rates of 19–25% apply.

HMO Through a Company — Often More Efficient
For HMO landlords with significant mortgage borrowing, the limited company route can substantially improve net returns. Corporation tax at 19–25% versus income tax at 40–45%, combined with full interest deduction, frequently delivers an extra £3,000–£8,000+ in annual net profit per property for higher-rate taxpayers.


VAT on Serviced Accommodation and HMOs

Letting TypeVAT TreatmentRegistration Required?
Standard residential lettingExempt — no VAT chargedNo (residential rental doesn’t count toward threshold)
HMO — long-term tenantsExempt — no VAT chargedOnly if other taxable income exceeds £90,000
Serviced accommodation (short-term)Standard-rated at 20% once above VAT thresholdYes — mandatory once turnover exceeds £90,000 (2025)
FHLStandard-rated — treated as short-term commercial accommodationYes — once turnover exceeds £90,000


Allowable Expenses for SA and HMO

  • Cleaning, laundry, and consumable supplies (toiletries, linen, kitchen essentials)
  • Utilities (gas, electricity, water, broadband) — where paid by the landlord
  • Letting agent and management fees; booking platform charges (Airbnb, Booking.com)
  • Buildings and liability insurance; rent guarantee insurance
  • Repairs and maintenance (not capital improvements)
  • Capital allowances on furniture, TVs, appliances, CCTV (SA and FHL operators only)


HMO Licensing and Regulatory Compliance

HMOs with 5 or more occupants in 3 or more storeys require mandatory licensing from the local authority. Many councils have introduced additional licensing requirements for smaller HMOs. Failure to licence is a criminal offence and can result in a Rent Repayment Order requiring the landlord to refund up to 12 months of rent.

Related Reading

Furnished Holiday Lets — tax benefits and compliance | VAT and property — when does it apply? | Property records and Making Tax Digital

Frequently Asked Questions

Is Airbnb income taxed as a trade or rental income?

If you let a property short-term on Airbnb with cleaning, linen changes, and guest services, HMRC typically treats this as trading income. If you simply let the property without services and guests manage themselves, the distinction is less clear. The FHL tests (if applicable) provide the clearest framework — if those are not met, the income may be taxed as property investment income.


Do I need to register for VAT for my serviced accommodation?

Yes, once your gross turnover from short-term letting (including all SA and FHL income) exceeds £90,000 per year (2025/26 threshold), you must register for VAT and charge 20% on income. You can then reclaim VAT on all business expenses including cleaning, utilities, and refurbishments.


Can I claim capital allowances on my HMO furniture?

Not on standard buy-to-let HMO furniture. The Replacement of Domestic Items Relief allows a deduction only when you replace an existing item like-for-like — there are no capital allowances on initial furnishing costs. Serviced accommodation and FHL operators can claim capital allowances on all eligible fixtures and equipment.


What is a Rent Repayment Order and when can tenants apply for one?

A Rent Repayment Order (RRO) allows tenants to reclaim up to 12 months of rent from a landlord who has committed a housing offence — including operating an unlicensed HMO or failing to comply with an improvement notice. The First-Tier Tribunal can order repayment even where the landlord is later prosecuted.


Should I hold my HMO portfolio in a company or personally?

For higher-rate taxpayers with significant mortgage borrowing, a limited company typically provides substantially better returns: full interest deduction, 19–25% corporation tax versus 40–45% income tax, and greater extraction flexibility. The decision depends on current leverage, income needs, and long-term portfolio plans.


Don’t manage your serviced accommodation or HMO tax position without professional support. Book a consultation with Felix Accountants today.

Speak to an SA/HMO Tax Specialist


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

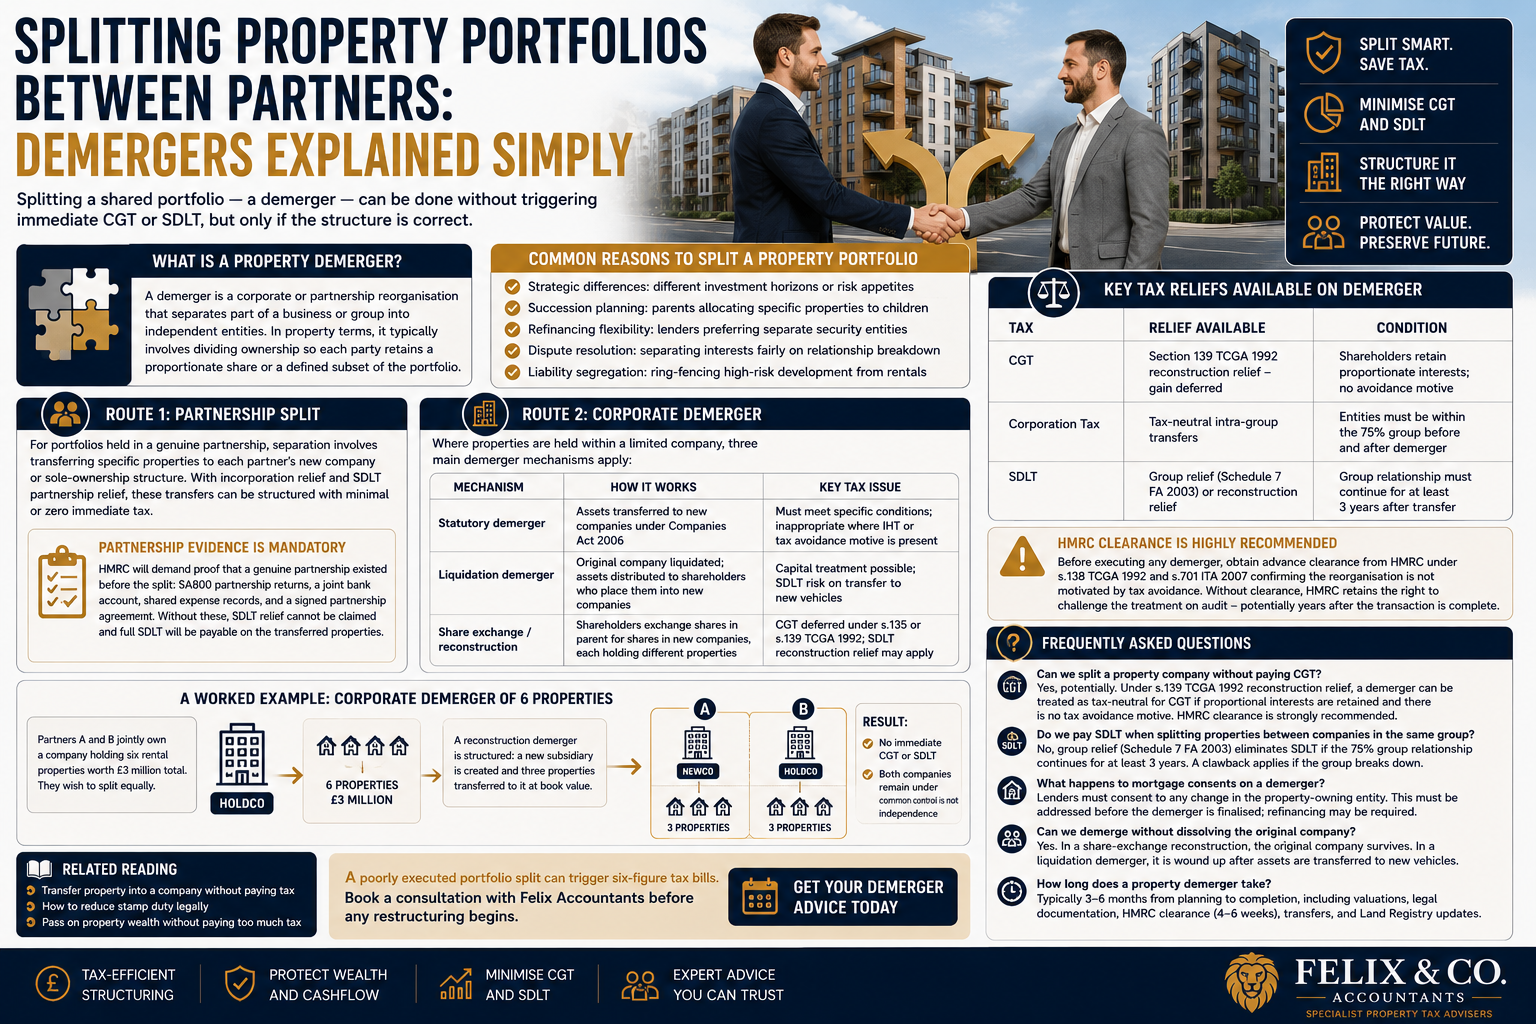
Splitting Property Portfolios Between Partners: Demergers Explained Simply

A property portfolio demerger allows property investors, business partners and family members to split shared property holdings in a tax-efficient way. As property partnerships evolve, partners often reach a point where their strategic objectives diverge. One wants to continue growing a rental portfolio; another wants to focus on development. Others simply wish to go their separate ways. Splitting a shared portfolio — a demerger — can be done without triggering immediate CGT or SDLT, but only if the structure is correct.

Property portfolio demerger

What Is a Property Portfolio Demerger?

A demerger is a corporate or partnership reorganisation that separates part of a business or group into independent entities. In property terms, it typically involves dividing ownership so each party retains a proportionate share or a defined subset of the portfolio.

Why Investors Use a Property Portfolio Demerger

  • Strategic differences: different investment horizons or risk appetites between partners
  • Succession planning: parents allocating specific properties to individual children
  • Refinancing flexibility: lenders preferring separate security entities per investor
  • Dispute resolution: separating interests fairly on relationship breakdown
  • Liability segregation: ring-fencing high-risk development projects from stable rental assets


Property Portfolio Demerger Through a Partnership Split

For portfolios held in a genuine partnership, separation involves transferring specific properties to each partner’s new company or sole-ownership structure. Where incorporation relief and SDLT partnership relief apply (as discussed in Chapter 4), these transfers can be structured with minimal or zero immediate tax.

Partnership Evidence Is Mandatory
HMRC will demand proof that a genuine partnership existed before the split: SA800 partnership returns, a joint bank account, shared expense records, and a signed partnership agreement. Without these, SDLT relief cannot be claimed and full SDLT will be payable on the transferred properties.


 Property Portfolio Demerger Through a Corporate Restructure

Where properties are held within a limited company, three main demerger mechanisms apply:

MechanismHow It WorksKey Tax Issue
Statutory demergerAssets transferred to new companies under Companies Act 2006Must meet specific conditions; inappropriate where IHT or tax avoidance motive is present
Liquidation demergerOriginal company liquidated; assets distributed to shareholders who place them into new companiesCapital treatment possible; SDLT risk on transfer to new vehicles
Share exchange / reconstructionShareholders exchange shares in parent for shares in new companies, each holding different propertiesCGT deferred under s.135 or s.139 TCGA 1992; SDLT reconstruction relief may apply


Key Tax Reliefs for a Property Portfolio Demerger

TaxRelief AvailableCondition
CGTSection 139 TCGA 1992 reconstruction relief — gain deferredShareholders retain proportionate interests; no avoidance motive
Corporation TaxTax-neutral intra-group transfersEntities must be within the 75% group before and after demerger
SDLTGroup relief (Schedule 7 FA 2003) or reconstruction reliefGroup relationship must continue for at least 3 years after transfer
HMRC Clearance Is Highly Recommended
Before executing any demerger, obtain advance clearance from HMRC under s.138 TCGA 1992 and s.701 ITA 2007 confirming the reorganisation is not motivated by tax avoidance. Without clearance, HMRC retains the right to challenge the treatment on audit — potentially years after the transaction is complete.


A Worked Example: Corporate Demerger of 6 Properties

Partners A and B jointly own a company holding six rental properties worth £3 million total. They wish to split equally. A reconstruction demerger is structured: a new subsidiary is created and three properties transferred to it at book value. A receives shares in the new subsidiary; B retains shares in the original company. Result: no immediate CGT or SDLT, both companies remain under common control until independence.

Related Reading

Transfer property into a company without paying tax | How to reduce stamp duty legally | Pass on property wealth without paying too much tax

Frequently Asked Questions

Can we split a property company without paying CGT?

Potentially, yes. Under s.139 TCGA 1992 reconstruction relief, a demerger structured so that shareholders retain proportionate interests in the separated entities can be treated as tax-neutral for CGT. The structure must not be motivated by tax avoidance, and advance HMRC clearance is strongly recommended.


Do we pay SDLT when splitting properties between companies in the same group?

Group relief (Schedule 7 FA 2003) eliminates SDLT on transfers between companies within the same 75% corporate group, provided the group relationship is maintained for at least three years after the transfer. A clawback applies if the group relationship breaks down within that period.


What happens to mortgage consents on a demerger?

Existing lenders must consent to any change in the property-owning entity. This is a practical constraint that must be addressed before the demerger structure is finalised. In some cases, refinancing is required, which can create additional cost and delay.


Can we demerge without dissolving the original company?

Yes. In a share-exchange reconstruction, the original company survives — shareholders simply swap some shares for shares in a newly created company. In a liquidation demerger, the original company is wound up, but properties transfer to the shareholders’ new vehicles before dissolution.


How long does a property demerger take?

A well-prepared demerger typically takes 3–6 months from initial planning to completion. This includes obtaining valuations, drafting legal documents, applying for HMRC clearance (which can take 4–6 weeks), executing the transfers, and registering new ownership at HM Land Registry.


A poorly executed portfolio split can trigger six-figure tax bills. Book a consultation with Felix Accountants before any restructuring begins.

Get Your Demerger Advice Today


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

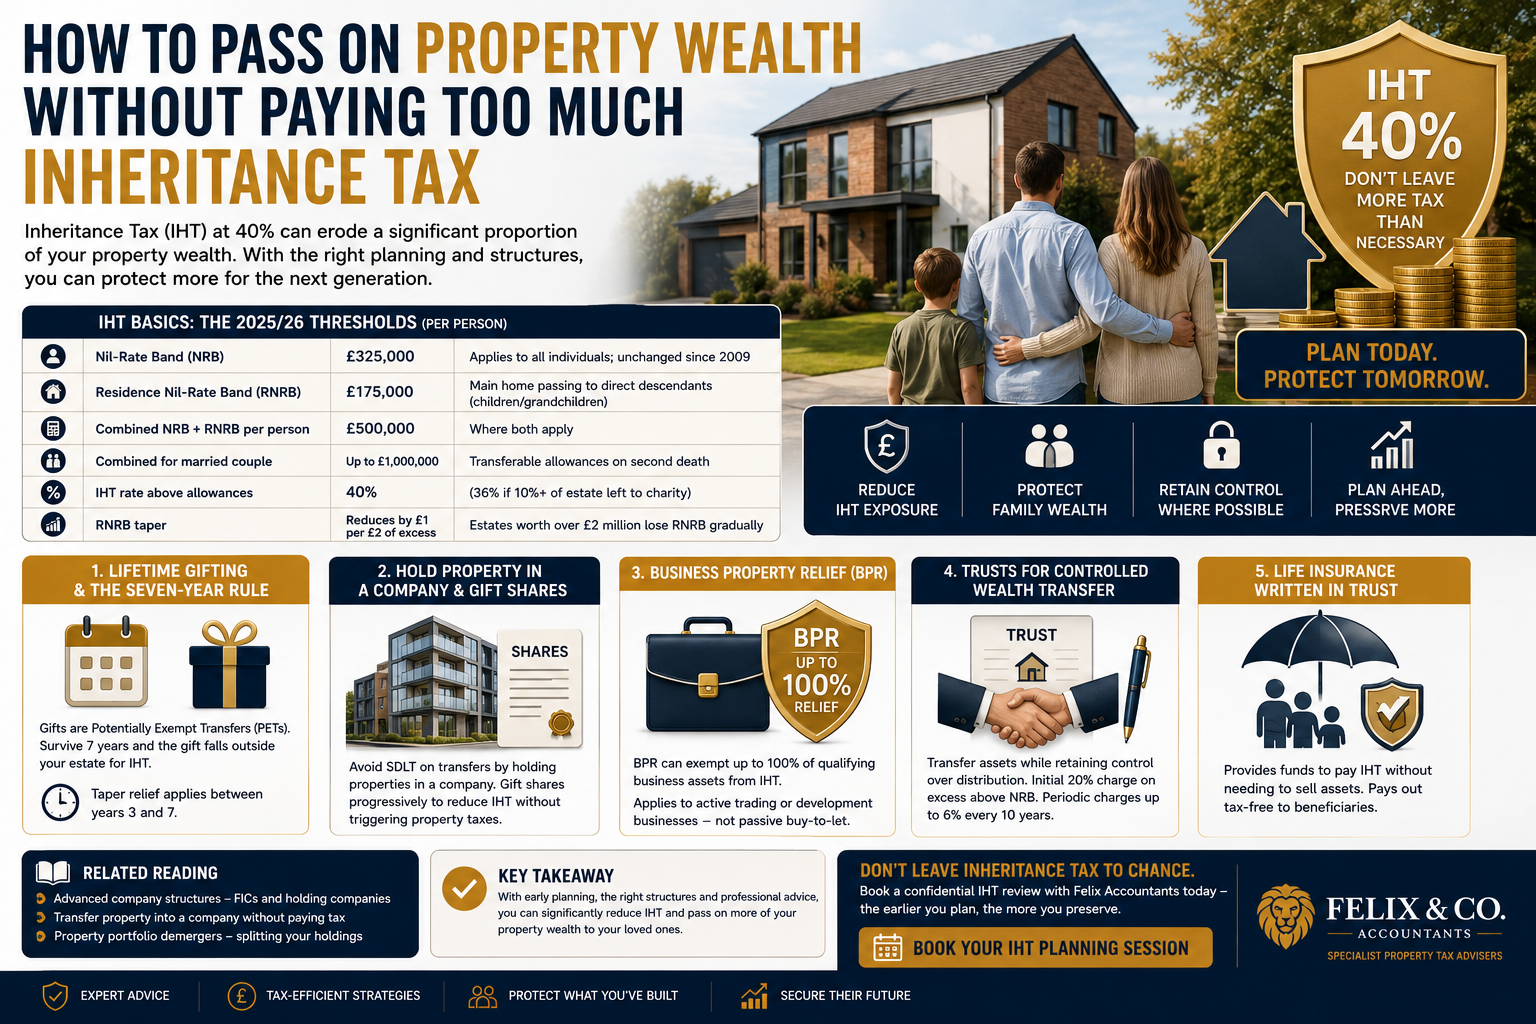
How to Pass On Property Wealth Without Paying Too Much Inheritance Tax

Property inheritance tax planning is an essential consideration for UK property investors who want to pass wealth to the next generation efficiently. Understanding the available reliefs, gifting rules, trusts and Business Property Relief opportunities can significantly reduce future inheritance tax liabilities. Building a property portfolio takes decades of disciplined investment. Passing it on efficiently requires equally disciplined planning. Inheritance Tax (IHT) at 40% threatens to erode a significant proportion of property wealth at the point of death — but with the right structures in place, the impact can be substantially reduced.

Property inheritance tax

 Property Inheritance Tax Thresholds for 2025/26

AllowanceAmount (per person)Condition
Nil-Rate Band (NRB)£325,000Applies to all individuals; unchanged since 2009
Residence Nil-Rate Band (RNRB)£175,000Main home passing to direct descendants (children/grandchildren)
Combined NRB + RNRB per person£500,000Where both apply
Combined for married coupleUp to £1,000,000Transferable allowances on second death
IHT rate above allowances40%(36% if 10%+ of estate left to charity)
RNRB taperReduces by £1 per £2 of excessEstates worth over £2 million lose RNRB gradually


Strategy 1: Property Inheritance Tax Strategy: Lifetime Gifting and the Seven-Year Rule

Gifts made during your lifetime are treated as Potentially Exempt Transfers (PETs). If you survive seven years after making the gift, the value falls completely outside your estate for IHT purposes. Between years 3 and 7, taper relief reduces the effective IHT rate on the gift.

Years Since GiftIHT Taper ReliefEffective IHT Rate
Under 3 years0%40% of value
3 to 4 years20%32% of value
4 to 5 years40%24% of value
5 to 6 years60%16% of value
6 to 7 years80%8% of value
Over 7 years100% exempt0%

gov.uk/inheritance-tax/gifts


Strategy 2: Property Inheritance Tax Strategy: Gifting Company Shares

Transferring individual properties triggers SDLT and CGT. Transferring shares in a company holding the properties does not trigger SDLT. By holding properties within a company and then gifting shares progressively to children, you can reduce IHT exposure over time without triggering property-level taxes on each transfer.

Strategy 3: Property Inheritance Tax Relief Through Business Property Relief (BPR)

BPR can exempt up to 100% of qualifying business assets from IHT. For property investors, BPR applies to active property trading or development businesses — not passive buy-to-let portfolios. HMRC scrutinises BPR claims carefully and has challenged passive landlords asserting BPR on long-term investment portfolios.

ActivityBPR EligibilityKey Requirement
Long-term residential rentalVery unlikelyHMRC treats as passive investment, not a trading business
Furnished Holiday LetsPossible — if genuinely commercialMust demonstrate substantial management activity akin to a hotel business
Active property developmentLikely — if genuine trading activityClear development intent, trading records, and staff/subcontractors
Serviced accommodation businessPossible — requires evidence of hotel-like operationsRegular guest services, active management, and commerciality


Strategy 4: Property Inheritance Tax Planning with Trusts

Relevant property trusts allow you to transfer assets while retaining some control over their eventual distribution. The initial transfer is a Chargeable Lifetime Transfer (CLT) — subject to an immediate 20% IHT charge on the excess above the NRB. Periodic charges of up to 6% apply every 10 years. Despite this, trusts offer strong asset-protection and succession benefits for larger estates.

Strategy 5: Property Inheritance Tax Protection with Life Insurance Trusts

A life insurance policy written in trust falls outside the estate and pays out directly to beneficiaries to meet the IHT liability — without requiring a property sale. The cost of premiums is predictable, and the benefit on death is immediate and tax-free to the recipient.

Related Reading

Advanced company structures — FICs and holding companies | Transfer property into a company without paying tax | Property portfolio demergers — splitting your holdings

Frequently Asked Questions

Is rental property subject to inheritance tax?

Yes. Investment property is included in your estate at market value on death. There is no automatic relief for investment property — only your nil-rate band (£325,000) and residence nil-rate band (£175,000 where applicable) reduce the chargeable estate.


Can I gift my buy-to-let properties to my children?

Yes, but the gift is treated as a disposal at market value — triggering CGT on any gain. The property also does not avoid IHT unless you survive seven years after the gift. Gifting company shares (where property is held corporately) is often more efficient.


What is the Residence Nil-Rate Band and do I qualify?

The RNRB (£175,000 per person, £350,000 for a couple) is an additional IHT-free allowance for estates where the main home passes to direct descendants (children, step-children, grandchildren). It tapers for estates above £2 million and is lost entirely if you do not have a qualifying residential interest.


Do landlords qualify for Business Property Relief?

Not typically for standard buy-to-let portfolios. HMRC treats passive rental income as investment rather than trading activity. FHLs and development businesses have a stronger (though not guaranteed) case. Professional review and contemporaneous evidence of commercial activity is essential before relying on BPR.


How can I plan for IHT without giving up control of my properties?

A Family Investment Company (FIC) allows parents to retain voting control (and therefore property decisions) while gifting growth shares to children. Alternatively, a trust allows you to transfer legal ownership of assets while trustees (potentially including yourself) manage distribution. Both require specialist drafting.


Don’t leave inheritance tax to chance. Book a confidential IHT review with Felix Accountants today — the earlier you plan, the more you preserve.

Book Your IHT Planning Session


JSON-LD Schema Markup

Categories
Articles Articles Blogs Guides

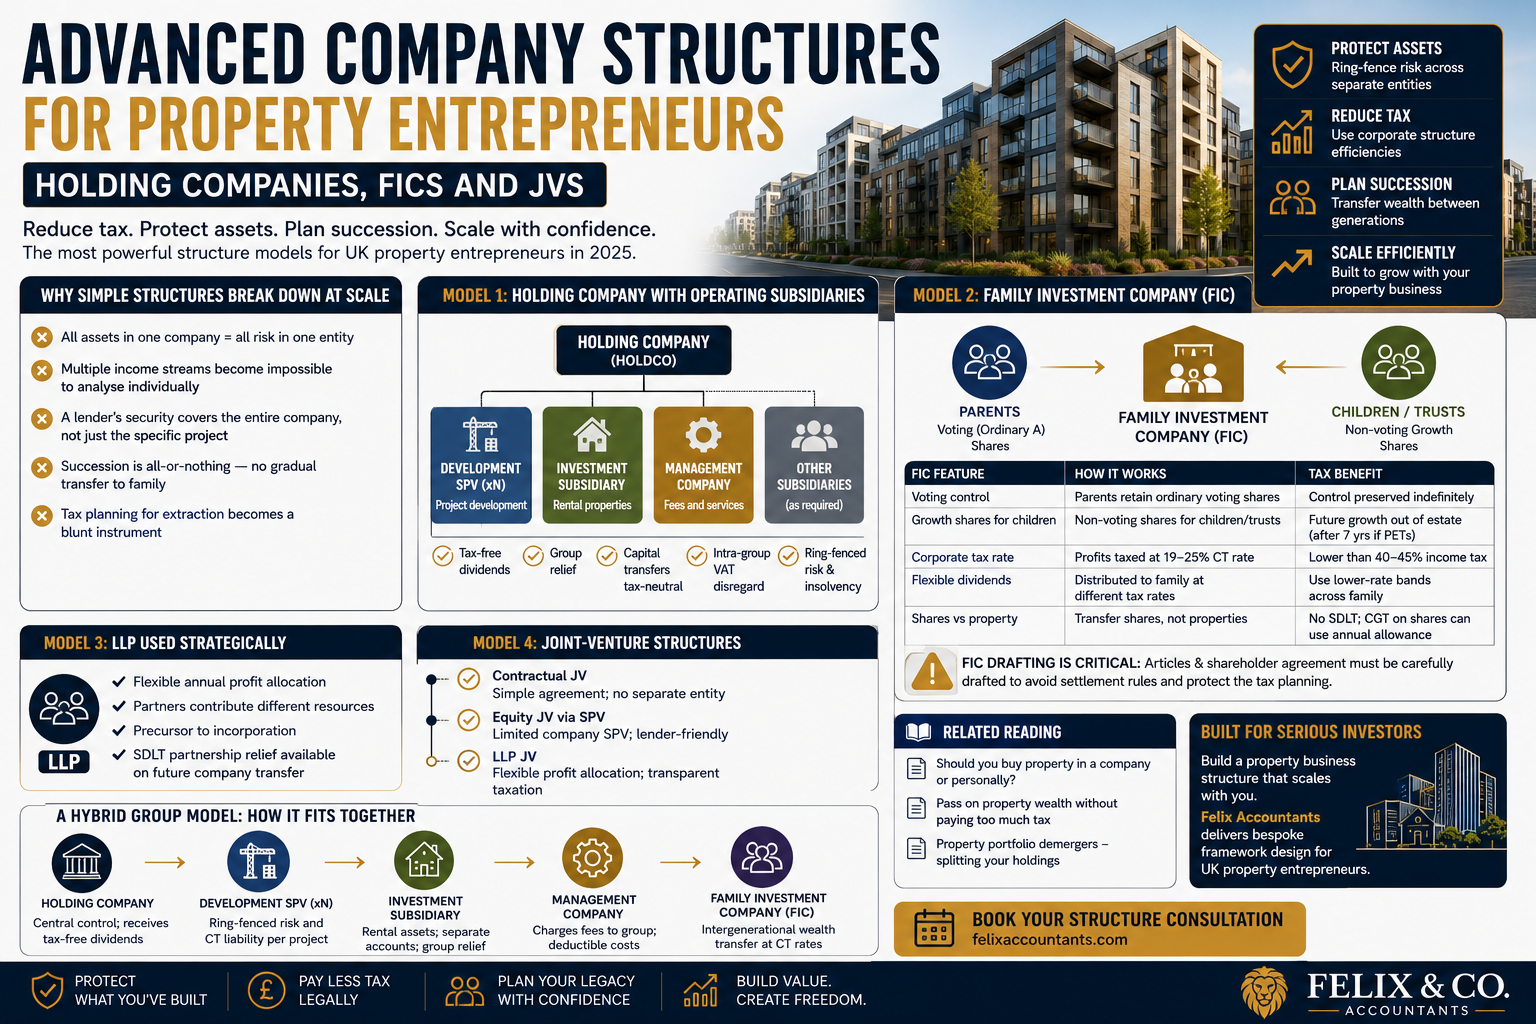
Advanced Company Structures for Property Entrepreneurs: Holding Companies, FICs and JVs

Advanced property company structures help UK property entrepreneurs reduce tax, protect assets, improve succession planning and scale portfolios more efficiently. As property businesses grow, simple limited company structures often become restrictive. Advanced property company structures such as holding companies, Family Investment Companies (FICs), LLPs and joint-venture SPVs provide greater flexibility, stronger risk protection and improved long-term tax efficiency. This guide explains the most effective structures available to UK property investors in 2025.

Advanced Property Company Structures

Why Advanced Property Company Structures Matter

  • All assets in one company = all risk in one entity
  • Multiple income streams become impossible to analyse individually
  • A lender’s security covers the entire company, not just the specific project
  • Succession is all-or-nothing — no gradual transfer to family
  • Tax planning for extraction becomes a blunt instrument


Model 1: Advanced Property Company Structures: Holding Companies

A holding company (Holdco) owns the shares of multiple subsidiary companies — each focused on a distinct activity: development SPV, investment subsidiary for long-term rentals, and a management company charging fees across the group. Benefits include:

  • Dividends flow between UK group companies free of corporation tax (UK’s participation exemption)
  • Losses in one subsidiary can be surrendered to profitable ones via group relief
  • Capital transfers between group companies are tax-neutral if within a 75% group
  • Intra-group VAT disregard where a VAT group election is in place
  • Insolvency of one subsidiary does not affect others


Model 2: Advanced Property Company Structures: Family Investment Companies (FICs)

An FIC is a bespoke limited company used to transfer property wealth between generations while retaining parental control. The typical structure: parents hold voting-only (ordinary A) shares; children hold non-voting growth shares that capture future capital appreciation.

FIC FeatureHow It WorksTax Benefit
Voting controlParents retain ordinary voting sharesDecision-making control preserved indefinitely
Growth shares for childrenNon-voting shares allocated to children/trustsFuture growth passes to next generation free of IHT after 7 years if gifted as PETs
Corporate tax rateProfits taxed at 19–25% CT rateLower than personal 40–45% income tax on same profits
Flexible dividendsDistributed to family members at different tax ratesUtilise lower-rate bands across the family
Shares vs propertyTransfer shares rather than propertiesNo SDLT; CGT on shares can be annual-allowance managed
FIC Drafting Is Critical
The Articles of Association and shareholder agreement must precisely define voting rights, dividend rights, transfer restrictions, and what happens on death or relationship breakdown. A poorly drafted FIC can inadvertently trigger the settlement rules, defeating the tax planning purpose. Always use an experienced solicitor and tax adviser in tandem.


Model 3: Advanced Property Company Structures Using LLPs

LLPs remain relevant in advanced structures where: flexible annual profit allocation is needed; partners contribute different resources; or the structure is designed as a precursor to incorporation, with SDLT partnership relief available on the subsequent company transfer.

Model 4: Advanced Property Company Structures for Joint Ventures

Large developments often require collaboration between landowners, capital investors, and development managers. Three main structures are used:

  • Contractual JV — parties collaborate under a single agreement without a separate entity; simpler but less lender-friendly
  • Equity JV via a limited company SPV — each party holds shares proportionate to capital input; clean for lender security
  • LLP JV — flexible profit allocation in variable ratios; transparent taxation for partners


A Hybrid Group Model: How It Fits Together

EntityRoleKey Tax Purpose
Holding companyOwns all subsidiaries; receives tax-free inter-company dividendsCentral control; estate planning anchor
Development SPV (×N)Each holds one development projectRing-fenced risk and CT liability per project
Investment subsidiaryHolds long-term rental propertiesSeparate accounting; group relief available
Management companyCharges fees to group for servicesDeductible costs; income splitting where legitimate
Family Investment CompanyHolds residential or stable commercial assetsIntergenerational wealth transfer at CT rates

Related Reading

Should you buy property in a company or personally? | Pass on property wealth without paying too much tax | Property portfolio demergers — splitting your holdings

Frequently Asked Questions

What is a Family Investment Company and is it still valid after the 2024 Budget?

A FIC remains a legitimate and widely used planning tool. The 2024 Autumn Budget tightened some IHT rules (including future pension IHT changes from 2027) but did not abolish FICs. They continue to offer significant advantages for corporate-rate profit retention and intergenerational share gifting.


Can I extract profits from a holding company more efficiently than a trading company?

Yes. A holding company receiving dividends from subsidiaries pays no corporation tax on those dividends (UK participation exemption). It can then make pension contributions, pay a controlled salary, or reinvest — all at the Holdco level — before any personal extraction.


What is group relief and how does it help a property group?

Group relief (CTA 2010 s.97) allows losses in one 75%-owned group company to be surrendered to offset profits in another, reducing the group’s overall CT liability in the year. This is particularly valuable when one development SPV makes a loss in the same year that others are profitable.


Are LLPs still used in property structures?

Yes — particularly where flexible annual profit allocation between partners is required, or as a stepping stone to incorporation. An LLP operating as a genuine property business can later be incorporated with SDLT partnership relief applying to the transfer.


How should I document inter-company transactions in a group?

Every inter-company loan, management charge, rent, and dividend must be documented by a formal agreement. HMRC may challenge arrangements where transactions appear uncommercial. The transfer pricing rules (TIOPA 2010) require arm’s-length pricing for transactions between connected parties in a UK group.


Build a property business structure that scales with you. Felix Accountants delivers bespoke framework design for serious UK investors.

Book Your Structure Consultation


JSON-LD Schema Markup